The Short Answers
- A free printable net worth worksheet is a template that lists your assets (cash, investments, property) and liabilities (debts, loans) to calculate your net worth—a single number that defines your financial health.
- You can find high-quality templates from reputable sources like the Federal Reserve, NerdWallet, or Mint, all of which offer downloadable versions without subscription fees.
- Update your worksheet quarterly at minimum, or after major life events (marriage, inheritance, job change). Ignoring this schedule turns the tool into a historical artifact.
- Common mistakes include underestimating assets (e.g., forgetting about retirement accounts), overestimating liabilities (e.g., counting student loans twice), or failing to adjust for inflation—all of which skew your true financial picture.

Deep Dive: The Full Picture
A net worth worksheet isn’t just a spreadsheet—it’s a financial X-ray. The number it produces isn’t about vanity; it’s about risk assessment. For example, a couple in their 40s with a net worth of $500,000 might feel secure, but if $400,000 of that is tied to a single property in a declining market, their real liquidity is far lower. The worksheet forces you to categorize assets by liquidity: cash and investments move quickly; a primary residence does not. Liabilities, meanwhile, aren’t just numbers—they’re obligations with interest rates, repayment timelines, and potential penalties. A free printable net worth worksheet from the Consumer Financial Protection Bureau (CFPB) includes fields for these nuances, not just totals. The psychological impact is often underestimated. Many people avoid calculating their net worth because the number feels too real. A negative net worth isn’t a failure—it’s data. It signals that debt reduction or income growth should be priorities. Conversely, a positive net worth doesn’t mean you’re rich; it means you’ve built a foundation. The worksheet’s value lies in its clarity. When you see your 401(k) balance, your credit card debt, and your emergency fund in one place, you can’t ignore the gaps. This is why financial advisors recommend starting with a net worth statement before diving into complex strategies like tax-loss harvesting or real estate investments.The Context You Need
Net worth tracking has roots in industrial-era accounting, when businesses used balance sheets to assess solvency. Personal finance adapted the concept in the 1970s as credit cards and mortgages became mainstream. The rise of the internet democratized access to tools, but the core principle remained: know your numbers. Today, a free printable net worth worksheet serves two audiences. For beginners, it’s a crash course in financial literacy. For seasoned investors, it’s a sanity check. The worksheet’s simplicity is its superpower—no jargon, no algorithms, just cold, hard categories. Yet, the tool’s effectiveness hinges on one critical factor: accuracy. A worksheet is only as good as the data you input. Misspelled account numbers, outdated balances, or forgotten assets (like a forgotten savings bond) create a distorted view. This is why templates from institutions like the IRS or the Securities and Exchange Commission (SEC) are preferred—they’re designed to minimize errors. For example, the SEC’s Investor.gov offers a net worth calculator that prompts users to include often-overlooked items like cryptocurrency or collectibles. The goal isn’t perfection; it’s consistency.The Mechanics
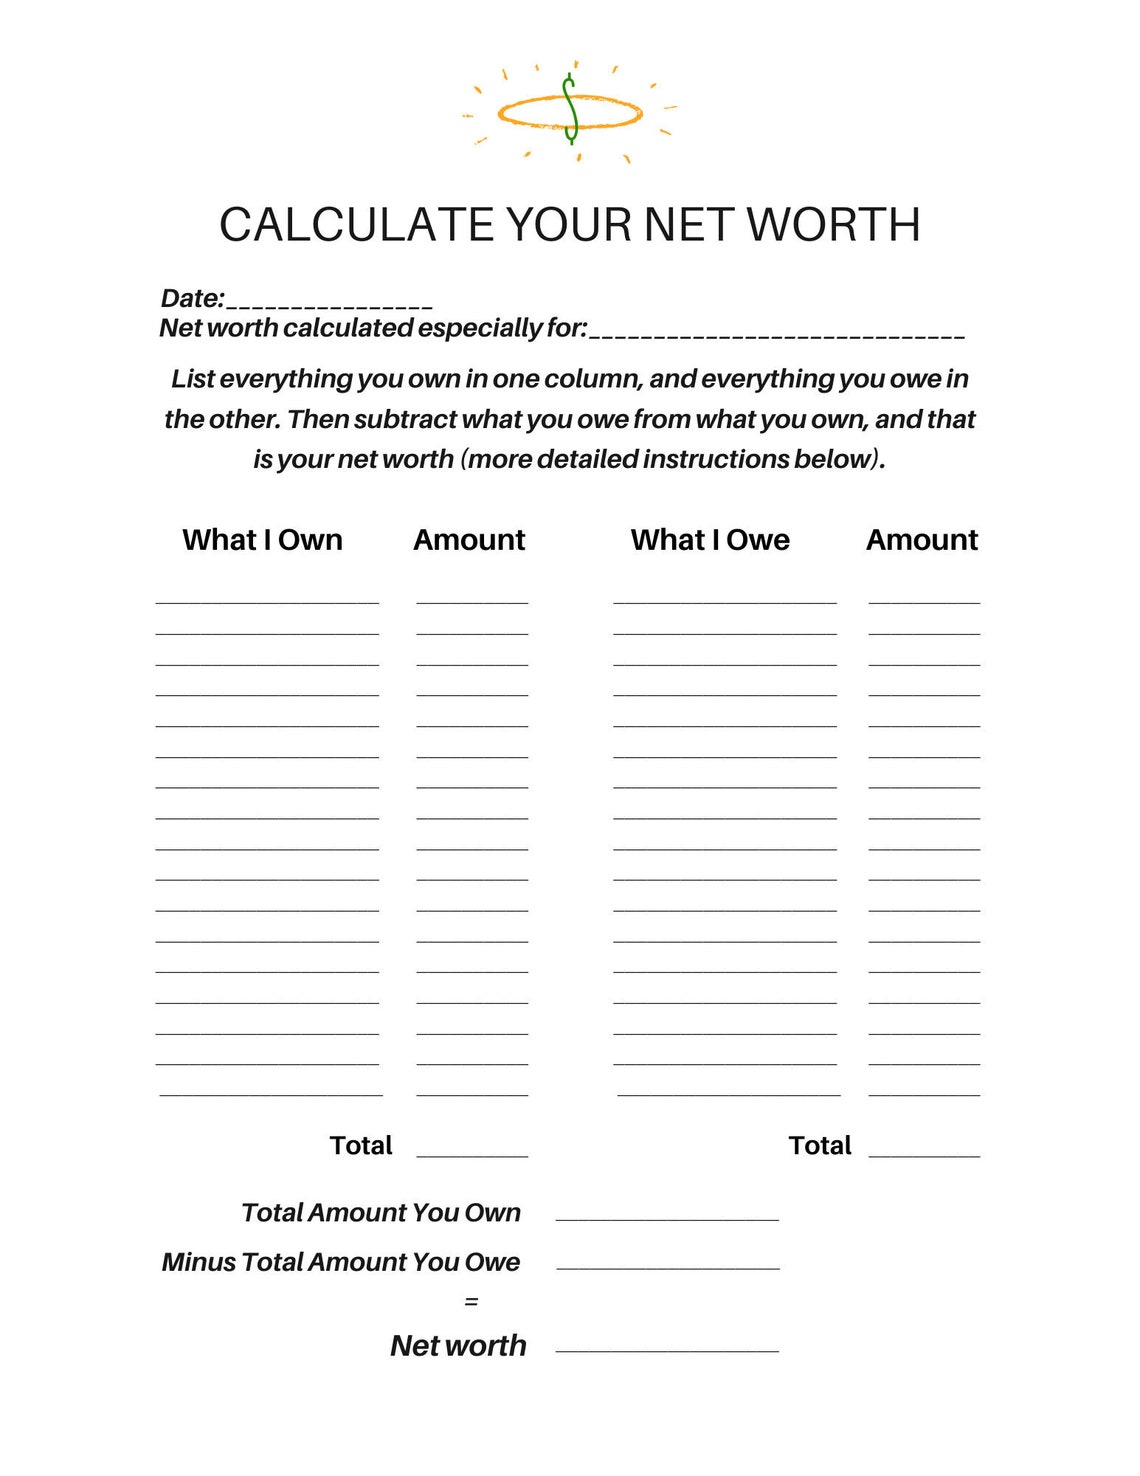
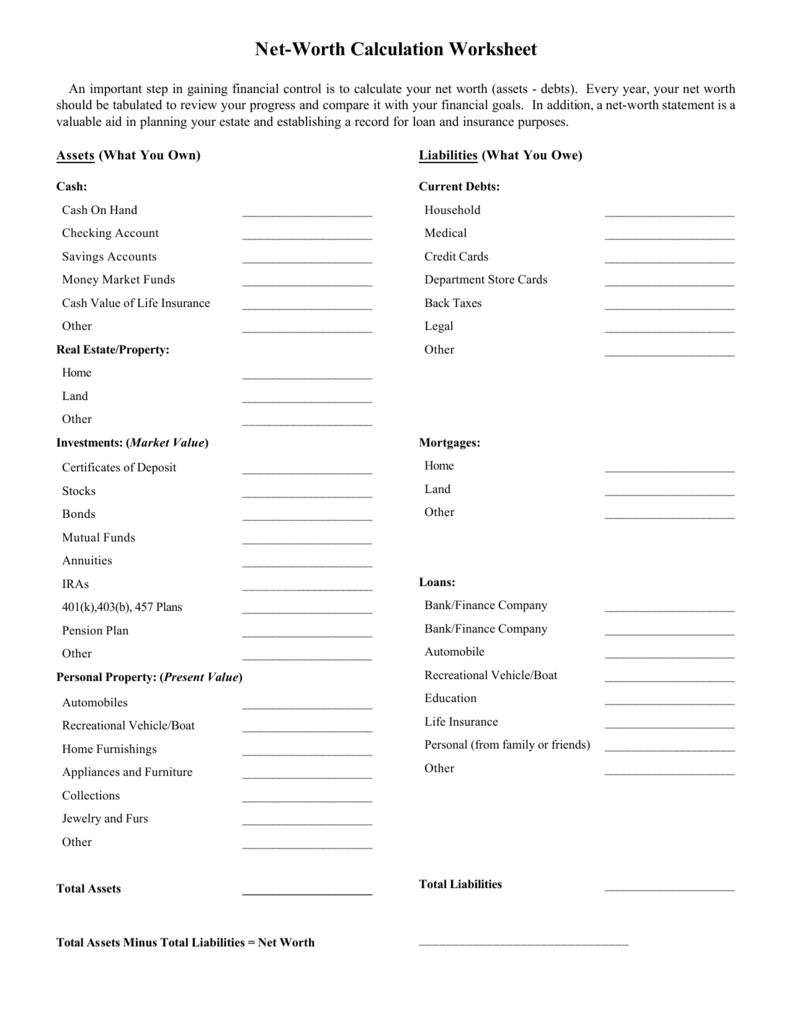
The mechanics of a net worth worksheet are deceptively simple. At its core, it’s a T-account: assets on one side, liabilities on the other. The formula is net worth = total assets – total liabilities. But the devil is in the details. Assets are divided into current (cash, checking/savings) and non-current (retirement accounts, real estate). Liabilities split into current (credit card balances, short-term loans) and long-term (mortgages, student loans). A well-designed free printable net worth worksheet from the CFPB includes columns for: - Date of calculation (to track progress over time) - Category (e.g., "Investments," "Auto Loans") - Current value (not purchase price) - Notes (e.g., "Mortgage interest rate: 3.5%") The key step most people skip? Revaluing assets annually. A stock portfolio worth $100,000 in 2020 might be $120,000 in 2024—but if you don’t update the worksheet, you’re working with stale data. Tools like Personal Capital or YNAB automate this, but a printable version requires manual discipline. The trade-off? You gain a deeper understanding of where your wealth comes from.Details That Change the Picture
Not all net worth worksheets are created equal. A template from a credit counseling agency might emphasize debt reduction, while one from a wealth management firm could focus on asset diversification. The difference lies in the hidden assumptions baked into the categories. For instance, some worksheets lump "other assets" into a single line, which can obscure valuable insights—like realizing that a vintage car collection is your largest asset. Others separate human capital (future earning potential) from financial assets, a distinction critical for young professionals or freelancers. The real game-changer? Comparing your worksheet to benchmarks. Industry data suggests that the median net worth for a 35-year-old in the U.S. hovers around $91,300, but this varies wildly by region and income level. A free printable net worth worksheet from the Federal Reserve’s Report on the Economic Well-Being of U.S. Households includes percentile rankings, letting you see how you stack up. This isn’t about keeping up with the Joneses; it’s about identifying outliers—like a high student loan balance or an unexpected windfall—that need attention."A net worth statement is like a financial GPS. It doesn’t tell you where to go, but it shows you exactly where you are—and whether you’re heading toward a cliff or a clear road." —Suze Orman, financial advisor and author of The Ultimate Retirement Guide for 50+
| Common Pitfall | How to Avoid It |
|---|---|
| Underestimating illiquid assets (e.g., a home’s true market value). | Use Zillow or Redfin for home valuations; consult a real estate agent for high-end properties. |
| Overlooking intangible assets (e.g., a business ownership stake). | Include a "Notes" column to describe non-standard assets and their estimated values. |
| Ignoring inflation’s impact on long-term liabilities (e.g., a 30-year mortgage). | Adjust for inflation annually using the CPI calculator from the Bureau of Labor Statistics. |
| Treating the worksheet as a one-time project. | Set calendar reminders for quarterly updates; link it to major life events (e.g., tax season). |
Conclusion
A free printable net worth worksheet is the financial equivalent of a mirror: it reflects reality, not your aspirations. The mistake isn’t in using one—it’s in using it incorrectly. Too many people treat it as a chore, filling in numbers without context. The truth is, the worksheet’s real value lies in the conversations it sparks. Why is your emergency fund lower than expected? Why does your debt-to-asset ratio feel precarious? These aren’t questions for a spreadsheet—they’re prompts for action. The best worksheets, like those from the CFPB or the Financial Industry Regulatory Authority (FINRA), include space for goals. That’s where the magic happens: connecting the numbers to your life. Start with a template, but don’t stop there. Pair it with a simple tracking system—even a shared Google Sheet—so you can monitor trends. Over time, you’ll notice patterns: perhaps your net worth grows steadily, or it stagnates during economic downturns. The worksheet doesn’t judge; it informs. And in a world where financial advice is often conflated with product sales, that clarity is priceless.Comprehensive FAQs
Q: Where can I find a legitimate free printable net worth worksheet?
A: Reputable sources include the Consumer Financial Protection Bureau (CFPB), SEC Investor.gov, and NerdWallet. Avoid templates from unknown websites that require personal data to download—stick to .pdf or .xlsx files with no login walls.
Q: Do I need to include every single asset, even small ones?
A: Yes, but with context. List items worth $500 or more; for smaller assets (e.g., a $200 bike), group them under "Miscellaneous Assets" with a total value. The goal is accuracy, not perfection. If you’re unsure about an item’s value, err on the conservative side and note it for future review.
Q: How often should I update my net worth worksheet?
A: At minimum, quarterly. However, trigger updates for major events: receiving an inheritance, refinancing a loan, or taking on a new debt. Market volatility (e.g., during a recession) also warrants a review. The more frequently you update, the more useful the data becomes for tracking progress.
Q: What if my net worth is negative? Is this a red flag?
A: Not necessarily. A negative net worth is common for young adults, students, or those with significant debt (e.g., mortgages or medical bills). The red flag isn’t the number itself—it’s the trend. If your net worth is improving (e.g., debt decreasing faster than assets grow), you’re on the right track. If it’s worsening, focus on high-interest debt repayment or increasing income.
Q: Can I use a free printable net worth worksheet if I have complex assets (e.g., a business, rental properties)?
A: Yes, but you’ll need to adapt it. For businesses, include separate lines for assets (equipment, inventory) and liabilities (loans, payroll taxes). For rental properties, list each property’s current market value, mortgage balance, and rental income. Consult a CPA or financial advisor to ensure you’re categorizing correctly—especially for depreciable assets.
Q: Are there any tax implications to tracking my net worth?
A: No, but accuracy matters for tax purposes. For example, if you underreport the value of a rental property, you might miscalculate depreciation deductions. Always use current market values (not purchase prices) for assets like real estate or collectibles. If you’re unsure, consult the IRS’s publications on asset valuation.
Q: How do I explain my net worth to a partner or spouse if we’re combining finances?
A: Start with transparency. Share your individual worksheets, then create a joint net worth statement that combines assets (e.g., shared bank accounts, joint investments) and liabilities (e.g., mortgages, student loans). Use the worksheet to discuss goals—like saving for a home or retirement—and align on priorities. Disagreements often stem from differing risk tolerances, not the numbers themselves.
Q: What’s the best way to store my net worth worksheets over time?
A: Use a secure, organized system. Options include:
- A password-protected digital folder (e.g., Google Drive or Dropbox) with yearly subfolders.
- A physical binder with carbon copies (for those who prefer paper trails).
- A spreadsheet tool like Excel or Google Sheets with version history enabled.
