
The Short Answers
- A decrease in net worth could be the result of: outflows—most often from unplanned expenses, tax drag, or asset liquidations forced by leverage.
- Lifestyle inflation (e.g., upgrading homes, cars, or subscriptions) is a top silent killer for those earning above median incomes.
- Investment-related outflows—like management fees, capital gains taxes, or redemption penalties—can erode returns by 1–3% annually.
- Legal and administrative costs (estate planning, divorces, lawsuits) frequently exceed 10% of the contested asset’s value.
- Market timing failures (buying high, selling low) often stem from emotional reactions to outflows, like panic withdrawals during downturns.
- Opportunity cost—capital locked in low-yielding assets or illiquid ventures—can be just as damaging as direct losses.
Deep Dive: The Full Picture
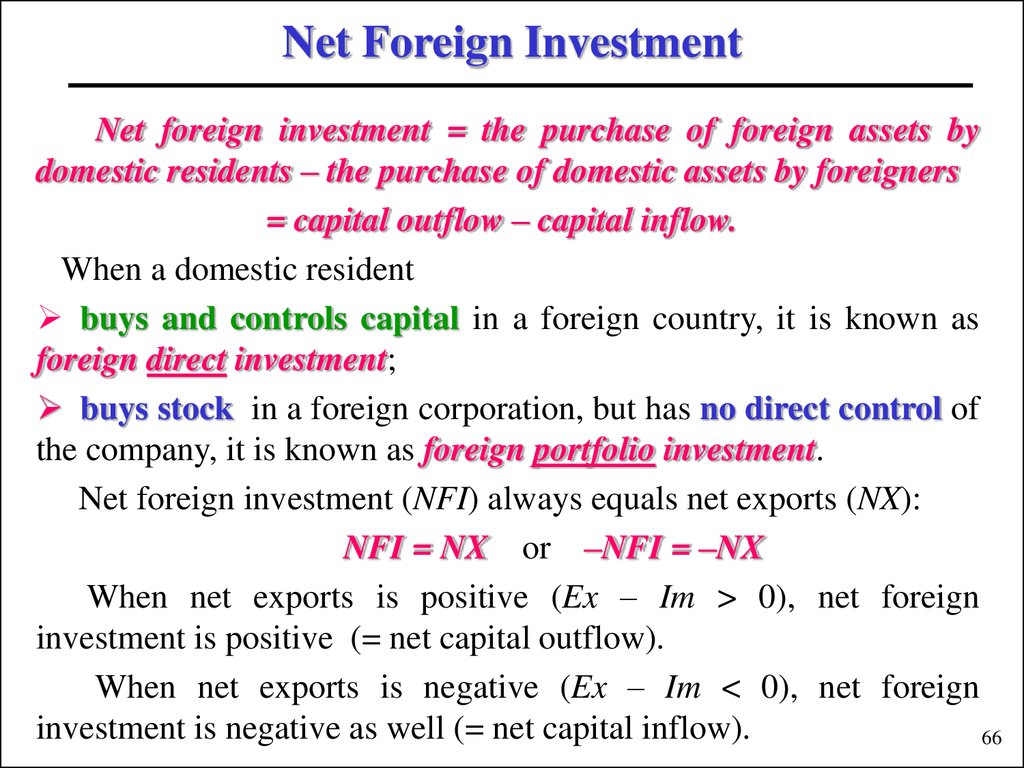
Wealth isn’t just about what you own; it’s about what you don’t lose. The most resilient portfolios aren’t those with the highest returns, but those that minimize unforced outflows. Consider the case of a tech executive who saw their net worth drop by 30% in 18 months. The stock market contributed—their company’s valuation dipped—but the real damage came from three parallel outflows: a divorce settlement that took 25% of liquid assets, a failed angel investment that required a $500,000 injection, and escalating private school tuition for their children. Each outflow was manageable alone, but together they created a cash-flow vortex. The psychology of outflows is understudied. Humans are wired to focus on gains, not losses, yet it’s the unseen drains that redefine net worth. A study of ultra-high-net-worth families found that 60% of wealth erosion wasn’t due to poor investment choices, but to lifestyle creep—spending increases that outpaced income growth. Another layer is tax-induced outflows: capital gains taxes on forced sales, estate taxes on inherited assets, or even the silent tax of opportunity cost when capital sits idle in low-return accounts. The wealthiest individuals often insulate themselves from these risks through trusts, tax-loss harvesting, and dedicated cash reserves—but for the majority, outflows are the default risk.The Context You Need
Not all outflows are created equal. Structural outflows—like mandatory payments (mortgages, alimony, child support)—are predictable but can still derail net worth if not offset by proportional inflows. Discretionary outflows, however, are where most erosion happens. A family might allocate 5% of income to dining out, only to realize that figure balloons to 15% after adding subscriptions, travel, and impulse purchases. The problem escalates when discretionary spending correlates with asset appreciation: people spend more when their portfolio grows, assuming the gains will cover the outflows—until they don’t. The timing of outflows also distorts perception. A sudden large outflow—like a $200,000 medical bill—is jarring, but a series of small, recurring ones (gym memberships, streaming services, "investment" seminars) can go unnoticed until a portfolio review reveals a net worth that’s 20% below projections. The most insidious outflows are those tied to social pressure: keeping up with peers, funding children’s extracurriculars, or maintaining multiple properties that generate little income but require constant upkeep. These aren’t just spending habits; they’re wealth-dilution strategies disguised as lifestyle choices.The Mechanics
The math behind outflows is simple but often ignored. Net worth = Assets – Liabilities. Outflows reduce assets (via sales or depreciation) or increase liabilities (via debt or obligations). The critical variable is cash flow velocity: how quickly outflows deplete liquidity before new inflows arrive. A freelancer with a $500,000 portfolio might see their net worth shrink by $100,000 in a year not because of poor returns, but because client payments slowed while personal expenses remained fixed. The outflow wasn’t a single event—it was a cash-flow mismatch. Taxes are the most invisible outflow. Even passive investors face tax drag: unrealized gains become taxable when assets are sold, and long-term capital gains taxes can turn a 10% paper gain into a 5% net loss after fees. High-income earners also face bracket creep, where rising incomes push them into higher tax rates, effectively increasing the outflow percentage. Then there are hidden fees: mutual fund expense ratios, custodial costs, and even the opportunity cost of cash sitting in low-yield accounts while inflation erodes purchasing power. These outflows aren’t line items on a statement—they’re silent partners in wealth erosion.Details That Change the Picture
The difference between a stable net worth and one in decline often comes down to leverage. A highly leveraged real estate investor might see their portfolio grow on paper, but if rental income doesn’t cover debt service, the net outflow from the property is masked by the asset’s appreciation. The same applies to private equity: dry powder (uninvested capital) can look like an asset, but if it’s tied up for years, it’s effectively an opportunity-cost outflow. Even "safe" investments like bonds can become liabilities if interest rates rise, forcing investors to sell at a loss to rebalance—turning a fixed-income outflow into a capital outflow. Another critical factor is behavioral drift. Investors who experience a net worth decline often double down on risky assets to recover losses, only to accelerate outflows when those assets underperform. The disposition effect—holding losers too long and selling winners too soon—creates a feedback loop where outflows (from forced sales) trigger more outflows (from emotional decisions). High-net-worth individuals aren’t immune; in fact, they may face greater psychological pressure to "keep up" appearances, leading to larger, riskier outflows in an attempt to restore perceived status."Wealth isn’t about how much you make; it’s about how much you don’t lose. The richest people I’ve worked with don’t chase returns—they chase outflow control."
—Financial advisor to Fortune 500 executives (anonymized)
| Outflow Type | Real-World Example |
|---|---|
| Structural | A $12,000/month mortgage on a $2M property where rental income covers only $8,000. |
| Discretionary | Annual spending on luxury cars, private schooling, and vacations that exceeds 40% of take-home pay. |
| Tax-Induced | Selling a $500K stock at a $100K gain, only to pay $30K in capital gains taxes, netting $70K instead. |
| Opportunity Cost | Keeping $1M in a 1% yield savings account while inflation runs at 3%, costing ~$20K/year in lost purchasing power. |
| Legal/Administrative | A divorce settlement where legal fees and asset division reduce a $3M portfolio to $2.2M net. |
Conclusion
The most dangerous outflows are the ones you don’t see coming. They’re not the dramatic market crashes or the high-profile bankruptcies—they’re the quiet leaks in the system: the unbudgeted repair bill, the fee you forgot to negotiate, the asset that drains cash instead of generating it. The solution isn’t to eliminate all outflows (that’s impossible) but to reclassify them. Treat discretionary spending as a line item in your net worth equation. Audit your tax strategy like you would an investment. And recognize that liquidity is the new leverage: the ability to absorb outflows without selling assets at a loss is the true measure of financial resilience. The irony is that the more wealth you accumulate, the more outflows you attract. High net worth doesn’t protect you—it amplifies the consequences of poor outflow management. The goal isn’t to live like a miser, but to optimize the balance. A decrease in net worth could be the result of: outflows, yes—but it’s also the result of not accounting for them early enough.Comprehensive FAQs
Q: Can a decrease in net worth happen even if my investments are growing?
A: Absolutely. If your discretionary spending or liabilities grow faster than your asset appreciation, net worth can shrink even with a rising portfolio. For example, if your home value increases by 5% but your mortgage payments, property taxes, and maintenance costs rise by 7%, your net equity in the property declines. Similarly, if you take on new debt (e.g., a second mortgage, student loans for children) while asset growth lags, the outflow from interest payments can outweigh gains.
Q: How do I identify hidden outflows I’m not tracking?
A: Start with a cash-flow audit: categorize every expense for three months, then compare it to your income. Look for:
- Recurring subscriptions or memberships you’ve forgotten about.
- Opportunity costs (e.g., cash sitting in low-yield accounts).
- Tax inefficiencies (e.g., holding investments in tax-inefficient accounts).
- Lifestyle inflation tied to asset appreciation (e.g., upgrading cars/homes when your portfolio grows).
Q: Is it better to avoid outflows entirely, or to structure them strategically?
A: Avoiding all outflows is impractical and often counterproductive (e.g., hoarding cash during inflation). The key is strategic structuring:
- Tax-efficient outflows: Harvest losses to offset gains, use tax-advantaged accounts (401(k), IRA) for discretionary spending.
- Liquidity buffers: Maintain a 6–12 month cash reserve to prevent forced asset sales during downturns.
- Asset-class alignment: Ensure outflows (e.g., living expenses) are covered by low-volatility assets (bonds, cash) while growth assets (equities, private equity) compound.
Q: What’s the most common outflow mistake high-net-worth individuals make?
A: Overestimating their ability to recover losses. The wealthiest often assume that if they’ve weathered downturns before, they can again—but the margins shrink. For example:
- A family might spend aggressively during a bull market, assuming the gains will cover future outflows—only to face a double hit when a recession forces asset sales to meet obligations.
- Investors chase "alpha" (outperformance) while ignoring drag factors like high fees or illiquidity, which turn outflows into compounding losses.
Q: How do outflows differ for self-employed vs. salaried professionals?
A: Salaried professionals face predictable but rigid outflows (taxes, 401(k) contributions, fixed expenses), while self-employed individuals deal with volatile, irregular outflows:
- Salaried: Net worth erosion often comes from lifestyle inflation (e.g., upgrading homes, cars) or tax-induced outflows (e.g., AMT, capital gains). The risk is overconfidence—assuming a steady paycheck will cover all outflows, even in downturns.
- Self-employed: Outflows are tied to cash-flow cycles (client payments, seasonality). A single slow quarter can trigger a liquidity crunch, forcing asset sales or debt accumulation. The risk is underestimating operational costs (e.g., healthcare, equipment) that eat into net worth before revenue arrives.
