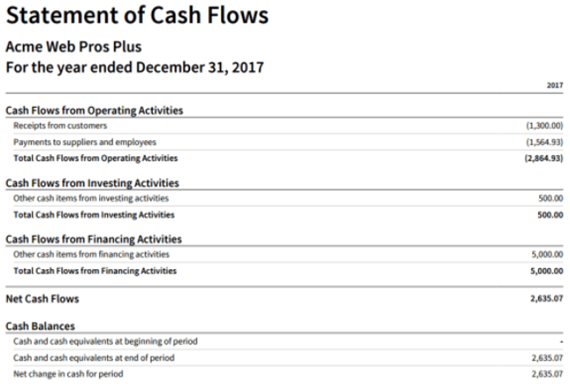
The Complete Overview of Financial Clarity Through Net Worth
At its core, the equation assets – liabilities = net worth is the financial equivalent of a thermometer for economic health. A cash flow statement uses this equation not to assign blame but to diagnose systemic risks—whether it’s a tech startup burning cash faster than it generates revenue or a retiree whose pension depends on an undervalued home. The key insight? Net worth isn’t a destination; it’s a velocity metric. A family with $2 million in assets but $1.8 million in debt may feel secure until a medical emergency forces them to liquidate illiquid assets at a loss. Conversely, a freelancer with $50,000 in cash and no debt can weather downturns while a corporate CFO with $500 million in "assets" (mostly inventory) might face a liquidity crisis overnight. The equation’s power lies in its duality: it’s both a balance sheet snapshot and a cash flow predictor. When a cash flow statement uses this equation dynamically—tracking how assets convert to liquidity and how liabilities accrue interest—it becomes a tool for preemptive finance. Consider Elon Musk’s Tesla: in 2020, its market cap briefly exceeded Ford’s, yet its net worth calculation (assets minus liabilities) revealed a company still grappling with debt servicing and working capital gaps. The market ignored the equation; investors who did not paid the price.Historical Background and Evolution
The concept of net worth traces back to medieval merchant ledgers, where traders recorded boni (assets) and danni (liabilities) to assess solvency before extending credit. By the 19th century, industrialists like Andrew Carnegie used variations of this equation to justify expansions—only to see railroads and steel mills collapse when liabilities outpaced asset liquidity. The modern cash flow statement, formalized in the 20th century, refined this into three components: operating, investing, and financing activities. A cash flow statement uses this equation to separate accounting profit from real cash movements, exposing how depreciation or deferred revenue can mask cash shortages. The 2008 financial crisis exposed a critical flaw: many institutions treated net worth as a static benchmark rather than a dynamic process. Lehman Brothers’ collapse wasn’t due to negative net worth on paper—it was the timing mismatch between illiquid assets (mortgage-backed securities) and short-term liabilities (commercial paper). The equation remained the same, but the speed of asset conversion became the difference between survival and insolvency. Today, fintech platforms like YNAB or Mint automate this equation for individuals, while corporate treasurers use real-time cash flow modeling to stress-test scenarios where assets might not cover liabilities in 30 days.Core Mechanisms: How It Works
The equation assets – liabilities = net worth functions as a financial fulcrum. A cash flow statement uses this equation to classify assets by liquidity tiers—cash (most liquid), accounts receivable (less so), and fixed assets (least)—while liabilities are ranked by urgency: payroll, debt covenants, or tax obligations. The critical variable isn’t the absolute number but the ratio of liquid assets to near-term liabilities. A tech startup with $10 million in venture funding but $8 million in unpaid vendor bills may have a positive net worth on paper, yet a cash flow statement would reveal a liquidity death spiral if burn rate exceeds runway. The equation also exposes hidden liabilities. For example, a homeowner with a $500,000 mortgage may report net worth of $700,000 if their property is valued at $1.2 million—but if the market corrects by 20%, their "assets" drop to $960,000 while liabilities remain unchanged. A cash flow statement uses this equation to stress-test scenarios, asking: What if 30% of receivables default? What if a key supplier demands COD? The answer isn’t in the balance sheet; it’s in the cash flow projection.Key Benefits and Crucial Impact
The equation’s greatest strength is its universality. Whether applied to a single mother’s emergency fund or a sovereign wealth fund’s portfolio, a cash flow statement uses this equation to democratize financial transparency. For individuals, it reveals whether lifestyle inflation is eroding savings; for businesses, it uncovers whether "growth" is funded by debt or organic cash generation. The impact isn’t theoretical: studies show that households tracking net worth monthly are 40% more likely to avoid debt spirals during economic downturns. Yet the equation’s limitations are equally stark. It ignores time value of money—a dollar today isn’t the same as a dollar in five years—and fails to account for non-financial assets like human capital or intellectual property. A cash flow statement uses this equation to quantify risk, but it cannot predict black swan events like pandemics or regulatory overhauls. The solution? Treat the equation as a starting point, not an endpoint. Pair it with scenario modeling, insurance assessments, and behavioral finance checks."Net worth is a photograph; cash flow is the motion picture." — Morgan Housel, The Psychology of Money
Major Advantages
- Risk exposure: Identifies illiquid assets (e.g., real estate) that may not cover short-term liabilities during crises.
- Debt sustainability: Reveals whether liabilities are growing faster than asset appreciation, signaling a leverage trap.
- Investment discipline: Forces a comparison between speculative assets (crypto, meme stocks) and income-generating assets (dividends, rental yields).
- Liquidity planning: Highlights the gap between "book value" and actual spendable cash, critical for retirees or entrepreneurs.
- Behavioral anchor: Acts as a counterbalance to emotional spending by providing a hard metric for financial decisions.

Comparative Analysis
| Individuals | Corporations |
|---|---|
| Net worth tracks personal wealth; cash flow shows ability to cover living expenses. | Net worth assesses solvency; cash flow determines dividend sustainability or expansion capacity. |
| Liabilities include mortgages, student loans, credit cards. | Liabilities include debt covenants, trade payables, deferred revenue. |
| Assets are often illiquid (home equity, retirement accounts). | Assets may include intangibles (patents, goodwill) with no direct cash conversion. |
| Equation used for goal-setting (e.g., "Net worth = $500K in 5 years"). | Equation used for M&A due diligence or credit rating assessments. |
| Tools: Mint, YNAB, spreadsheets. | Tools: QuickBooks, SAP, custom cash flow models. |
Future Trends and Innovations
The next evolution of this equation will lie in predictive analytics. Fintech firms are already embedding machine learning into cash flow statements to forecast how net worth might change under alternative scenarios—e.g., a 10% inflation spike or a 20% drop in a single asset class. For individuals, apps like Personal Capital now simulate how side hustles or early retirement might alter the equation over decades. On the corporate side, ESG (Environmental, Social, Governance) metrics are being folded into net worth calculations, treating sustainability risks as a new class of liability. The biggest disruption may come from decentralized finance (DeFi). Blockchain-based platforms are redefining assets and liabilities in real time—smart contracts auto-liquidate collateral if net worth dips below thresholds, and tokenized real estate allows fractional ownership to be traded instantly. A cash flow statement uses this equation in DeFi not as a quarterly report, but as a continuous, programmable ledger. The challenge? Ensuring the equation adapts to volatility without losing its core purpose: measuring true economic resilience.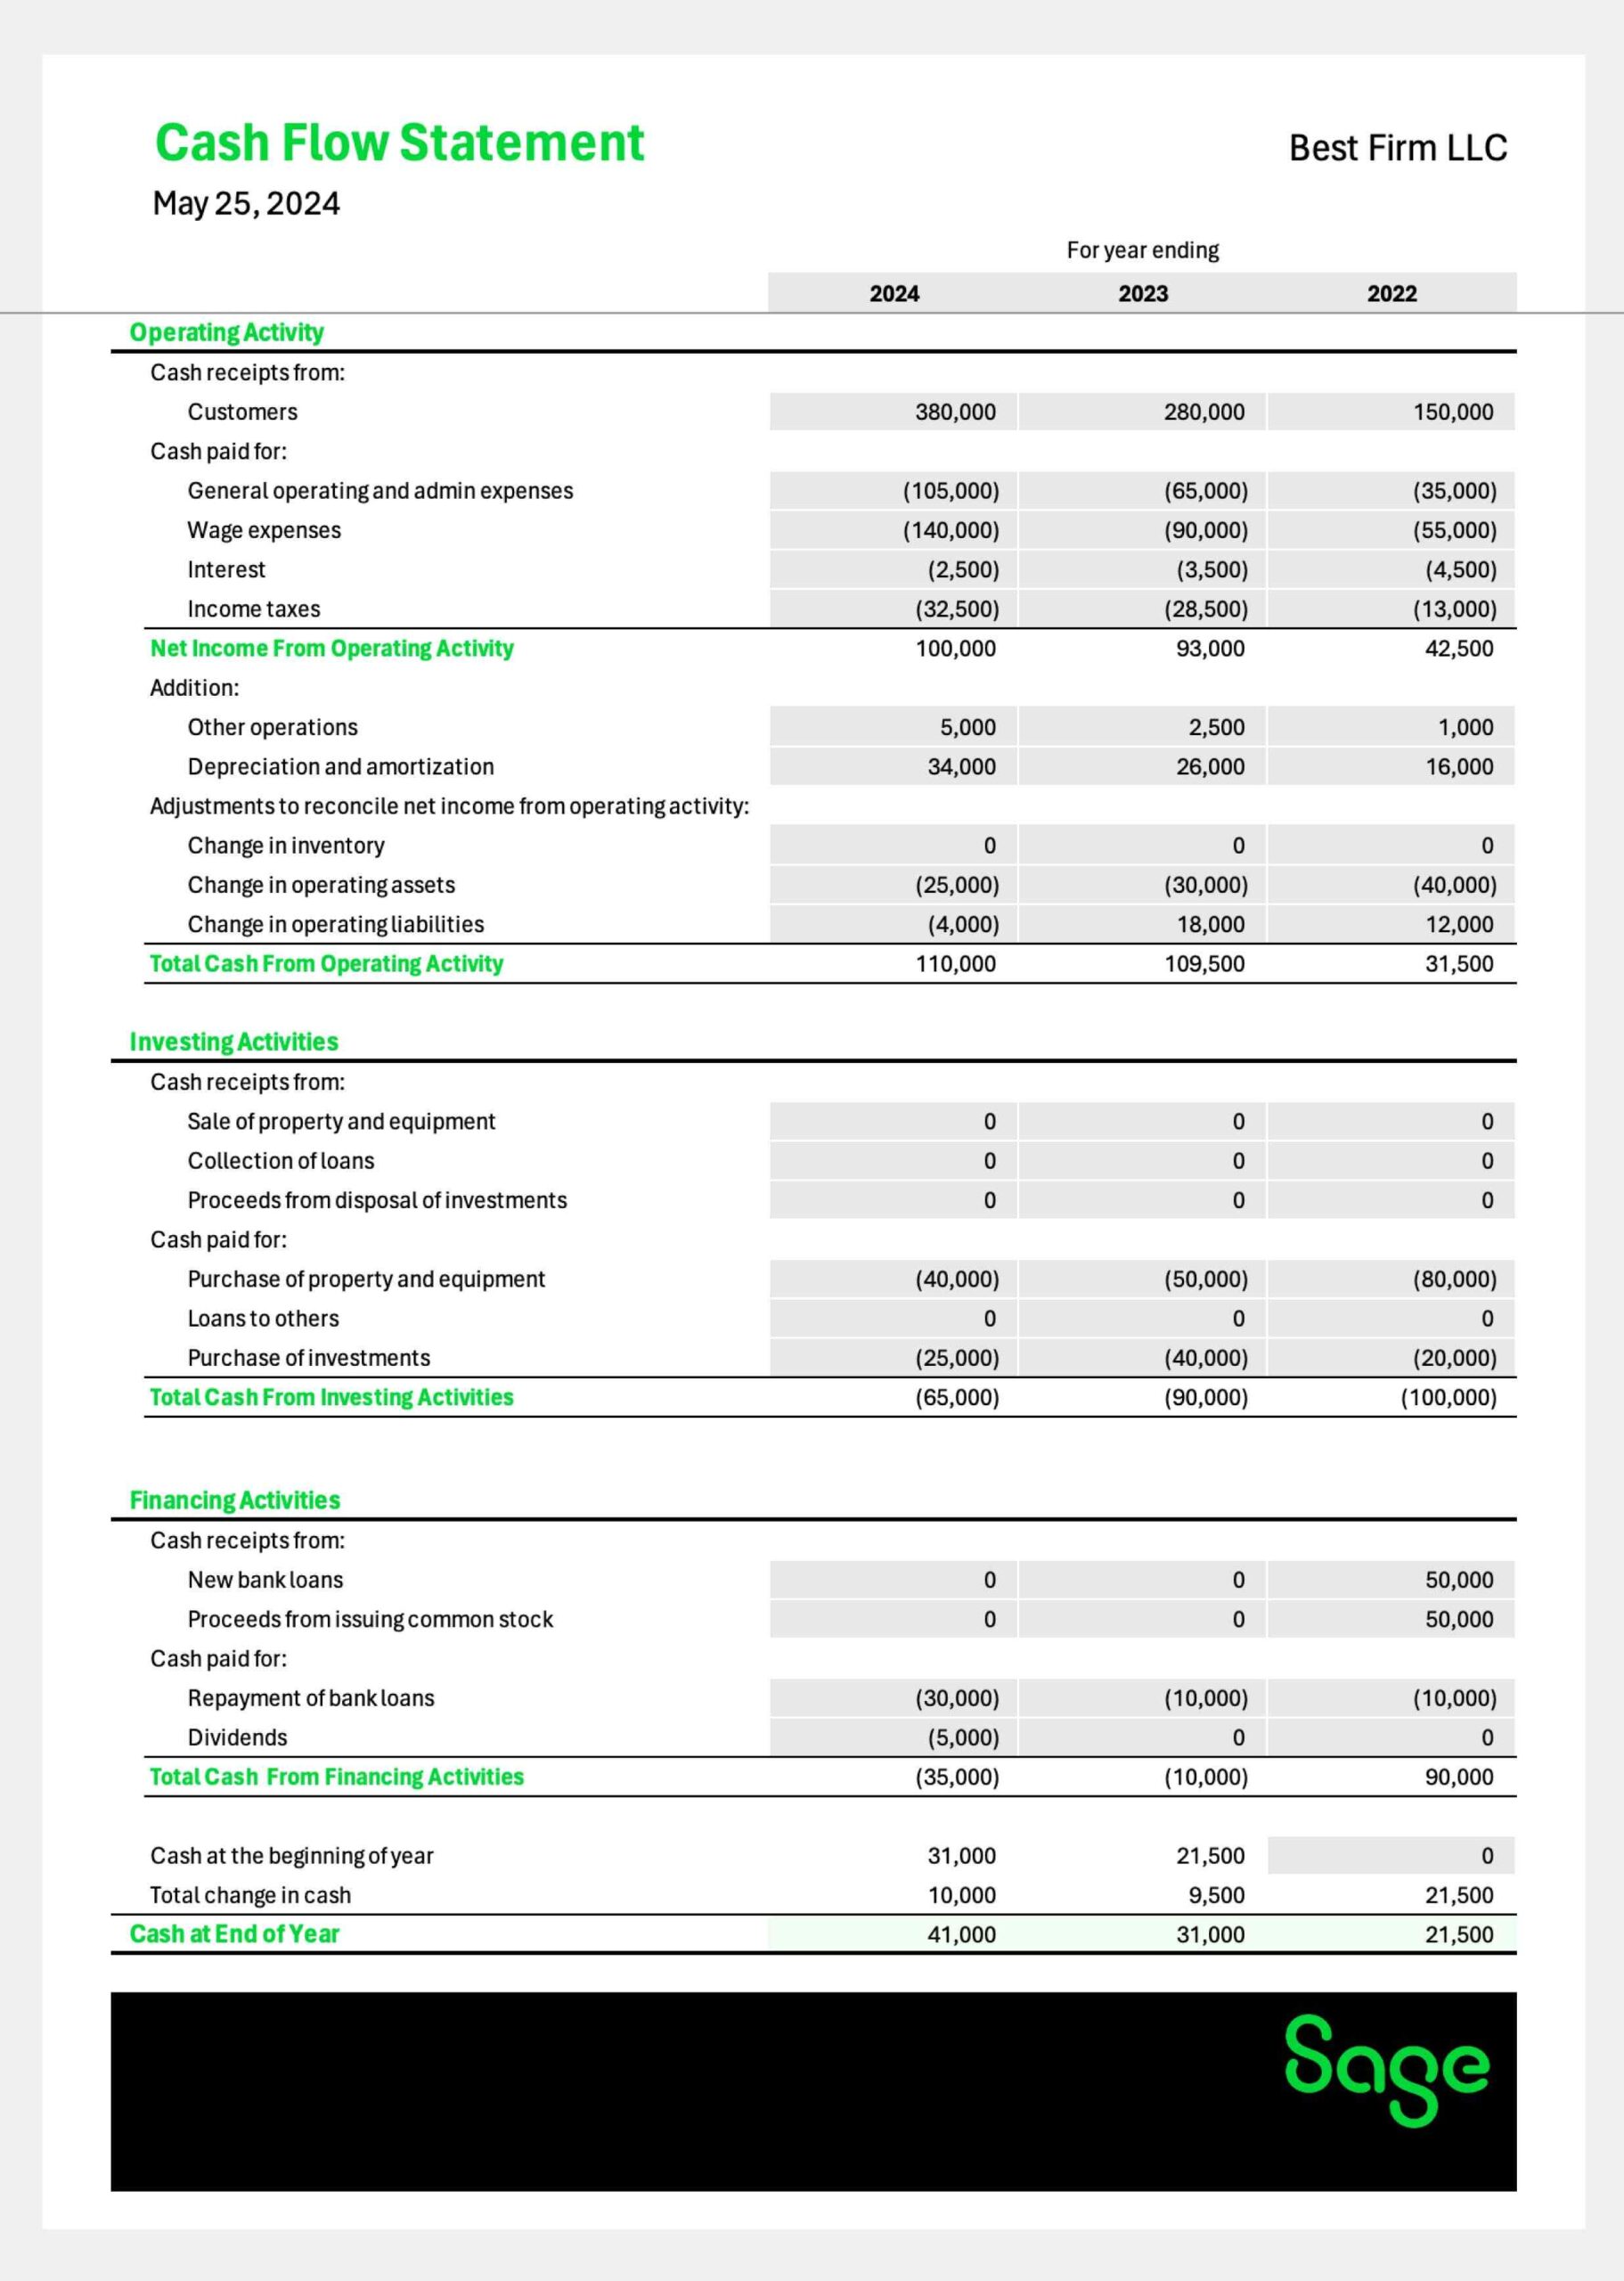
Conclusion
The equation assets – liabilities = net worth is older than modern capitalism, yet its relevance has never been sharper. A cash flow statement uses this equation not to glorify wealth accumulation but to reveal the mechanics of financial survival. The lesson for individuals is simple: net worth isn’t about the number itself, but the story behind it. A corporate CFO’s job isn’t to maximize the equation’s output, but to ensure its components—assets and liabilities—move in harmony. The future belongs to those who treat this equation as a living system, not a static balance. Whether you’re a freelancer tracking invoices or a CEO stress-testing a balance sheet, the question remains the same: Does your cash flow statement reflect reality, or is it a house of cards waiting for the first gust of economic wind?Comprehensive FAQs
Q: Can negative net worth be a good thing?
A: In rare cases, yes—but only if liabilities are strategic (e.g., a startup’s debt-funded growth) and assets are highly liquid or appreciating. For most individuals, negative net worth signals financial strain. The key is whether the equation’s components are aligned with long-term cash flow (e.g., a mortgage on an appreciating home) or a short-term squeeze (credit card debt with no asset backing).
Q: How often should I recalculate my net worth?
A: At minimum, quarterly for active financial management. High-net-worth individuals or business owners may track it monthly to adjust for market volatility, tax liabilities, or large transactions. The goal isn’t perfection but awareness: a sudden drop in net worth often signals a cash flow leak before it becomes a crisis.
Q: Does my cash flow statement need to include non-financial assets (e.g., skills, reputation)?h3>
A: No—by definition, a cash flow statement uses this equation to measure monetizable assets and liabilities. However, you can create a parallel "human capital" ledger to track how skills or relationships might translate into future income. The equation itself remains financial, but smart planners supplement it with qualitative assessments.
Q: What’s the difference between net worth and cash flow?
A: Net worth is a snapshot (assets minus liabilities at a point in time), while cash flow is a movie (how money moves in and out over periods). A cash flow statement uses this equation to bridge the gap: it shows whether your net worth is growing organically (positive cash flow) or eroding (negative cash flow despite high assets). Example: A doctor with $2M in net worth but negative cash flow due to student loans is in a far riskier position than a freelancer with $500K in net worth and steady income.
Q: How do I improve my net worth using this equation?
A: Focus on three levers: 1. Increase liquid assets (cash, low-volatility investments) to cover liabilities. 2. Reduce high-cost liabilities (e.g., refinance debt at lower rates). 3. Convert illiquid assets into cash flow (e.g., sell a non-performing rental property). A cash flow statement uses this equation to prioritize actions: if your liabilities are growing faster than assets, cutting expenses may be more urgent than investing. The equation doesn’t tell you what to do—it tells you where to look.
