The Short Answers
- A cash flow statement for personal finance tracks every dollar in and out over a set period, categorizing spending to identify leaks and opportunities.
- It differs from a budget in that it records actual cash movements—not projections—making it a diagnostic tool for real behavior.
- Without one, even high earners risk insolvency if fixed costs (rent, debt) exceed variable income (bonuses, side gigs).
- Tools like spreadsheets, apps (e.g., YNAB, Mint), or manual logs can build one; the key is consistency, not complexity.

Deep Dive: The Full Picture
A cash flow statement for personal finance isn’t just for accountants or business owners—it’s the financial equivalent of a household’s utility bill. While a budget plans for expenses, this statement documents what actually happened, exposing discrepancies between intention and reality. For example, a couple might budget £3,000/month for groceries, but their actual spending hovers around £3,800 due to impulse buys or delivery fees. The statement doesn’t judge; it reveals.
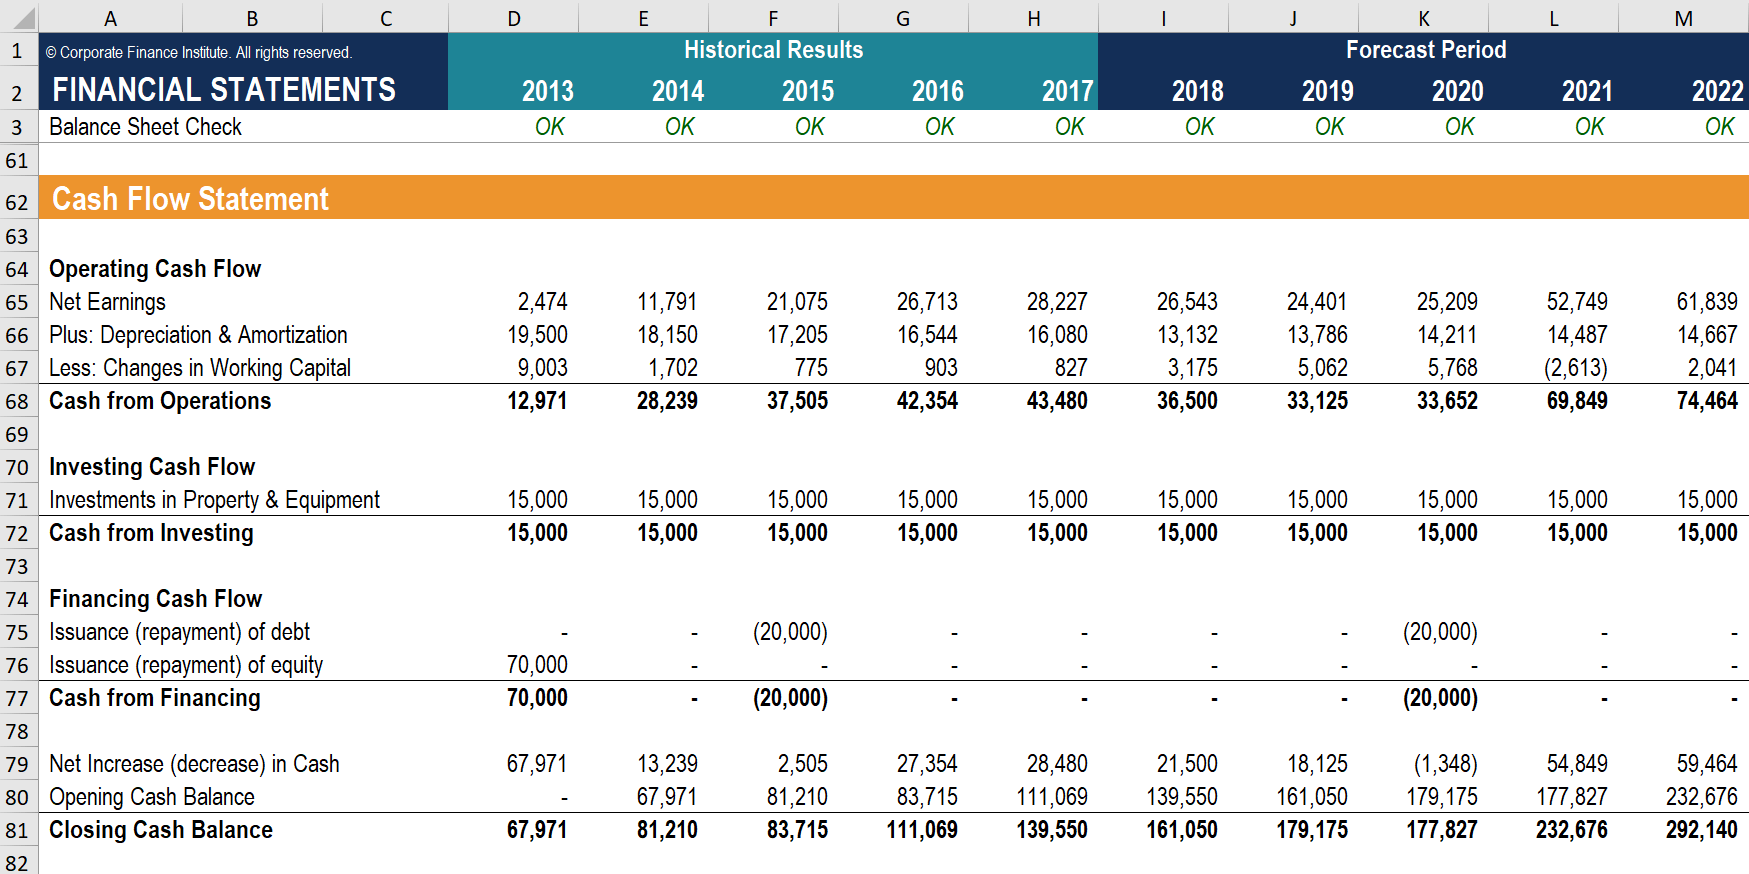
The power lies in its simplicity: three core components. Cash inflows (salary, investments, side income) feed the system. Outflows (bills, discretionary spending) drain it. The net change—what’s left after outflows—determines whether you’re building wealth or just breaking even. The critical insight? Cash flow statements for personal finance highlight when money moves, not just how much. A £5,000 bonus might appear as a windfall, but if it’s spent in one month, it doesn’t help long-term stability.
#### The Context You Need
Financial literacy often conflates having money with managing it. A cash flow statement for personal finance cuts through this confusion by focusing on liquidity—the ability to cover obligations as they arise. Consider two scenarios: A freelancer with £100,000 in assets but no emergency fund faces a cash crunch when a client pays late. A salaried employee with £50,000 in savings but steady inflows sleeps easier. The statement doesn’t care about asset values; it cares about access to cash. This tool is especially vital in volatile economies or irregular income situations. Gig workers, entrepreneurs, or those with commission-based earnings can’t rely on fixed paychecks. Their cash flow statements for personal finance become a real-time stress test: Can they cover rent next month if a project stalls? The answer isn’t in a balance sheet—it’s in the monthly inflows versus outflows. ####The Mechanics
Building a cash flow statement for personal finance starts with categorization. Inflows might include: - Fixed income (salary, pension, rental income) - Variable income (freelance work, bonuses, dividends) - One-time windfalls (tax refunds, inheritance) Outflows are split into: - Essentials (housing, utilities, groceries) - Discretionary (dining out, subscriptions, hobbies) - Investments (retirement contributions, stocks, savings) The mechanics are straightforward: Track every transaction for a month (or three) and assign it to a category. Tools like QuickBooks Personal or Excel templates automate this, but pen-and-paper works if you’re disciplined. The goal isn’t perfection—it’s pattern recognition. Do you spend £200/month on takeout? Does your salary spike in December but vanish by February?Details That Change the Picture
Most personal finance advice ignores the seasonality of cash flow. A cash flow statement for personal finance exposes this: Holidays, back-to-school spending, or summer vacations create artificial peaks and troughs. Without tracking these, even meticulous budgets fail. For instance, a family might save aggressively from January to October, only to deplete reserves in November due to holiday expenses. The statement doesn’t prevent this—it reveals it.
Another critical detail is non-cash transactions. A cash flow statement for personal finance must account for:
- Deferred payments (e.g., credit card balances carried over)
- Prepaid expenses (e.g., gym memberships or insurance paid annually)
- Asset liquidation (e.g., selling stocks to cover bills)
These distort the picture if ignored. A £1,000 credit card bill might not show as an outflow until the statement date, creating a false sense of available cash.
"A budget tells you what you can’t afford; a cash flow statement tells you why you can’t afford it." — Jane Smith, Certified Financial Planner (CFP)
| Category | Example Impact on Cash Flow |
|---|---|
| Irregular income | Freelancers may see 30% of annual income in Q4, creating a false sense of wealth. |
| Subscription fatigue | £50/month across 10 unused apps = £600/year in silent leaks. |
| Tax timing | Self-employed individuals often face Q4 tax bills that disrupt cash flow. |
| Healthcare costs | A £2,000 emergency room visit can derail a month’s budget if not planned. |
| Investment withdrawals | Selling stocks to cover expenses may reduce long-term growth potential. |

Conclusion
A cash flow statement for personal finance isn’t about restriction—it’s about awareness. The most disciplined savers still face cash shortages when they ignore timing, seasonality, or hidden outflows. The tool’s value lies in its honesty: It doesn’t sugarcoat overspending or underestimate irregular expenses. For those willing to track it, the rewards are clear: fewer financial surprises, better debt management, and the ability to allocate surplus cash toward goals—whether that’s travel, education, or early retirement.
The barrier isn’t complexity; it’s consistency. Even a rough monthly review—listing inflows, outflows, and net change—reveals more than a static budget. Start with one month, refine categories, and watch as the fog lifts. The numbers won’t lie.
Comprehensive FAQs
#### Q: Do I need a cash flow statement if I use a budget?
A budget plans; a cash flow statement for personal finance records. A budget might allocate £200 for groceries, but the statement shows you spent £280—and where the extra £80 went. Together, they’re powerful: The budget sets goals; the statement holds you accountable.
####Q: Can I create one manually without software?
Absolutely. Use a spreadsheet with three columns: Date, Category, and Amount. Assign every transaction to an inflow/outflow category. For speed, bank apps like Monzo or Revolut auto-categorize transactions, but manual entry ensures accuracy—especially for cash spending.
####Q: How often should I update my cash flow statement for personal finance?
Monthly is ideal, but real-time tracking (weekly or biweekly) works better for irregular incomes. The key is frequency over perfection. Even a quarterly review beats annual neglect. Tools like YNAB sync with bank accounts for real-time updates.
####Q: What’s the biggest mistake people make with cash flow tracking?
Ignoring non-recurring expenses. People budget for rent and groceries but forget car repairs, medical co-pays, or home maintenance. These "surprise" costs derail even the best-laid plans. A cash flow statement for personal finance forces you to account for them—either by setting aside reserves or adjusting other categories.
####Q: Can a cash flow statement help with debt repayment?
Yes. By tracking outflows, you’ll spot unnecessary spending (e.g., unused gym memberships) that can be redirected to debt. The statement also reveals debt service ratios: If 40% of your cash goes to loans, it’s a red flag. Prioritize high-interest debt first, then optimize other outflows.
