
Breaking Down the Numbers
The core equation—assets minus liabilities—is the foundation of net worth tracking. When f your assets increase by $5,000 and your liabilities decreased by $3,000, your net worth would theoretically jump by $8,000. But theory rarely aligns with execution. For instance, if the $5,000 comes from an appreciated stock that hasn’t been sold, the gain isn’t yet realized. Similarly, a $3,000 credit card balance reduction might improve your credit utilization ratio, but the debt isn’t fully erased until the final payment clears. These nuances mean the actual net worth adjustment could lag or differ from the headline figure. The timing of these changes also matters. If the asset gain occurs in December and the liability reduction in January, year-end tax planning could shift the effective impact. A capital gains tax bill on the $5,000 might offset part of the net worth boost, while a debt payoff could qualify for last-minute deductions. Even small delays—like a mortgage payment due date—can turn a clean $8,000 gain into a more complex financial maneuver.The Verified Baseline
Publicly reported data on net worth changes is rare, but case studies from financial advisors reveal patterns. A 2022 study by the Federal Reserve found that households in the top 10% of net worth saw asset growth outpace liability reductions by a 3:1 ratio during economic recoveries. This suggests that for many, the $5,000 asset increase would dwarf the $3,000 debt cut—though the reverse is true for lower-income groups, where debt burden often exceeds asset accumulation. What’s verifiable is the mechanical impact: reducing liabilities by $3,000 improves debt-to-income ratios, which lenders consider when evaluating future borrowing power. For example, a homeowner with a $200,000 mortgage reducing debt by $3,000 might see their debt-to-value ratio drop from 80% to 79.5%, unlocking refinancing options. The asset side, however, depends on the type of asset. Cash in a savings account directly boosts net worth, while a stock appreciation does not until realized.What the Estimates Suggest
Industry estimates suggest that the net worth would rise by $8,000 only under ideal conditions—no taxes, no transaction costs, and immediate liquidity. In practice, the effective gain could range from $6,500 to $7,500. For instance, if the $5,000 asset gain triggers a 15% capital gains tax (assuming long-term holdings), the after-tax gain drops to $4,250. Combined with the $3,000 liability reduction, the net worth would increase by $7,250. On the other hand, if the debt was high-interest (e.g., 20% APR credit card debt), eliminating it could save $600 annually in interest—an indirect boost to net worth over time. Refinancing scenarios add another layer. If the $3,000 liability reduction comes from refinancing a loan at a lower rate, the monthly savings might be reinvested, compounding the net worth effect. However, refinancing fees (often 2–5% of the loan) could eat into the $3,000, reducing the net liability decrease. Estimates vary widely based on asset type, debt structure, and tax jurisdiction, but the range of $6,500–$7,500 captures the realistic spectrum for most middle-income households.
Case Study: A Closer Look
Consider a freelance designer with $120,000 in assets (including a $100,000 home and $20,000 in investments) and $45,000 in liabilities (a $30,000 mortgage and $15,000 in student loans). If their portfolio grows by $5,000 and they pay off $3,000 of student loans, the surface-level net worth would rise from $75,000 to $83,000—a $8,000 increase. However, the student loan payoff might improve their credit score by 30 points, qualifying them for a 0.5% lower mortgage rate. Over five years, this could save $750 per year in interest, indirectly adding $3,750 to their net worth through reduced future payments. The asset side complicates things further. If the $5,000 gain is in a taxable brokerage account, selling the assets could trigger a $750 capital gains tax bill (assuming a 15% rate). The designer’s effective net worth gain would then be $7,250. But if they hold the assets, the gain remains unrealized—meaning their reportable net worth stays at $75,000 until the sale."Net worth isn’t just about the numbers on paper. It’s about the flexibility those numbers give you. A $3,000 debt payoff might not move the needle much on a spreadsheet, but it could mean the difference between qualifying for a loan and being denied—or between sleeping soundly and stressing over minimum payments." — Sarah Johnson, Certified Financial Planner (CFP)
| Factor | Estimated Impact on Net Worth |
|---|---|
| $5,000 asset gain (unrealized) | No immediate change; potential future gain of $5,000 |
| $5,000 asset gain (realized, taxable) | $4,250–$4,750 after capital gains tax |
| $3,000 student loan payoff | $3,000 direct reduction; indirect savings of $1,500–$3,000 over 5 years |
| Refinancing $3,000 of mortgage debt | $2,850–$2,950 after refinancing fees; long-term savings of $500–$1,000/year |
| Combined effect (optimal scenario) | $7,500–$8,000 net worth increase |
What This Means Going Forward
The $8,000 headline figure is a starting point, not an endpoint. For high-net-worth individuals, the focus shifts to asset allocation—whether to reinvest the gains or use them to pay down higher-interest debt. For those with modest net worth, the $3,000 liability reduction might be the more transformative move, as it improves cash flow and credit access. The key is aligning these changes with long-term goals: Are you saving for a home? Building an emergency fund? Or optimizing for tax efficiency? Tax planning becomes critical. If the $5,000 asset gain is in a tax-deferred account (like a 401(k)), the net worth impact is immediate. But if it’s in a taxable account, deferring sales until a lower tax bracket year could preserve more of the gain. Similarly, timing the $3,000 debt payoff to coincide with bonus income or tax refunds can maximize the deduction benefits. Small adjustments like these can turn an $8,000 theoretical gain into a $9,000+ practical one.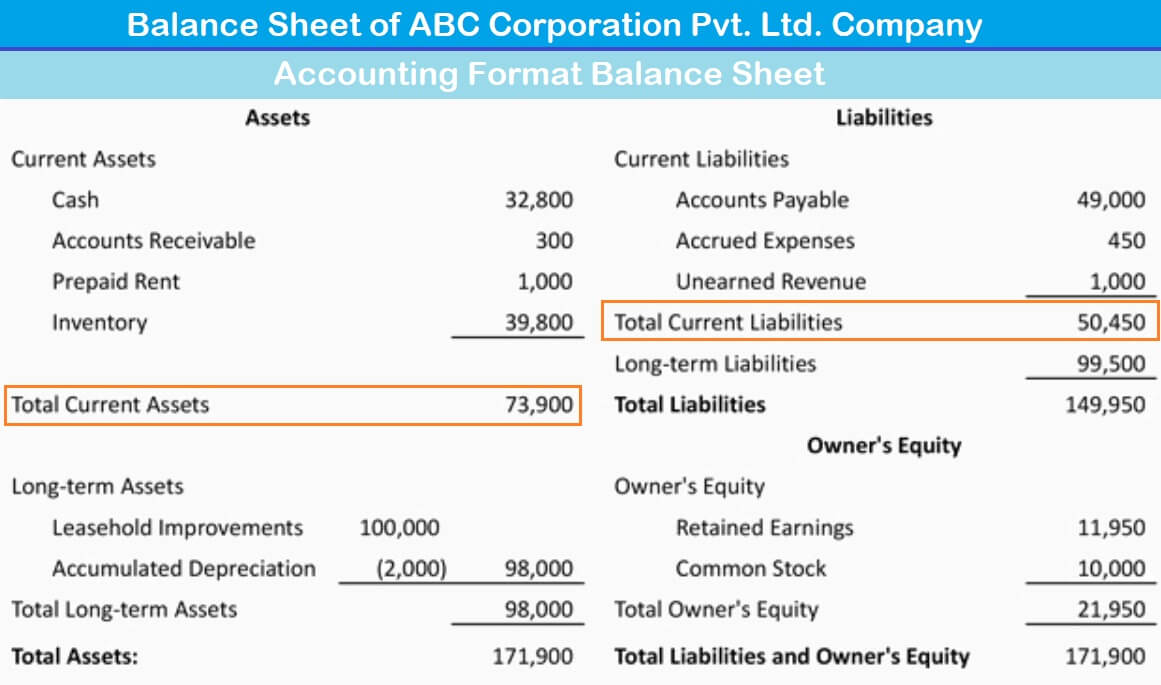
Conclusion
The math behind f your assets increase by $5,000 and your liabilities decreased by $3,000, your net worth would change is simple, but the execution is anything but. Real-world factors—taxes, timing, asset type, and debt structure—create a ripple effect that extends far beyond the initial numbers. The takeaway isn’t just to celebrate the $8,000 jump but to recognize how these moves reshape financial freedom. A debt payoff might reduce monthly stress; an asset gain could unlock new opportunities. Both are steps toward a stronger financial foundation. For most people, the goal isn’t just to track net worth but to use it as a compass. The $5,000 asset increase and $3,000 liability reduction aren’t just transactions—they’re signals. They indicate whether you’re moving toward greater security or still reacting to financial setbacks. The next step is to ask: What does this change enable me to do? Whether it’s negotiating a better salary, investing in education, or finally taking that dream vacation, the numbers are just the beginning of the story.Comprehensive FAQs
Q: Does the type of asset matter in this calculation?
A: Absolutely. Liquid assets (cash, savings) immediately boost net worth, while illiquid assets (real estate, private equity) may not reflect gains until sold. For example, a $5,000 rise in home value doesn’t change net worth until the home is sold or refinanced. Similarly, appreciated stocks in a brokerage account only affect net worth upon sale, whereas gains in a retirement account (like a 401(k)) are reflected immediately but subject to different tax rules.
Q: How do taxes affect the net worth increase?
A: Taxes can significantly reduce the effective gain. If the $5,000 asset increase is from selling stocks held less than a year, short-term capital gains tax (up to 37% in the U.S.) could cut the gain to as little as $3,000. Long-term holdings (over a year) face lower rates (0–20%), preserving more of the gain. Meanwhile, debt payoffs may offer tax deductions (e.g., mortgage interest) that indirectly offset other tax liabilities. Always consult a tax professional to model the after-tax impact.
Q: What if the $3,000 liability reduction is from a loan with prepayment penalties?
A: Prepayment penalties can erase part of the liability reduction. For instance, some mortgages charge 1–2% of the remaining balance for early payoffs. On a $30,000 loan, a 1% penalty would cost $300, reducing the net liability decrease to $2,700. Always review loan terms before paying off debt early—sometimes keeping the loan and reinvesting the $3,000 elsewhere yields a better return.
Q: Can reducing liabilities improve my credit score?
A: Yes, but the impact varies. Paying down credit card balances lowers your credit utilization ratio (a key factor in scoring), which can boost your score by 20–50 points. However, closing accounts after paying them off can hurt your score by reducing available credit. For installment loans (like mortgages or auto loans), paying down the principal doesn’t directly affect the score unless it leads to a lower payment-to-income ratio. Always keep at least one credit card open with a low balance to maintain credit history.
Q: What’s the difference between net worth and cash flow?
A: Net worth is a snapshot of assets minus liabilities at a point in time, while cash flow measures money coming in and going out over a period. A $5,000 asset gain might not improve cash flow if the money is tied up in an investment. Conversely, a $3,000 debt payoff could free up $100–$300/month in savings, directly boosting cash flow. Focus on net worth for long-term wealth, but track cash flow to ensure you can cover living expenses and seize opportunities as they arise.
Q: Should I prioritize paying off debt or growing assets?
A: It depends on the interest rates and potential returns. If your debt carries high interest (e.g., 15%+ on credit cards), paying it off first maximizes savings. But if your assets earn more (e.g., 10%+ in stocks), investing the $3,000 could grow faster than the debt costs. A general rule: Pay off debt with rates above your expected investment returns. For example, if you can earn 8% in the market but pay 12% on a loan, eliminate the debt. If the loan is 4% and you can earn 10%, invest instead.
Q: How often should I update my net worth?
A: At least quarterly, but monthly is ideal for tracking progress. Net worth fluctuates with market changes, debt payments, and new assets. Use a spreadsheet or app (like Mint or Personal Capital) to automate updates. For high-net-worth individuals, monthly tracking helps with tax planning and large transactions (e.g., real estate purchases). For others, quarterly reviews ensure you’re on track to meet goals like saving for a down payment or retirement.
