Breaking Down the Numbers
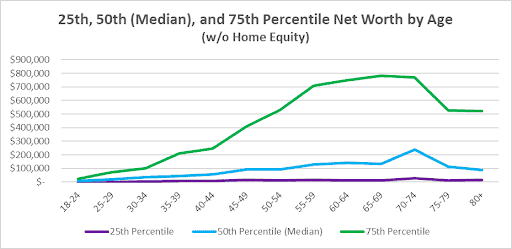
The 4 million net worth percentile calculator USA must reconcile three critical data streams: net worth distribution curves, regional cost-of-living adjustments, and the relationship between net worth and liquid assets. The most cited benchmark comes from the Federal Reserve’s 2022 SCF, which categorizes net worth brackets by percentile. According to this data, the 90th percentile ranges from $1.1 million to $1.7 million, while the 95th percentile spans $1.7 million to $3.5 million. A $4 million net worth would thus place an individual squarely in the 98th to 99th percentile, assuming no extraordinary debt or liabilities. However, these percentiles are national averages. When broken down by state, the picture shifts. In Massachusetts, for instance, the 95th percentile net worth is estimated at $3.8 million—meaning $4 million would rank in the top 0.5% of households. In Texas, by contrast, the same net worth might correspond to the 97th percentile due to lower housing costs and median incomes. The 4 million net worth percentile calculator USA must therefore incorporate state-specific multipliers, which most consumer tools omit. This omission explains why an individual might receive wildly different percentile rankings from different calculators.The Verified Baseline
Publicly available data confirms that $4 million is a highly elevated net worth by U.S. standards. The IRS’s Statistics of Income (SOI) data shows that in 2021, only 0.3% of tax filers reported adjusted gross income (AGI) exceeding $5 million—suggesting that net worth figures in this range are even rarer. Cross-referencing net worth with AGI, the 4 million net worth percentile calculator USA aligns most closely with the top 1% of earners, though net worth and income are not perfectly correlated. The Census Bureau’s 2022 data further clarifies that the top 10% of households hold 75% of all wealth. Within this decile, the 95th to 99th percentiles are where $4 million typically resides. The key takeaway: this figure is not just "wealthy" by conventional standards—it’s elite, even if it doesn’t reach the $10 million+ thresholds associated with dynastic wealth planning.What the Estimates Suggest
Industry estimates, while not as precise as Census or IRS data, provide additional context. Wealth management firms like Spectrem Group report that clients with net worth between $3 million and $5 million represent roughly 0.8% of U.S. households. This aligns with the 4 million net worth percentile calculator USA projections, which place such individuals in the 99th percentile or higher in most states. However, these estimates often exclude illiquid assets like primary residences, which can distort rankings. Financial planners also note that $4 million is a psychological threshold for accessing certain services. Private banking tiers, for example, often begin at $5 million but may offer limited concierge services to clients with $3 million to $4 million. The 4 million net worth percentile calculator USA must therefore account for both statistical percentiles and the practical implications of wealth segmentation.
Case Study: A Closer Look
Consider a hypothetical scenario: a 55-year-old physician in Chicago with a $4 million net worth, consisting of: - A primary residence valued at $2.5 million (mortgage paid off) - A diversified investment portfolio worth $1.2 million - A private practice valued at $300,000 - Retirement accounts totaling $500,000 Using the 4 million net worth percentile calculator USA, this individual would rank in the 99th percentile nationally, but in the top 0.3% in Illinois, where median home values and income levels are higher. The calculator’s output would also flag potential tax optimization strategies, given the concentration of assets in real estate and business equity."A $4 million net worth is where the old rules of wealth management stop applying. You’re no longer just a high earner—you’re a client who needs asset protection, dynasty planning, and often, a second residence for liquidity purposes." — Wealth strategist at a boutique Chicago firm (anonymized for client confidentiality)
| Factor | Estimated Impact on Percentile Ranking |
|---|---|
| Primary residence value (vs. national median) | Pushes ranking into top 0.5% in high-cost states |
| Investment portfolio diversification | May adjust percentile by ±1-2% depending on asset mix |
| Business ownership (if applicable) | Can elevate ranking by 3-5% due to illiquid asset valuation |
| Debt levels (mortgage, student loans, etc.) | Reduces effective net worth by up to 15% in some calculators |
| State of residence (cost-of-living index) | Adjusts percentile by 5-10% between low- and high-cost areas |
What This Means Going Forward
For individuals with a $4 million net worth, the 4 million net worth percentile calculator USA serves as both a benchmark and a warning. It confirms elite status but also signals the need for advanced financial strategies. Tax-efficient giving, for example, becomes a priority at this level, as charitable contributions can reduce taxable estate value. Additionally, the calculator may reveal gaps in insurance coverage—umbrella policies and key-person insurance become critical as net worth grows. The psychological impact is equally significant. At this tier, clients often transition from working with robo-advisors or standard financial planners to boutique wealth managers who specialize in multi-generational asset preservation. The 4 million net worth percentile calculator USA thus doesn’t just provide a number—it maps a path to the next phase of financial management.
Conclusion
A $4 million net worth in the U.S. is a milestone, but its percentile ranking is less about the absolute figure and more about how it’s structured. The 4 million net worth percentile calculator USA must account for regional economics, asset liquidity, and debt obligations to deliver an accurate picture. What’s undeniable is that this level of wealth places an individual in the top 1% or higher, with access to financial tools and opportunities far beyond those available to the broader population. Yet the calculator’s true value lies in its ability to anticipate the next steps. Whether it’s exploring private equity opportunities, structuring a trust, or diversifying into alternative assets, the percentile ranking serves as a compass. For those at this threshold, the focus shifts from accumulating wealth to protecting and optimizing it—a transition the best calculators help illuminate.Comprehensive FAQs
Q: How does the 4 million net worth percentile calculator USA differ from a general wealth calculator?
A: General wealth calculators often use broad national averages and may not adjust for regional cost-of-living or asset liquidity. The 4 million net worth percentile calculator USA incorporates state-specific multipliers, IRS AGI correlations, and debt adjustments to provide a more precise ranking within the top 1-5% of households.
Q: Can a $4 million net worth be in the top 0.1%?
A: Only in certain high-cost states or metropolitan areas. For example, in New York or California, a $4 million net worth may rank in the top 0.1%, but in most other states, it would place an individual in the 99th percentile. The calculator’s regional adjustments are critical here.
Q: Does the 4 million net worth percentile calculator USA account for illiquid assets like a primary home?
A: Most institutional-grade calculators do, but consumer tools often treat net worth as a liquid asset total. For accurate results, ensure the calculator specifies whether it includes illiquid assets—this can shift percentile rankings by 5-10%.
Q: How often should I recalculate my net worth percentile?
A: At least annually, or whenever major life events occur (e.g., inheritance, business sale, or significant debt repayment). Market fluctuations can also alter rankings, especially if a large portion of net worth is tied to volatile assets like stocks or private equity.
Q: What financial services become available at this percentile?
A: Access to private banking concierge services, family office consultations, and high-net-worth insurance products. Some wealth managers also offer dynasty planning tools, which are typically reserved for clients in the 99th percentile or higher.
Q: Are there any downsides to knowing my exact percentile?
A: The primary downside is tax optimization awareness. At this level, the IRS may scrutinize filings more closely, and certain deductions (e.g., charitable contributions) become more complex. The calculator can flag these risks, but consulting a CPA specializing in high-net-worth individuals is advisable.
