Breaking Down the Numbers
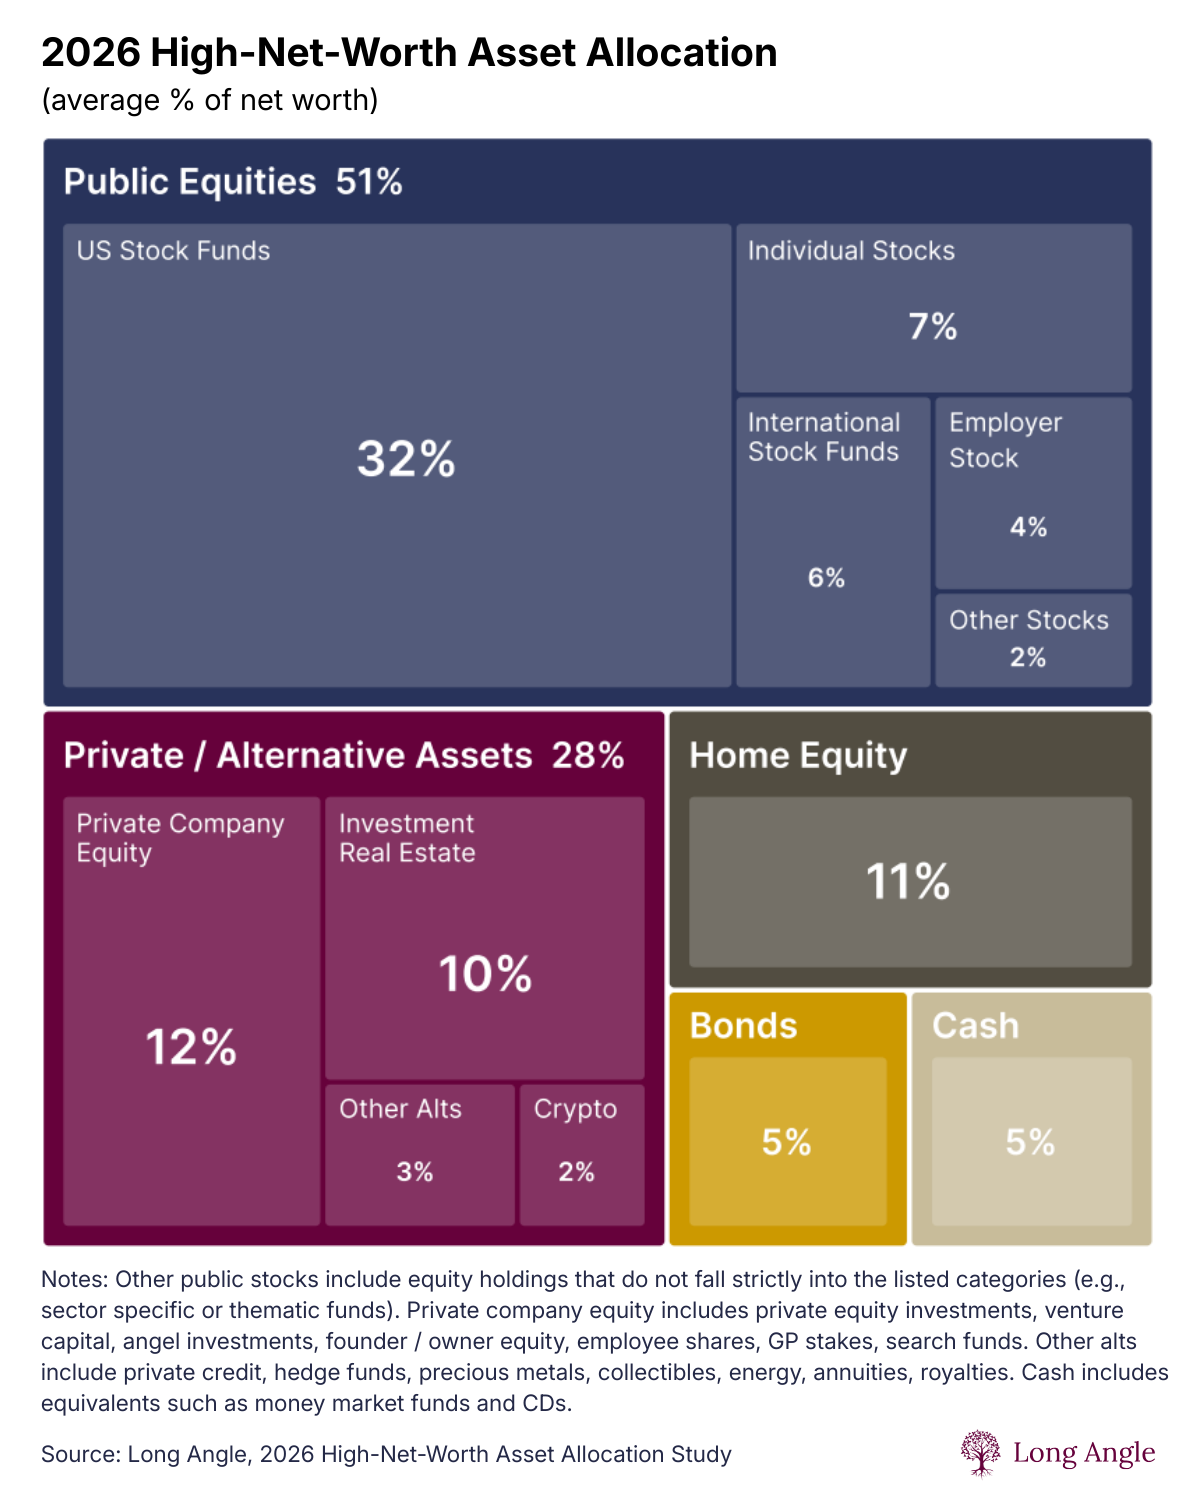
The 2019 high-net-worth-individuals-asset-allocation landscape was defined by two opposing forces: a liquidity crunch in public markets and an abundance of dry powder among HNWIs. The latter stemmed from years of low interest rates and strong economic growth, which had swollen net worth figures. By mid-2019, global HNWI assets were estimated at $84.2 trillion, per Credit Suisse’s Global Wealth Report, with the top 1% controlling nearly half of that total. The challenge became where to deploy capital without overconcentration risk. Private equity remained the darling of HNWI allocations, but the game changed in 2019. Secondary buyout funds—which allow investors to enter midway through a fund’s lifecycle—surged in popularity, accounting for ~15% of total private equity commitments that year. This shift reflected a desire for immediate diversification without the 10-year lockup periods of traditional funds. Meanwhile, venture capital saw record dry powder, with HNWIs and family offices deploying capital into late-stage startups (Series C and beyond) rather than early-stage bets. The rationale was simple: exit multiples were higher, and liquidity events via IPOs or acquisitions were more predictable.The Verified Baseline
Publicly available data confirms that 2019 high-net-worth-individuals-asset-allocation leaned heavily on illiquid assets, but the numbers vary by region. In the U.S., the Securities Industry and Financial Markets Association (SIFMA) reported that HNWIs held ~30% of their portfolios in alternatives by year-end, up from 25% in 2018. This included private credit (10%), real estate (8%), and hedge funds (5%). European HNWIs, constrained by stricter regulations, allocated slightly less—~22%—but with a heavier tilt toward art and collectibles, which grew from 4% to 6% of portfolios. The UBS/PwC Billionaire Census 2019 provided further clarity: 42% of billionaires reported increasing their exposure to private markets in 2019, while 38% boosted allocations to real assets. Notably, family offices—which manage $10 trillion+ in assets—were the primary drivers. Their average allocation to private equity rose to 28%, with infrastructure and renewable energy becoming top picks. The data also showed a decline in public equities, dropping from 45% to 38% of portfolios, as HNWIs sought to reduce market exposure.What the Estimates Suggest
Industry estimates paint a more speculative but equally revealing picture. Campbell Lutyens’ Private Equity Survey 2019 suggested that HNWI commitments to private equity could have reached $200 billion by year-end, driven by secondary fund sales and direct co-investments. While exact figures are elusive, hedge fund managers privately cited $50–70 billion in HNWI capital flowing into distressed debt and special situations funds—a strategy that gained traction as trade tensions escalated. For real assets, estimates are even harder to pin down, but JLL’s Wealth Report 2019 indicated that commercial real estate allocations grew by 12% among HNWIs, with logistics and data center properties leading the charge. Timberland and farmland also saw increased interest, with Blackstone and Nuveen reporting record demand from family offices. The catch? Many of these allocations were off-balance-sheet, meaning they didn’t appear in traditional wealth reports. This opacity makes it difficult to quantify the full extent of 2019 high-net-worth-individuals-asset-allocation shifts, but the trend toward non-traditional assets is undeniable.
Case Study: A Closer Look
The 2019 asset strategy of a single European family office—let’s call it House of V.—offers a microcosm of the broader HNWI trends. With a net worth estimated at €8–10 billion, the family had historically followed a 60/30/10 split between public equities, bonds, and alternatives. By 2019, however, the allocation had evolved into 40/20/40, with the alternatives bucket now dominated by private equity (25%), real estate (10%), and fine art (5%). The pivot was driven by three key factors: 1. Tax optimization in Switzerland, where capital gains on art are taxed at lower rates than equities. 2. Geopolitical risk, particularly around Brexit and U.S.-China trade wars, which made liquidity a priority. 3. Access to exclusive deals, including a €1.2 billion stake in a German industrial REIT and a €300 million commitment to a secondary private equity fund. The family office’s CIO explained in a 2020 interview with Institutional Investor:"In 2019, we treated cash like a tactical asset. If markets corrected, we wanted dry powder to deploy. Private credit gave us that flexibility—yield without the volatility of public bonds."A breakdown of the estimated impact of these shifts:
| Factor | Estimated Impact |
|---|---|
| Private Equity Allocation (25%) | ~8–10% annualized returns, with lower correlation to public markets. Secondary funds provided liquidity options. |
| Real Estate (10%) | ~6–8% net yield, but with illiquidity premium—exit strategies took 3–5 years. |
| Fine Art (5%) | Tax efficiency (lower capital gains), but valuation risk—some pieces lost value post-2019 market shifts. |
What This Means Going Forward
The 2019 high-net-worth-individuals-asset-allocation patterns set the stage for the 2020s wealth management paradigm. The most enduring lesson is that liquidity and resilience now rank above traditional return metrics. HNWIs who over-indexed in public equities in 2019 faced significant drawdowns by early 2020, while those with diversified alternative exposures weathered the storm better. This has led to a permanent rebalancing toward private markets and real assets, even as public markets recover. The rise of digital assets—while not dominant in 2019—also casts a long shadow. By late 2019, bitcoin allocations among HNWIs were still minimal (<1%), but the infrastructure around crypto custody and trading (e.g., Coinbase Prime, Bakkt) had matured enough to attract early adopters. The 2019 allocation trends suggest that 2020–2021 would see a trickle of capital flow into crypto-related ventures, particularly blockchain-based private equity and tokenized real estate. The shift is incremental but indicative of a broader tech-driven wealth strategy.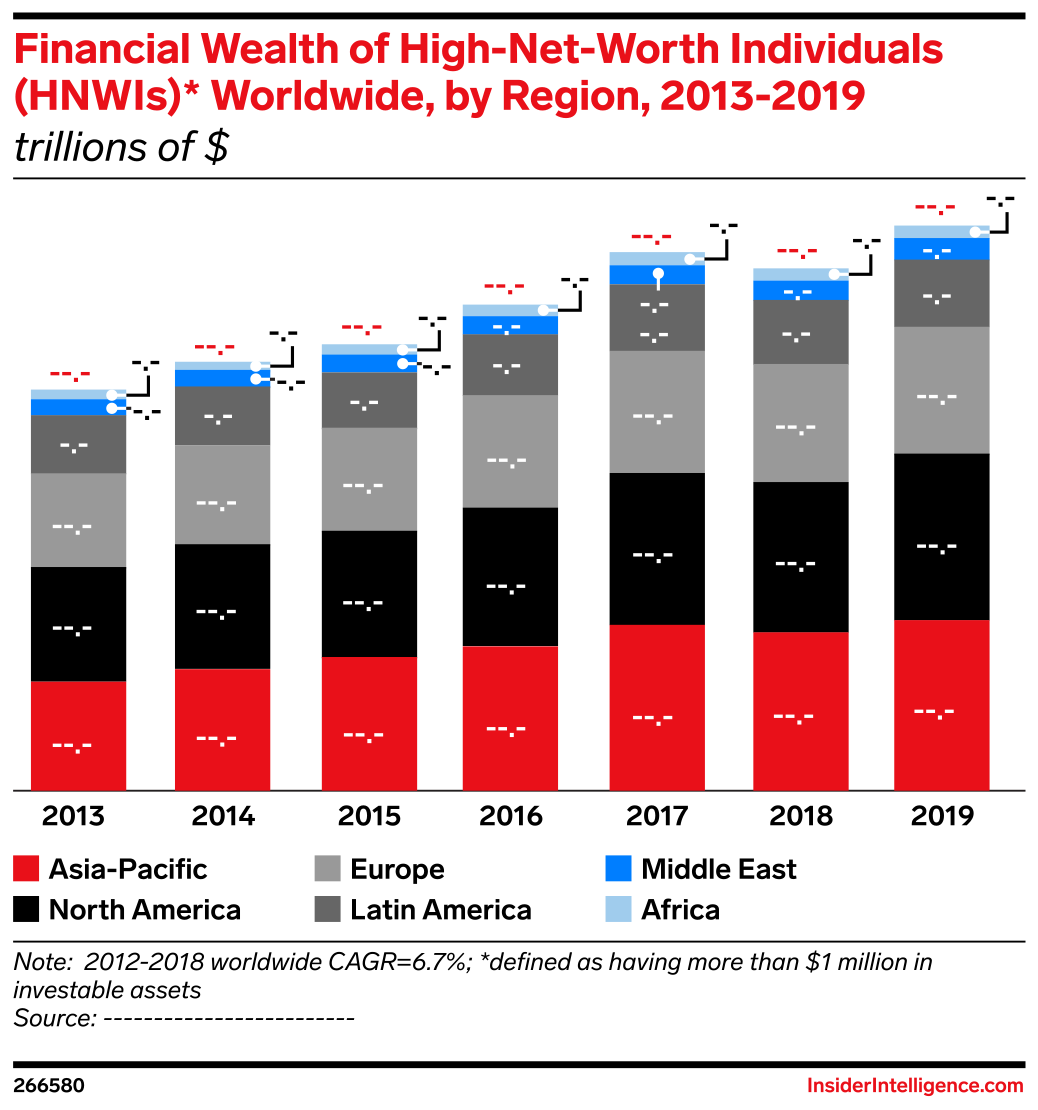
Conclusion
The 2019 high-net-worth-individuals-asset-allocation story is one of adaptation under uncertainty. What began as a response to tax policy, trade wars, and central bank experiments evolved into a structural shift—one where illiquidity is no longer a bug but a feature. The data shows that HNWIs are no longer passive investors; they are active allocators, using family offices, single-tranche funds, and direct co-investments to shape markets rather than follow them. For wealth managers, the takeaway is clear: the 60/40 portfolio is dead. The 2019 playbook—with its emphasis on private equity, real assets, and geopolitical hedges—will continue to dominate as long as public market volatility persists. The question now is not whether HNWIs will keep diversifying, but how quickly they will embrace new asset classes, from AI-driven venture capital to climate-adaptive infrastructure. The 2019 allocation patterns were a warning; the 2020s will be the decade of execution.Comprehensive FAQs
Q: How did tax policy in 2019 specifically influence HNWI asset allocation?
The 2017 U.S. Tax Cuts and Jobs Act lowered capital gains rates, incentivizing opportunity zone investments and pass-through entities. Meanwhile, European HNWIs faced higher capital taxes, driving demand for art, collectibles, and real estate—assets with lower taxable gains. The ECB’s negative rates also pressured bond allocations, pushing HNWIs toward private credit and alternatives with higher yields.
Q: Were there regional differences in 2019 allocation strategies?
Yes. U.S. HNWIs favored private equity and venture capital, while European HNWIs leaned into art and real estate for tax efficiency. Middle Eastern investors routed capital through Swiss/Luxembourg funds to avoid sanctions, and Asian HNWIs diversified into Singapore/Hong Kong property. Latin American HNWIs, however, remained heavily exposed to local equities and commodities due to limited alternative options.
Q: Did family offices play a bigger role in 2019 allocations?
Absolutely. Family offices—managing $10 trillion+—became the primary vehicle for HNWI allocations in 2019. They allowed for greater discretion in private equity, real assets, and direct co-investments, which traditional asset managers couldn’t match. By year-end, ~60% of HNWI alternative allocations were managed through family offices or single-family structures.
Q: How did Brexit affect UK HNWI asset allocation in 2019?
UK HNWIs accelerated capital outflows in 2019, with ~£30–40 billion reportedly moved to EU jurisdictions (e.g., Dubai, Singapore, Switzerland). They also increased allocations to gold and farmland as hedges. The pound’s depreciation made overseas real estate more attractive, particularly in Germany and France, where property taxes are lower.
Q: Were there any sectors that underperformed in 2019 HNWI allocations?
Public equities saw a relative decline, dropping from 45% to 38% of portfolios. Hedge funds also underperformed, as many HNWIs shifted to private credit for similar yields with less volatility. Emerging market debt was another laggard, as trade wars and currency risks deterred allocations.
Q: How did the rise of fintech impact 2019 HNWI strategies?
Fintech enabled greater access to alternatives—platforms like Secondaries Market, RealtyMogul, and Masterworks allowed HNWIs to invest in private equity, real estate, and art with lower minimums. However, trust in custody solutions (e.g., Coinbase for crypto, ArtTactic for art) remained a hurdle. By 2019, ~15% of HNWIs used fintech for alternative allocations, a figure expected to grow.
Q: What was the biggest mistake HNWIs made in 2019 allocations?
The biggest misstep was overconcentration in late-stage venture capital. While Series C/D startups delivered strong returns, the lack of liquidity became apparent in 2020 as IPO windows closed. Another error was underallocating to inflation hedges—gold and farmland saw stronger demand in 2020–2021 as central banks printed money.
Q: How do 2019 allocation trends compare to 2023?
By 2023, private equity allocations grew further (now ~30% of portfolios), while public equities shrank to ~30%. Crypto allocations (now 2–4%) and ESG-focused real assets (e.g., renewable energy) gained traction. The biggest shift? HNWIs now actively manage liquidity—holding 10–15% in cash equivalents as a buffer against geopolitical and market shocks. The 2019 playbook evolved into a more dynamic, crisis-ready strategy.
