The Complete Overview of 2% of Americans Net Worth $5 Million
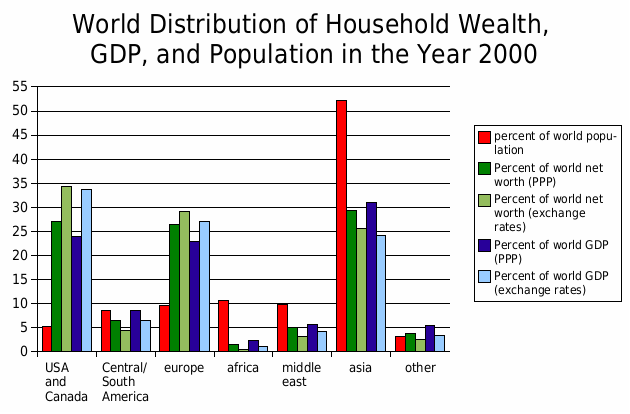
The concentration of wealth at the $5 million+ level is a hallmark of structural inequality. Federal Reserve data shows that roughly 2% of U.S. households—about 3.5 million families—hold net worths in this range, yet their collective assets exceed $20 trillion. That’s more than the GDP of all but a handful of nations. This isn’t just about individual success; it’s about systemic advantages. Tax policies favor capital gains over labor income, estate laws preserve dynastic wealth, and access to private markets (like hedge funds or syndicated real estate) accelerates accumulation. The result? A feedback loop where the ultra-wealthy reinvest in assets that appreciate faster than wages, widening the gap. The implications stretch beyond personal finance. Cities like New York and San Francisco see home prices inflated by foreign and domestic buyers with $5 million+ portfolios. Political campaigns are funded by donors in this bracket, shaping policies that further entrench their advantages. Even cultural trends—from private islands to space tourism—are often pioneered by this cohort. Their spending isn’t just consumption; it’s a signal of what’s next for the economy. Yet for all their influence, they remain statistically invisible in discussions about the "average American."Historical Background and Evolution
The modern era of $5 million+ wealth in America traces back to the post-WWII tax reforms of the 1940s and 1950s, when capital gains were taxed at lower rates than income. The 1980s saw this trend accelerate under Reagan-era policies, which slashed estate taxes and deregulated financial markets. By the 1990s, the rise of private equity and tech IPOs created new pathways to ultra-high net worth. The dot-com boom and subsequent bust revealed another pattern: even crashes didn’t erase wealth when assets were diversified across stocks, real estate, and alternative investments. The 2008 financial crisis didn’t disrupt this class—it reinforced it. While middle-class households lost 37% of their median net worth, those with $5 million+ saw their wealth grow by 11% over the same period, according to the Federal Reserve. The recovery further cemented their dominance: quantitative easing and near-zero interest rates allowed them to borrow cheaply, buy distressed assets, and deploy capital in ways unavailable to others. Today, the $5 million threshold isn’t just a milestone—it’s a gateway to a different economic reality, one where risk is mitigated by scale and access.Core Mechanisms: How It Works
Wealth at this level isn’t passive. It’s actively managed through a mix of tax-efficient structures and high-return strategies. The most common vehicles include: - Family limited partnerships (FLPs), which allow wealth to be transferred to heirs with minimal tax impact. - Grantor retained annuity trusts (GRATs), used to shift appreciating assets to beneficiaries tax-free. - Offshore accounts, often in jurisdictions like the Cayman Islands or Switzerland, where capital gains taxes are negligible. - Private equity and venture capital, where $5 million+ investors gain access to deals closed to retail markets. The mechanics extend beyond finance. This cohort often leverages dynastic trusts, which can last for generations, ensuring wealth persists even if future earnings stagnate. Their spending, too, follows patterns: luxury real estate in primary cities, art as a hedge against inflation, and philanthropy that carries tax benefits. The result is a closed-loop system where wealth begets more wealth, insulated from the economic shocks that destabilize broader society.Key Benefits and Crucial Impact
The advantages of belonging to the 2% with $5 million+ net worth are structural. They include tax arbitrage (paying lower effective rates than middle-class earners), liquidity advantages (access to private markets), and political leverage (donations that shape policy). Their spending doesn’t just drive demand—it reshapes entire industries. Consider the rise of fractional ownership in art or the surge in private jet travel; both reflect the preferences of this demographic. Even cultural shifts, like the normalization of remote work, were accelerated by tech billionaires who could afford to experiment without traditional office constraints. The economic impact is equally pronounced. Studies show that when this cohort invests in startups or real estate, it creates jobs—but often in high-skilled, high-paying roles that benefit fewer workers overall. Their consumption patterns also distort markets: a $20 million Manhattan penthouse purchase doesn’t just add to GDP; it bids up prices for everyone else. The feedback loop is clear: their wealth grows faster than the economy as a whole, ensuring their dominance persists."Wealth at this level isn’t about money—it’s about control. The tools to preserve and grow it are designed by those who already have it, for those who already have it." — James Henry, economist and wealth inequality researcher
Major Advantages
- Tax optimization: Strategies like step-up in basis (inheritance tax exemptions) and charitable remainder trusts reduce liabilities to near-zero for many.
- Asset diversification: Access to private equity, hedge funds, and alternative investments yields returns inaccessible to retail investors.
- Political influence: Donations to candidates and lobbying efforts directly shape policies that benefit high-net-worth individuals.
- Generational wealth transfer: Tools like dynasty trusts ensure assets remain within families, bypassing erosion from inflation or market downturns.
Comparative Analysis
| Metric | 2% with $5M+ Net Worth | Top 1% (Includes Lower Tier) |
|---|---|---|
| Median Net Worth | $5.2 million (varies by source) | $2.5 million |
| Primary Wealth Sources | Business ownership, private equity, real estate | Stocks, executive compensation, real estate |
| Tax Burden | Effective rate ~15-20% | Effective rate ~25-30% |
| Political Engagement | High (direct donations, PACs, lobbying) | Moderate (donations, voting) |
Future Trends and Innovations
The next decade will likely see further concentration among the $5 million+ cohort. Advances in AI-driven wealth management will allow this group to automate tax optimization and investment strategies with precision. Meanwhile, cryptocurrency and decentralized finance (DeFi) are emerging as new tools for wealth preservation, though adoption remains uneven. The rise of impact investing—where ultra-high-net-worth individuals fund sustainable projects—could also reshape their portfolios, though profitability remains the primary driver. Politically, debates over wealth taxes and inheritance reforms will intensify, but structural changes are unlikely without mass pressure. The cohort’s ability to lobby and donate ensures that policies favoring capital accumulation will persist. Economically, their focus on alternative assets (like rare art or collectibles) will continue, as traditional markets saturate. The result? A future where the 2% with $5 million+ net worth wields even greater influence—unless systemic shifts force a reckoning.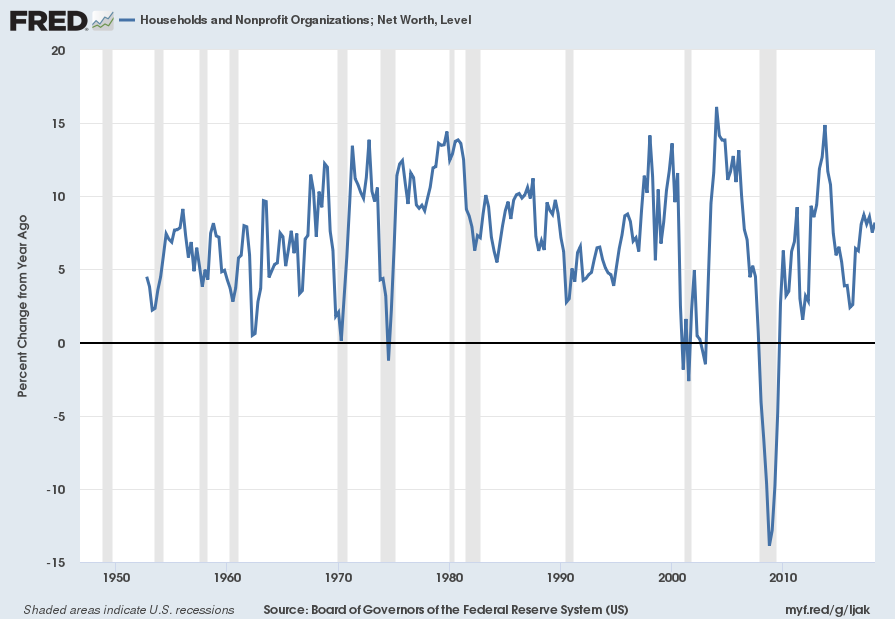
Conclusion
The 2% of Americans with net worths exceeding $5 million aren’t just wealthy—they’re a distinct economic caste. Their financial strategies, political clout, and cultural footprint ensure they operate on a different plane than the rest of society. The data tells a clear story: this group’s wealth grows faster than the economy, their taxes are lower, and their influence is outsized. Ignoring this reality means missing the core dynamics of modern capitalism. Yet for all their power, they’re not invincible. Economic crises, policy shifts, or social movements could disrupt their dominance—but only if the broader population recognizes their role in shaping the system. The question isn’t whether this cohort will persist; it’s whether the rest of America will tolerate it.Comprehensive FAQs
Q: How many Americans actually have $5 million in net worth?
Estimates vary, but federal data suggests around 3.5 million households—or roughly 2% of U.S. families—hold net worths of $5 million or more. This number has grown steadily since the 2008 recovery, driven by stock market gains and real estate appreciation.
Q: What’s the biggest advantage of being in this wealth bracket?
The primary edge is tax arbitrage. High-net-worth individuals use trusts, offshore accounts, and charitable giving to reduce their effective tax rate to 15-20%, far below the rates paid by middle-class earners. Additionally, access to private markets and political influence amplifies their financial returns.
Q: Can someone with a $5 million net worth lose it all?
While rare, it’s possible—especially if assets are concentrated in volatile sectors like tech startups or leveraged real estate. However, diversification strategies (e.g., holding cash, gold, or blue-chip stocks) and legal structures (like limited liability entities) make total loss extremely difficult for this cohort.
Q: How does this group compare to the top 0.1%?
The top 0.1% (net worth $10 million+) controls more liquid assets and wields greater political power, but the $5 million threshold is where tax optimization and dynastic wealth strategies become viable. The 0.1% often engages in philanthropy and global investments, while the 2% focuses on domestic asset preservation.
Q: Will wealth taxes ever affect this group?
Proposals like a 2% wealth tax on fortunes over $50 million have gained traction, but implementation faces legal and political hurdles. The 2% with $5 million+ net worth would likely see minimal direct impact, though indirect effects (e.g., reduced capital gains) could emerge if broader reforms pass.
