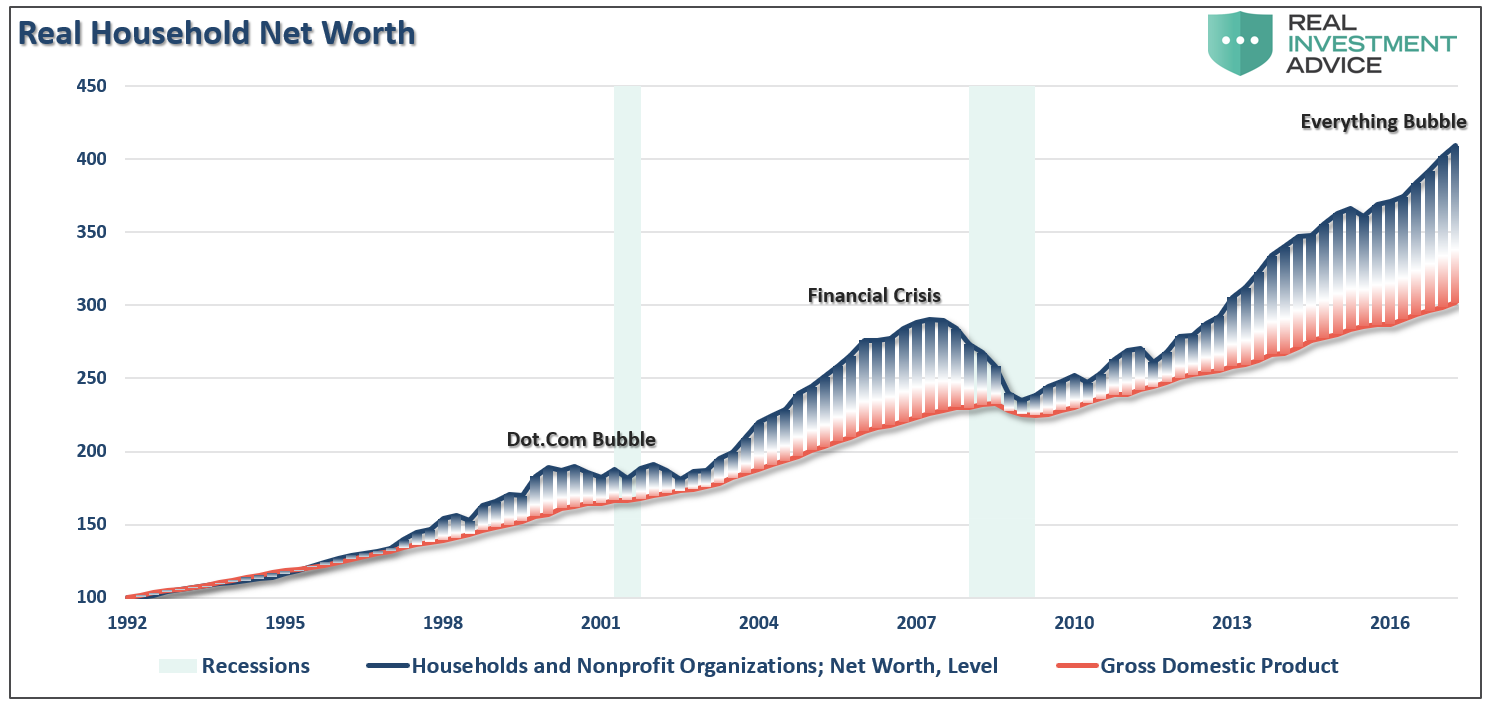
Where It All Began
The origins of tracking Households and Nonprofit Organizations; Net Worth breakdown by holdings trace back to the 1970s, when economists first attempted to quantify "unseen wealth." Before then, financial data focused almost exclusively on corporate balance sheets and government budgets. Households were treated as a monolith—statistics lumped middle-class families with billionaires under the same "net worth" umbrella. Nonprofits, meanwhile, were considered too fragmented to analyze. Their assets were scattered across tax-exempt filings, donor reports, and internal ledgers, making large-scale comparisons impossible. The breakthrough came when the Federal Reserve began publishing its Survey of Consumer Finances, which, for the first time, broke down household assets by type: stocks, bonds, home equity, and even collectibles. Around the same time, academic researchers like Robert Reich started dissecting nonprofit financials, revealing that institutions like Harvard and Yale managed endowments larger than the GDP of some nations. The realization hit hard: Households and Nonprofit Organizations; Net Worth breakdown by holdings weren’t just separate—they were two sides of the same economic coin. One side represented individual security; the other, institutional power.The Early Signs
By the 1990s, the disparities became harder to ignore. While the average American household’s net worth grew modestly, nonprofits saw explosive growth. Universities, for instance, reinvested tuition hikes into endowments, creating a feedback loop: higher fees → more donations → larger reserves → more prestige → higher fees. Meanwhile, households grappled with rising medical costs and a housing market that favored investors over first-time buyers. The gap wasn’t just numerical—it was structural. Nonprofits held illiquid assets (land, art, private equity), while households relied on liquid ones (cash, stocks, retirement accounts). The first major study to bridge the two worlds was a 2003 paper by the Urban Institute, which mapped how nonprofit holdings stabilized local economies during downturns. It found that hospitals and universities often acted as "wealth anchors," preventing mass foreclosures by buying distressed properties or offering low-interest loans. The catch? These interventions required transparency in Households and Nonprofit Organizations; Net Worth breakdown by holdings—something neither sector was accustomed to sharing. The data remained siloed, but the implications were clear: wealth wasn’t just personal or institutional; it was a shared ecosystem.The Turning Point
The 2008 crisis didn’t just expose inequality—it forced a reckoning. When household wealth plunged by nearly 20%, nonprofits became the only stable counterweight in many communities. Hospitals like Kaiser Permanente used their reserves to keep clinics open; universities like Stanford offered emergency grants to students. The shift wasn’t philanthropic—it was pragmatic. Nonprofits realized their survival depended on the health of the households around them. Conversely, households began to see nonprofits not just as service providers but as economic partners. The turning point wasn’t a single event but a series of policy changes. The Dodd-Frank Act, for example, required nonprofits with over $1 billion in assets to disclose more about their investments. Meanwhile, the rise of fintech made it easier for households to track their own net worth in real time. For the first time, the two sectors were forced to acknowledge their interdependence. A family’s ability to save for college might hinge on a university’s endowment performance; a nonprofit’s ability to fund a food bank could depend on local homeowners’ property tax payments."We used to think of nonprofits as separate from the economy. Now we see them as the economy’s immune system—keeping it functional when other parts fail." — Economist Rachel Black, 2015
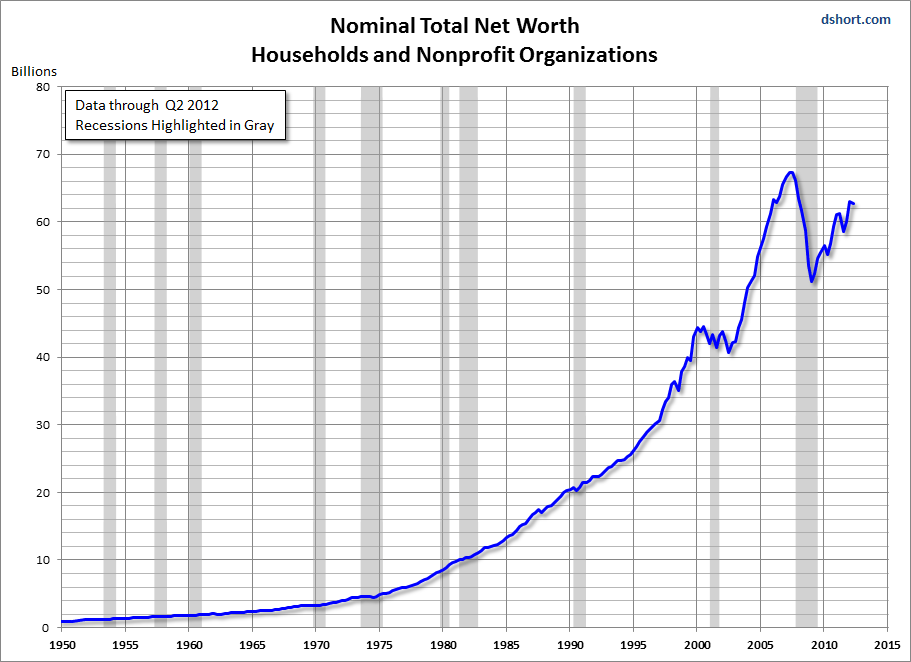
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1970s–1980s | Federal Reserve introduces Survey of Consumer Finances; nonprofits begin reporting assets to IRS but with minimal standardization. |
| 1990s | Endowment growth accelerates; households see stagnant wage growth but rising home values. First studies link nonprofit reserves to local economic stability. |
| 2000–2007 | Household debt peaks; nonprofits diversify into private equity and real estate. The term "Households and Nonprofit Organizations; Net Worth breakdown by holdings" enters academic discourse. |
| 2008–2012 | Crisis forces transparency: Dodd-Frank requires larger nonprofits to disclose investment strategies. Households shift to low-risk assets; nonprofits buy distressed properties. |
| 2015–Present | Impact investing rises; households use robo-advisors to mirror nonprofit diversification. Data-sharing initiatives (e.g., ProPublica’s Nonprofit Explorer) make Households and Nonprofit Organizations; Net Worth breakdown by holdings more accessible. |
Lessons From the Journey
- Liquidity matters. Households prioritize liquid assets (cash, stocks) for survival; nonprofits can afford illiquid ones (land, art) because their missions provide long-term stability.
- Transparency is a two-way street. Nonprofits resisted disclosing holdings for decades, but crises forced accountability. Households, meanwhile, now demand clarity from both sectors.
- Diversification isn’t just for the rich. Nonprofits proved that spreading risk across asset classes—even in downturns—can protect communities. Households are adopting similar strategies.
- Policy shapes outcomes. Tax laws favoring nonprofit endowments over household savings widened the gap until recent reforms.
- Technology bridges gaps. Fintech tools now let households track their net worth in real time, while AI analyzes nonprofit financials for efficiency.
- The future is collaborative. The most resilient systems will treat Households and Nonprofit Organizations; Net Worth breakdown by holdings as a single, interconnected ecosystem.
Where Things Stand Today
Today, the conversation around Households and Nonprofit Organizations; Net Worth breakdown by holdings is less about raw numbers and more about dynamics. Households, though still recovering from the pandemic, have embraced alternative investments—peer-to-peer lending, fractional real estate, and even micro-donations to nonprofits via apps like Patreon. Nonprofits, meanwhile, are under pressure to align their portfolios with their missions. A hospital’s endowment might now include green bonds to offset its carbon footprint, while a university’s holdings could prioritize diversity-focused startups. The biggest shift? Recognition that wealth isn’t static. A family’s net worth can rise or fall in months, while a nonprofit’s endowment might take decades to grow. The two sectors are learning to move in sync. When a nonprofit like the Ford Foundation announced it would liquidate half its endowment to fund grants, it sent ripples through household portfolios—some saw it as a vote of confidence in economic recovery, others as a warning. The lines between personal and institutional wealth are blurring, and the data reflects it.
Conclusion
The story of Households and Nonprofit Organizations; Net Worth breakdown by holdings is one of hidden connections. For decades, economists treated the two as separate entities, but the reality is far more intertwined. A household’s ability to weather a recession depends on the stability of local nonprofits, just as a nonprofit’s ability to fulfill its mission depends on the financial health of the communities it serves. The data confirms what policymakers and activists have long suspected: wealth isn’t just personal or institutional—it’s relational. Moving forward, the focus won’t be on who holds more, but on how those holdings interact. Will households gain tools to invest like nonprofits? Will nonprofits adopt household-level transparency? The answers will determine whether wealth remains a source of division—or a shared foundation for resilience.Comprehensive FAQs
Q: How do nonprofits typically allocate their holdings compared to households?
Nonprofits tend to hold a higher percentage of illiquid assets—real estate, private equity, and art—while households focus on liquid assets like cash, stocks, and retirement accounts. For example, a university’s endowment might allocate 30% to alternative investments, whereas the average household holds less than 5% in anything beyond traditional stocks and bonds.
Q: Can households invest like nonprofits do?
Not easily, due to regulatory and capital requirements. Nonprofits can invest in private markets (e.g., hedge funds) because they’re tax-exempt and have long horizons. Households, however, face restrictions like the Accredited Investor rule, which limits access to such opportunities. Platforms like Fundrise now offer fractional real estate investments, bridging the gap slightly.
Q: Why do nonprofits hold so much real estate?
Real estate is a stable, low-maintenance asset for nonprofits. Hospitals own clinics; universities own dorms and labs. It generates steady revenue (rental income) and appreciates over time. Households, meanwhile, often see real estate as a speculative asset, not a long-term holding.
Q: How has the pandemic affected the Households and Nonprofit Organizations; Net Worth breakdown by holdings?
The pandemic widened disparities. Household wealth dropped due to job losses and market volatility, while nonprofits with diversified endowments (e.g., hospitals, universities) saw minimal impact. Some nonprofits even bought distressed assets, further concentrating wealth in institutional hands.
Q: Are there tools to track nonprofit holdings like household net worth?
Yes, but they’re less user-friendly. Households use Mint or Personal Capital; nonprofits rely on IRS Form 990 filings (available via ProPublica’s Nonprofit Explorer) or commercial databases like GuideStar. The data is fragmented, but tools like Charity Navigator now include financial health metrics.
Q: What’s the biggest misconception about Households and Nonprofit Organizations; Net Worth breakdown by holdings?
That they operate in isolation. Many assume nonprofits are "above" market forces, while households are purely individual. In truth, a family’s ability to donate to a nonprofit depends on that nonprofit’s ability to create jobs or provide services—making their fates inseparable.
