
Common Myths About Household Net Worth US
The narrative around household net worth US thrives on oversimplifications. One persistent myth is that wealth is evenly distributed—a belief reinforced by political rhetoric and pop economics. In reality, the top 1% of households control nearly a third of all wealth, a concentration that hasn’t budged meaningfully since the 1980s. Another misconception is that homeownership alone secures financial stability. Yet in regions like Florida or California, where housing prices have outpaced wage growth, many homeowners are "underwater" in equity, their wealth tied to an asset that’s become a financial anchor. The idea that household net worth US is primarily driven by wages ignores the role of inheritance and asset appreciation. A 2022 study by the Urban Institute found that 62% of wealth for households aged 35–44 comes from inheritances or gifts—money that rarely enters the conversation about "earned" prosperity. Meanwhile, the assumption that student debt is the sole barrier to wealth overlooks how debt shapes long-term asset accumulation. A graduate with $100,000 in loans may delay buying a home, but that delay compounds over decades, widening the wealth gap with peers who inherited family homes or stock portfolios.Myth 1: The American Dream is Alive and Well for Most
The phrase "household net worth US" is often invoked to defend the idea that hard work leads to upward mobility. Yet the data tells a different story. A Brookings Institution analysis found that 43% of Americans would struggle to cover a $400 emergency expense in 2021, a figure unchanged from 2019. For these households, net worth isn’t a cushion—it’s a fragile ledge. The myth persists because mobility is measured in generations, not years. A child born in 1990 has a 30% chance of earning more than their parents; for a child born in 2000, that drops to 20%. The American Dream isn’t dead; it’s being outpaced by structural forces like healthcare costs and stagnant wages. What’s often missing from the conversation is how household net worth US is a lagging indicator. The wealth of a 65-year-old today reflects economic conditions from the 1980s and 90s—a period of deregulation, rising inequality, and the shift from manufacturing to finance. Younger generations, saddled with student debt and housing costs that exceed their incomes, are playing by rules that don’t favor them. The Fed’s data shows that millennials, now in their 40s, have yet to recover the wealth lost to the Great Recession. Their net worth is still 20% below where it would have been without the crisis.Myth 2: Retirement Savings Are on Track for the Average Household
The narrative that household net worth US includes robust retirement accounts ignores the reality for millions. The median retirement account balance for near-retirees (ages 55–64) is just $17,000, according to the Economic Policy Institute. For households of color, that figure is often zero. The myth of preparedness is propped up by the 401(k) system, which assumes consistent contributions over decades—a luxury unavailable to gig workers, part-time employees, or those in industries with erratic hours. Even for those who contribute, market volatility can erase years of savings. The 2022 bear market wiped out $5.2 trillion in household retirement wealth in a single year. The confusion deepens when retirement planning is framed as an individual responsibility rather than a systemic issue. Pension plans, once the backbone of middle-class security, have been replaced by defined-contribution accounts that shift risk onto workers. Meanwhile, Social Security—often dismissed as insufficient—remains the largest source of income for retirees, covering 39% of their needs. The gap between what households think they’ve saved and what they actually have is a ticking time bomb. For household net worth US, retirement isn’t a future concern; it’s a present crisis for those who’ve been left behind.Myth 3: Wealth is Just About Money in the Bank
The term "household net worth US" is frequently conflated with liquid assets, but wealth is as much about what you own as what you owe. A family with a paid-off home in Detroit may have a net worth of $200,000, while a tech executive in Austin with the same number might have $500,000 in stocks but $300,000 in student loans and a mortgage. The former’s wealth is tangible; the latter’s is speculative. This distinction matters when assessing financial resilience. During the pandemic, homeowners with equity weathered lockdowns better than renters, but that advantage evaporates if housing prices crash—or if a medical emergency forces a sale. The overemphasis on cash and stocks also ignores non-financial assets like social capital or access to networks that create opportunities. A study by Harvard’s Raj Chetty found that children born to parents in the top 1% are 77% more likely to attend elite colleges, a pipeline to high-paying jobs that compound wealth over lifetimes. For household net worth US, the real divide isn’t between rich and poor; it’s between those who inherit advantage and those who don’t. The Fed’s data captures the former but rarely the latter.
What Holds Up to Scrutiny
When stripped of myths, household net worth US reveals three verifiable truths. First, wealth is concentrated at the top, but the middle class isn’t disappearing—it’s shrinking. The Pew Research Center found that 52% of Americans were middle-income in 1971; by 2021, that had fallen to 50%. The difference is marginal, but the implications are profound: fewer households are within striking distance of the top 20%, and more are teetering on the edge of the bottom 40%. Second, debt is the great equalizer. Student loans, medical bills, and credit card debt don’t just reduce net worth; they limit future earning potential. A 2023 Federal Reserve report showed that households with debt have 30% less wealth than those without. Third, household net worth US is increasingly tied to housing—both as an asset and a liability. Homeownership rates have stabilized around 65%, but the value of that ownership varies wildly. In 2022, the typical homeowner’s net worth was $300,000, while renters’ was $8,000. The disparity isn’t just about ownership; it’s about location. A home in Wichita might be a wealth builder, while one in San Francisco is a financial albatross. The Fed’s data confirms that geographic inequality is as real as racial or generational inequality."Wealth isn’t just about what you earn; it’s about what you inherit, what you own, and what you owe. The American economy rewards the first two and punishes the third." — Edward N. Wolff, Professor of Economics at NYU
| Common Belief | What the Evidence Says |
|---|---|
| Most Americans are building wealth steadily. | Only 40% of households saw net worth grow between 2019 and 2022; the rest stagnated or declined. |
| Homeownership guarantees financial security. | 37% of homeowners have less than $5,000 in liquid savings, leaving them vulnerable to housing market shocks. |
| Retirement savings are on track for the average worker. | 65% of near-retirees have less than $100,000 in retirement accounts, with racial disparities widening. |
| Wealth gaps are closing due to economic growth. | The top 1% captured 53% of all income growth from 2009 to 2018, while the bottom 50% saw none. |
Why the Confusion Persists
The persistence of misconceptions about household net worth US isn’t accidental. Political narratives frame wealth as a personal achievement, deflecting blame from systemic factors like wage stagnation or healthcare costs. The financial industry benefits from the status quo: high-fee investment products, predatory lending, and the myth of "self-made" millionaires obscure the role of inherited advantage. Even the data itself is a double-edged sword. The Fed’s triennial Survey of Consumer Finances is the gold standard, but its three-year lag means it reflects the past, not the present. Cultural narratives also play a role. The rise of social media has amplified stories of overnight success—crypto millionaires, YouTube tycoons—while downplaying the slow grind of wealth accumulation. For household net worth US, the story of the 0.1% overshadows the 99.9%. Meanwhile, economic literacy remains low. A 2023 TIAA Institute survey found that only 36% of Americans can pass a basic financial literacy test. Without a shared understanding of how wealth is built (or lost), the confusion will endure.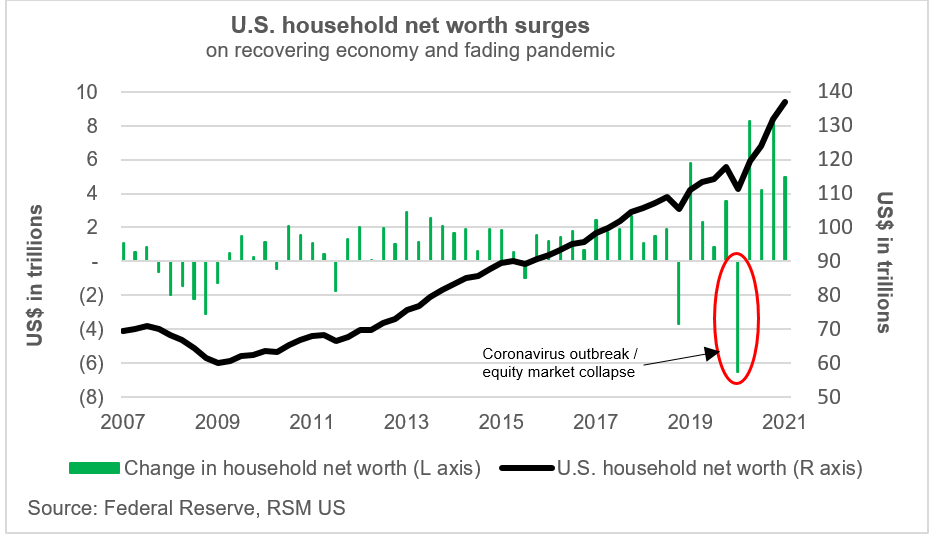
Conclusion
The story of household net worth US is one of contradictions. On one hand, aggregate wealth has never been higher—$148 trillion in 2023, up from $95 trillion in 2010. On the other, that wealth is concentrated in fewer hands than ever. The median household may have recovered from the 2008 crash, but the mean—distorted by billionaires and Wall Street—paints a rosier picture. The challenge isn’t just measuring wealth; it’s understanding who benefits from its growth and who gets left behind. Policy changes could shift the narrative. Expanding the Earned Income Tax Credit, cracking down on predatory lending, or reforming student debt could reshape household net worth US for the next generation. But without political will and public pressure, the myths will persist—and so will the inequality they mask. The numbers don’t lie, but they’re only part of the story.Comprehensive FAQs
Q: How often does the Federal Reserve update household net worth data?
The Fed releases its household net worth US figures quarterly, but the detailed Survey of Consumer Finances—used for long-term trends—comes out every three years. The most recent full report (2022) reflects data from 2019–2022, with a lag of up to four years.
Q: Does homeownership still matter for building wealth?
Yes, but with caveats. Homeowners have a median net worth of $300,000 vs. $8,000 for renters. However, location and mortgage terms matter. In high-cost areas, home equity may not translate to liquid savings, and underwater mortgages can erode wealth. The Fed’s data shows that homeownership’s wealth-building power has diminished since the 2008 crisis.
Q: Why do Black and Hispanic households have lower net worth?
Historical discrimination plays a role: redlining denied Black families access to mortgages for decades, while wealth-building tools like 401(k)s and homeownership were less accessible. Today, gaps persist due to wage disparities, higher student debt burdens, and systemic barriers in hiring and promotions. The median white household has 10 times the wealth of a Black household.
Q: Can student debt really derail wealth accumulation?
Absolutely. A 2023 study found that borrowers with $50,000+ in student debt have 20% lower net worth by age 40. The delay in buying homes or starting families compounds over time. Even after repayment, the lost decade of asset growth (stocks, home equity) creates a permanent wealth gap.
Q: How does inflation affect household net worth?
Inflation erodes the value of cash savings and fixed-income assets like bonds. However, household net worth US often rises during inflation if asset prices (homes, stocks) outpace price increases. The catch: wages rarely keep up. In 2022–2023, inflation ate into real wages, while asset prices surged—benefiting homeowners and investors but leaving renters and low-wage workers behind.
Q: Are there any bright spots in wealth distribution?
Yes, but they’re narrow. The gig economy has created new wealth pathways for skilled freelancers (e.g., software developers, consultants). Community land trusts and co-op housing models are emerging as alternatives to traditional homeownership. However, these remain exceptions, not trends. The biggest bright spot is policy: expanded child tax credits in 2021 temporarily reduced child poverty by 40%, proving that targeted interventions can work.
Q: What’s the biggest misconception about retirement savings?
The myth that household net worth US includes secure retirement accounts for most Americans. In reality, 65% of near-retirees have less than $100,000 saved, and 28% have nothing. The shift from pensions to 401(k)s has turned retirement into a gamble, with market volatility and longevity risks adding to the uncertainty.
