The Complete Overview of Household Net Worth Last Quarter 2017
The household net worth last quarter 2017 reached approximately $97.5 trillion, according to the Federal Reserve’s Flow of Funds report—a 2.2% increase from Q3 2017 and a 13.7% year-over-year surge. This growth was fueled by a combination of rising home values, bullish equity markets, and modest wage increases, though the latter failed to keep pace with asset appreciation. The data underscored a familiar pattern: wealth accumulation was heavily concentrated, with the top 1% holding nearly a third of all liquid assets, while the bottom 50% saw only marginal gains.
Yet beneath the headline figures, the quarter exposed critical vulnerabilities. Student debt continued to balloon, offsetting gains in other asset classes for younger households. Meanwhile, the rural-urban wealth gap widened, as metropolitan areas benefited disproportionately from tech-driven job growth and housing appreciation. For policymakers and economists, the question lingered: Was this growth sustainable, or merely a temporary reprieve before the next economic correction?
Historical Background and Evolution
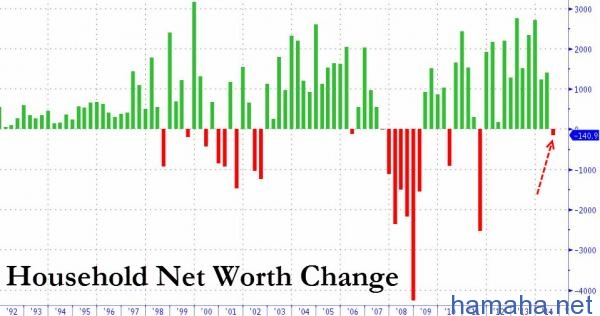
The trajectory of household net worth last quarter 2017 must be viewed through the lens of the 2008 financial crisis, which erased trillions in wealth overnight. By Q4 2017, the recovery had restored—and then some—pre-crisis levels, but the path to recovery was far from uniform. The Great Recession had devastated home equity, particularly in hard-hit states like California and Florida, where foreclosure rates remained elevated for years. The subsequent rebound in real estate prices, however, did not translate uniformly into broader prosperity.
The post-2008 era also saw a shift in wealth composition. Traditional pensions gave way to 401(k)s and IRAs, placing more financial risk on individual households. The household net worth last quarter 2017 reflected this shift, with retirement accounts accounting for roughly 28% of total net worth—up from 20% in 2000. This structural change meant that market volatility, policy changes, and employer contributions became even more critical determinants of long-term financial security.
Core Mechanisms: How It Works
Three primary drivers shaped the household net worth last quarter 2017: asset valuation, income distribution, and policy levers. Real estate, the largest component of household wealth, benefited from tight housing inventory and steady demand, pushing prices up by an average of 6.2% year-over-year. Meanwhile, the S&P 500’s 19.4% gain in 2017 translated into paper wealth for those with stock holdings, though participation remained skewed toward higher-income brackets.
Income played a secondary but critical role. While hourly wages grew by just 2.5% annually, bonuses and capital gains skewed wealth upward. Tax reforms enacted in late 2017—though not yet fully implemented—promised to further alter the landscape, with potential windfalls for corporations and high-net-worth individuals. The household net worth last quarter 2017 thus served as a baseline before these policy changes took full effect, offering a glimpse into the pre-reform economic state.
Key Benefits and Crucial Impact
The household net worth last quarter 2017 figures offered more than just a financial benchmark; they revealed the underlying health of consumer spending, savings rates, and economic confidence. Higher net worth typically correlates with increased consumption, which in turn stimulates job growth and business investment. Yet the data also highlighted systemic inequalities, where wealth begets wealth, and debt perpetuates cycles of financial strain for lower-income families.
For individuals, rising net worth translated into greater access to credit, home equity loans, and retirement planning flexibility. However, the benefits were not evenly distributed. Families with diversified portfolios—spanning stocks, real estate, and business ownership—fared far better than those reliant on stagnant wages or high-interest debt. The quarter’s numbers thus raised questions about the sustainability of this growth and whether it would translate into broader economic mobility.
"Wealth is not just about what you own; it’s about what you can do with what you own—and for too many, the door remains locked." — Edward N. Wolff, Professor of Economics at NYU
Major Advantages
- Asset Appreciation: Real estate and equities drove the bulk of net worth growth, benefiting homeowners and investors.
- Debt Reduction: Mortgage delinquencies hit historic lows, improving financial stability for millions.
- Retirement Security: Rising 401(k) and IRA balances provided a cushion against economic downturns.
- Policy Tailwinds: Pre-tax reform expectations boosted confidence, though long-term impacts remained uncertain.

Comparative Analysis
| Metric | Q4 2017 vs. Q4 2016 |
|---|---|
| Total Household Net Worth | +13.7% (from $86.6T to $97.5T) |
| Real Estate Holdings | +6.2% (driven by urban markets) |
| Financial Assets (Stocks/Bonds) | +19.4% (S&P 500 led gains) |
| Student Debt Burden | +4.5% (offsetting gains for younger households) |
Future Trends and Innovations
Looking ahead, the household net worth last quarter 2017 data suggests two competing forces: continued asset inflation and rising income inequality. The tax reforms of 2017 were expected to accelerate corporate profits and high-end wage growth, potentially widening the wealth gap further. Meanwhile, technological disruption—automation, gig economy growth—could reshape earning potential, particularly for middle-skill workers. The challenge for policymakers lies in ensuring that future net worth growth is inclusive, not just concentrated.
Emerging trends, such as the rise of alternative investments (cryptocurrencies, peer-to-peer lending) and the growing influence of millennial financial behaviors, may also redefine wealth accumulation. However, without structural changes to address wage stagnation and debt burdens, the household net worth trajectory could remain as uneven as it was in Q4 2017.
Conclusion
The household net worth last quarter 2017 was a mixed bag: a recovery in progress, but one marred by persistent disparities. The data confirmed that wealth accumulation is not a level playing field, where access to capital, education, and stable employment remains the primary differentiators. For economists, the figures served as a reminder that macroeconomic health does not always translate to individual prosperity. Moving forward, the focus must shift from aggregate growth to equitable distribution—before the next crisis exposes even deeper fractures.
The quarter’s snapshot also highlighted the fragility of financial security. A single market downturn, job loss, or policy misstep could reverse years of progress for vulnerable households. The lesson from Q4 2017 is clear: sustainable wealth requires more than rising asset prices—it demands systemic reforms to close the gaps that have long defined American economics.
Comprehensive FAQs
#### Q: How was household net worth calculated in Q4 2017?
The Federal Reserve’s Flow of Funds report aggregates assets (real estate, financial securities, business equity) and subtracts liabilities (mortgages, student loans, credit card debt). The household net worth last quarter 2017 total was derived from this balance, with adjustments for inflation and demographic weighting.
####Q: Did all regions see equal growth in net worth?
No. Urban areas, particularly coastal cities, led gains due to real estate appreciation, while rural and Rust Belt regions lagged. The household net worth last quarter 2017 data showed a 15% disparity between the highest- and lowest-performing states.
####Q: How did student debt affect net worth?
Student debt offset asset gains for younger households, with borrowers under 35 seeing net worth growth half the national average. The household net worth last quarter 2017 figures revealed that 44% of 25-34-year-olds carried student loans, compared to 11% of those 65+.
####Q: Were there differences by income percentile?
Yes. The top 10% of households held 71% of all liquid assets, while the bottom 50% collectively owned just 2.6%. The household net worth last quarter 2017 data reinforced that wealth begets wealth, with inheritance and capital gains playing outsized roles.
####Q: How did the stock market’s performance impact net worth?
The S&P 500’s 19.4% gain in 2017 directly boosted net worth for stockholders, but only 55% of U.S. households owned equities. The household net worth last quarter 2017 growth was thus concentrated among those with retirement accounts or direct investments.
####Q: What role did homeownership play?
Homeowners accounted for 63% of net worth growth, as housing prices rose 6.2% nationally. Renters, meanwhile, saw no direct benefit, widening the wealth divide between owner-occupied and rental households.
####Q: How did tax policy changes influence the outlook?
While not yet fully implemented, the 2017 Tax Cuts and Jobs Act was expected to boost corporate profits and high-end wages, potentially accelerating net worth growth for the wealthy. The household net worth last quarter 2017 data served as a pre-reform benchmark for assessing these impacts.
####Q: What were the biggest risks to sustained growth?
Rising interest rates, a market correction, or wage stagnation could derail progress. The household net worth last quarter 2017 figures also highlighted debt vulnerabilities, particularly for millennials and low-income families.
