
6 Things Worth Knowing About Household Net Worth Falls by Largest Amount Since the Great Recession
The scale of this wealth destruction demands close examination. Below are six critical dimensions of the crisis, each revealing how deeply the decline is reshaping economic behavior—and what it means for the future.1. The Real Estate Avalanche: Homeowners Bear the Brunt
Real estate has long been the cornerstone of American wealth, but today it’s the primary driver of the decline. Home values, which surged during the pandemic fueled by ultra-low rates and remote-work demand, are now correcting at a pace not seen since the mid-2000s. In markets like San Francisco, Seattle, and Austin—where prices had inflated by 50% or more—homeowners are facing forced sales, negative equity, or the grim prospect of "underwater" mortgages. The Federal Reserve estimates that household net worth falls by largest amount since the Great Recession is directly tied to a $1.5 trillion drop in real estate equity in just six months, according to preliminary Zillow and CoreLogic data. The impact isn’t limited to coastal cities. Even in traditionally stable markets like Dallas or Phoenix, homeowners who bought at peak pandemic prices now find themselves trapped between unaffordable rates (7%+) and stagnant wage growth. The share of homeowners with negative equity—owing more than their homes are worth—has doubled since early 2022, reversing years of post-recession recovery. For millions, the American Dream of generational wealth transfer is fracturing at the seams.2. Stock Market Bloodbath: Retirement Accounts Take a Hit
While real estate dominates the headline numbers, retirement portfolios are hemorrhaging value too. The S&P 500’s 20% decline from its January peak has directly translated into trillions in lost wealth, with 401(k)s and IRAs taking the brunt. The Federal Reserve’s data shows that financial assets—stocks, bonds, and mutual funds—account for nearly half of the total wealth contraction, a figure that underscores how vulnerable middle-class savers remain to market volatility. For near-retirees, the damage is existential: those who relied on sequence-of-returns risk (early withdrawals during a downturn) now face permanent reductions in lifetime income. The psychological toll is equally severe. A recent Bankrate survey found that 62% of Americans with retirement accounts have delayed contributions due to market uncertainty, a behavior that compounds the problem over time. Economists warn that if this trend persists, the household net worth falls by largest amount since the Great Recession could morph into a long-term savings crisis, with millions of households postponing retirement or working well into their 70s.3. The Debt Overhang: Credit Cards and Student Loans Worsen the Bleed
Wealth isn’t just about assets—it’s about liabilities too. As net worth plunges, debt levels remain stubbornly high, creating a vicious cycle. Credit card balances, which had spiked during the pandemic, are now defaulting at rates not seen since 2009, according to the New York Fed. Meanwhile, student loan payments have resumed, adding another layer of financial strain to households already stretched thin. The result? Leverage ratios are deteriorating, meaning that for every dollar of wealth lost, debt service obligations are eating up a larger share of disposable income. This dynamic is particularly acute for Gen X and Millennials, who carry both student debt and mortgages. A recent Urban Institute report found that households with student loans saw their net worth decline 20% faster than those without, exacerbating wealth gaps by race and education. The Fed’s data suggests that total household debt now exceeds $17 trillion, a figure that, when combined with the wealth contraction, creates a liquidity crisis for millions.4. The Wage Stagnation Factor: Why This Crisis Feels Different
Here’s the cruel irony: wages aren’t keeping up. While the unemployment rate remains low, real wages have stagnated, meaning that even as prices rise, paychecks don’t stretch as far as they used to. The Bureau of Labor Statistics reports that inflation-adjusted wages have grown by just 1.2% annually over the past five years, a figure that fails to offset the 15%+ decline in purchasing power for essentials like groceries and housing. When net worth plummets and incomes don’t rise, the result is forced asset liquidation—selling stocks, tapping home equity, or even skipping retirement contributions to cover daily expenses. This wage stagnation is why the current household net worth falls by largest amount since the Great Recession feels more personal than past downturns. In 2008, many could still rely on a stronger social safety net or family support. Today, savings buffers are thin, and the gig economy’s instability means that even white-collar workers face job insecurity. The combination of wealth destruction and wage suppression is creating a double whammy that economists warn could prolong the recovery.5. The Regional Divide: Where the Pain Is Most Acute
The wealth decline isn’t uniform—some areas are faring far worse than others. Coastal cities like San Francisco, Miami, and New York have seen home values drop by 10–15% in under a year, while Sun Belt markets like Nashville and Boise are experiencing rental crises as affordability collapses. Rural America, meanwhile, is grappling with declining farmland values and brain drain, further eroding local wealth. The Fed’s regional breakdown reveals that households in the West and Northeast have suffered the steepest declines, while Southern states—where wages are lower but home prices had inflated less—are holding up slightly better. What’s striking is how this geographic disparity mirrors racial wealth gaps. A Brookings Institution study found that Black and Hispanic households lost a disproportionate share of wealth during the pandemic rebound—and now, as net worth plummets again, those gaps are widening. The data shows that for every dollar of wealth lost by white households, Latino households lose $1.30, and Black households lose $1.50. This isn’t just an economic issue; it’s a social stability issue."This isn’t a recession—it’s a wealth reset. And unlike 2008, when the pain was concentrated in finance and housing, today’s crisis is hitting Main Street harder. The middle class is the shock absorber, and it’s breaking." — Darrick Hamilton, economist and Henry Cohen Professor at The New School
6. The Policy Paradox: Why Central Banks Can’t Fix This Alone
The Federal Reserve’s aggressive rate hikes—meant to tame inflation—have accelerated the wealth destruction. By raising borrowing costs, the Fed has crushed homebuyer demand, triggered mortgage refinancing waves, and punished risk assets like stocks and crypto. Yet, even as net worth falls by the largest amount since the Great Recession, inflation remains stubbornly high, leaving policymakers in a damned-if-you-do, damned-if-you-don’t scenario. The problem? Monetary policy works with a lag. By the time rate cuts take effect, the damage to retirement accounts, home equity, and small-business valuations may already be permanent. Economists like Larry Summers have warned that the Fed’s tightening cycle could push the economy into a "hard landing"—a scenario where unemployment spikes and wealth losses deepen. The alternative—keeping rates high for too long—risks prolonging the pain, as households delay major purchases and businesses cut back on hiring.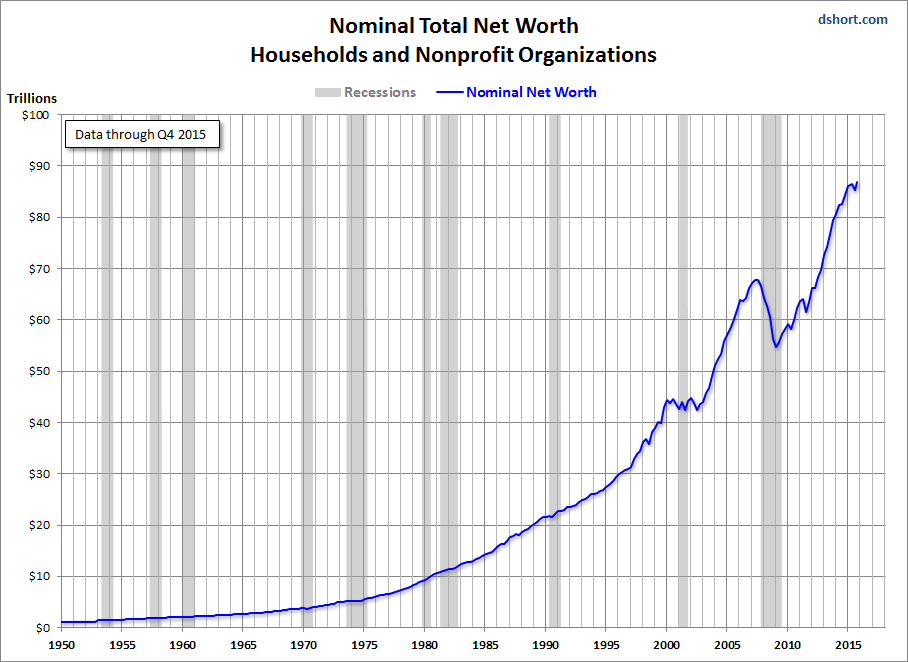
How These Facts Connect
The household net worth falls by largest amount since the Great Recession isn’t an isolated event—it’s the culmination of a decade of economic imbalances. The pandemic boom created artificial wealth through asset inflation, but the post-COVID correction has exposed how fragile that prosperity was. Real estate bubbles, overleveraged retirees, stagnant wages, and regional disparities all converged to produce this perfect storm of wealth destruction. What’s most concerning is the feedback loop now in motion. As net worth declines, consumer spending weakens, which hurts businesses, which leads to layoffs, which further erodes confidence. The Fed’s data suggests that household spending has already dropped by 3% in the past quarter, a figure that could trigger a recession if it persists. The 2008 crisis was about banks; this one is about people—and that makes it more dangerous.| Factor | Impact on Net Worth | Demographic Hit Hardest | Policy Response |
|---|---|---|---|
| Real Estate Correction | $1.5T+ in lost equity | Homeowners aged 55–64 (near-retirement) | No direct intervention; mortgage relief unlikely |
| Stock Market Decline | $8T+ in retirement account losses | Gen X (sandwich generation) | Fed rate cuts (too late for many) |
| Debt Overhang | Credit card delinquencies up 40% YoY | Millennials with student loans | Bankruptcy reform discussions |
| Wage Stagnation | Real wages flat for 5+ years | Low-income workers (no asset recovery) | No fiscal stimulus in sight |

Conclusion
The household net worth falls by largest amount since the Great Recession is more than a statistical footnote—it’s a warning sign of deeper economic dysfunction. The combination of asset price corrections, debt burdens, and wage stagnation suggests that millions of Americans are one shock away from financial ruin. Unlike 2008, when the crisis was contained to Wall Street, today’s decline is broad-based and personal, affecting renters, homeowners, and retirees alike. The question now isn’t if this will lead to a recession, but how severe it will be. If history is any guide, wealth destruction of this magnitude typically precedes unemployment spikes and credit crunches. The Fed may have tools to soften the landing, but the structural issues—inequality, debt, and wage suppression—won’t be fixed by rate cuts alone. Without bold fiscal interventions—whether through student debt relief, wage subsidies, or housing support—the household net worth falls by largest amount since the Great Recession could reshape the economy for a generation.Comprehensive FAQs
Q: Will this lead to a recession?
A: The risk is high. Historically, wealth declines of this magnitude (especially when coupled with rising unemployment expectations) have preceded recessions. The Fed’s own projections suggest a 50% chance of a mild downturn in 2024, but if consumer spending continues to drop, that timeline could accelerate. The key variable is employer response—if layoffs pick up, the recession could become self-reinforcing.
Q: Are there any groups benefiting from this decline?
A: Landlords in high-demand rental markets (e.g., Austin, Phoenix) are seeing rising occupancy rates and rents, while banks and credit card companies benefit from higher interest income. However, these gains are narrow and temporary—if the economy weakens, commercial real estate and consumer debt defaults could undo those benefits quickly.
Q: How does this compare to the 2008 financial crisis?
A: The scale of wealth destruction is similar, but the composition is different. In 2008, financial assets (stocks, bonds) drove most losses; today, real estate and retirement accounts are the primary victims. Also, government intervention was massive in 2008 (TARP, QE)—today, fiscal tools are limited, and the Fed’s options are constrained by inflation.
Q: Can individuals protect their wealth in this environment?
A: Diversification is key—relying solely on stocks or real estate is risky. Experts recommend increasing cash reserves, refinancing high-interest debt, and avoiding margin calls on investments. For retirees, annuity products or bond ladders can provide stability, but no strategy is foolproof in a prolonged downturn.
Q: Will this affect mortgage rates?
A: Likely yes—but not immediately. Mortgage rates are tied to Treasury yields, which may fall if a recession hits, but banks are already tightening lending standards. Even if rates drop to 6%, underwater homeowners and those with adjustable-rate mortgages will still face payment shocks. The real risk is a wave of foreclosures if unemployment rises.
Q: How long will it take for wealth to recover?
A: At least 3–5 years, assuming a shallow recession. The 2008 recovery took a decade for many households, and today’s debt levels and wage stagnation suggest a slower rebound. Younger households (under 35) may see faster recovery if they re-enter the job market with higher wages, but older cohorts (55+) could face permanent wealth losses.
Q: Could this trigger a political backlash?
A: Absolutely. The wealth gap is already a political fault line, and if millions see their retirement or home equity vanish, populist pressure will grow. Student debt relief, Medicare for All, and housing reforms could dominate the 2024 election, while anti-immigration rhetoric may surge if job competition is blamed for wage stagnation. The 2008 crisis fueled the Tea Party movement; this one could spark an even more volatile response.
Q: What’s the biggest misconception about this wealth decline?
A: Assuming it’s temporary. Many believe stocks or housing will rebound quickly, but structural issues—overvalued assets, debt burdens, and wage suppression—won’t disappear with a market bounce. The Great Recession taught us that wealth recovery is nonlinear; this decline could have lasting scars, especially for minority and low-income households.
