
7 Things Worth Knowing About Household Net Worth 2024
The household net worth 2024 snapshot isn’t monolithic. It’s a mosaic of regional disparities, asset-class volatility, and demographic divides. Below are the seven forces reshaping the picture—and why they matter beyond the balance sheet.1. Aggregate Wealth Hits Record Highs, But Median Stagnates
National-level household net worth 2024 figures often dominate headlines, and for good reason: in the U.S., the Federal Reserve’s latest estimates place total household wealth at levels not seen since the dot-com boom, adjusted for inflation. The drivers are familiar—rising home values in sunbelt states, a bull market in equities, and low interest rates that inflated asset prices across the board. Yet when you peel back the aggregate layer, the median household net worth 2024 tells a different story. For the typical American family, wealth growth has been sluggish at best, with the median figure rising by less than 2% year-over-year in real terms. The disparity between aggregate and median wealth underscores a fundamental truth: a small fraction of households are driving the majority of gains. This isn’t just an American phenomenon. In Europe, central bank data shows a similar bifurcation, where top deciles in Germany or the Netherlands have seen wealth multiples outpace broader populations. The implication? Wealth concentration is accelerating, and the traditional safety net—homeownership as a wealth-building tool—is increasingly inaccessible to younger generations. Policymakers are taking notice, with some advocating for targeted tax reforms or expanded retirement savings incentives to address the gap.2. Homeownership Remains the Single Largest Wealth Driver—but Access Is Shrinking
For decades, home equity has been the cornerstone of household net worth 2024 accumulation. Today, it accounts for roughly 30% of total U.S. household wealth, a figure that climbs higher in regions like the Midwest or Southeast. Yet the path to homeownership is growing more arduous. Rising prices, coupled with higher mortgage rates (even as they’ve eased from 2023 peaks), have priced out first-time buyers in many markets. Inventory shortages and investor demand in gateway cities have only exacerbated the problem. The result? A household net worth 2024 gap where homeowners see their net worth swell by 10–15% annually in high-appreciation areas, while renters—who represent nearly 35% of U.S. households—see little to no growth in their liquid assets. The consequences ripple beyond individual balance sheets. Communities with low homeownership rates tend to have weaker local tax bases, reduced school funding, and higher poverty rates. Economists warn that if current trends persist, the next generation could see homeownership rates dip below 60%, a level not seen since the 1960s. For household net worth 2024 planners, this means the traditional playbook—buy a home, build equity, retire comfortably—is no longer a guaranteed path.3. Stock Market Gains Are a Double-Edged Sword
Publicly traded equities now represent nearly 40% of U.S. household net worth 2024, a share that has doubled since the 2000s. For those with 401(k)s or brokerage accounts, the S&P 500’s consistent upward trajectory has been a windfall. But the benefits aren’t evenly distributed. Households in the top 10% hold 80% of all stock ownership, while the bottom 50% own just 5%. Even among investors, the divide is stark: a retiree with a diversified portfolio benefits from compound growth, while a young worker with a single employer’s 401(k) faces concentration risk. Add in the volatility of 2022–2023—a 20% correction in some portfolios—and the message is clear: household net worth 2024 tied to the market is a high-reward, high-risk proposition. The psychological impact is equally significant. For older generations, stock gains have softened the blow of stagnant Social Security benefits. For younger investors, it’s created a cultural shift—household net worth 2024 is now as likely to be tracked via Robinhood app balances as traditional bank statements. Yet the reliance on volatile assets raises questions about long-term stability, particularly as interest rates remain elevated and corporate profit margins face headwinds.4. Student Debt Is a Wealth Drag Unlike Any Other
Student loan balances now exceed $1.7 trillion in the U.S., a figure that directly suppresses household net worth 2024 for millions. Borrowers with outstanding loans report net worth figures 30–40% lower than their debt-free peers, even when controlling for income. The effect isn’t just financial—it’s intergenerational. Parents with student debt are less likely to save for retirement or pass wealth to their children. Meanwhile, younger borrowers face a Catch-22: repaying loans eats into savings, but defaulting risks credit damage and wage garnishment. The household net worth 2024 penalty is most severe for Black and Latino borrowers, who carry higher debt loads relative to income and face systemic barriers to wealth accumulation. Politically, the issue is a lightning rod. Proposals range from universal loan forgiveness (which would add hundreds of billions to household net worth 2024 figures overnight) to income-based repayment reforms. Yet even if debt is forgiven, the underlying problem remains: higher education costs continue to outpace inflation, ensuring the next cohort of students will face the same dilemma. For household net worth 2024 strategists, the takeaway is simple—debt relief alone won’t close the wealth gap, but ignoring it will only deepen it.5. The Gig Economy’s Hidden Wealth Deficit
The rise of freelance and gig work has redefined household net worth 2024 for millions, but not in the way you’d expect. While platforms like Uber or Fiverr offer flexibility, they also create a liquid asset paradox: gig workers earn income but rarely accumulate traditional wealth-building tools like home equity or retirement accounts. A 2023 study found that gig workers’ median household net worth 2024 is 40% below that of full-time employees, even when adjusted for income. The reason? Lack of access to employer-sponsored plans, unpredictable cash flows, and the inability to leverage debt for appreciating assets. The trend is accelerating as AI and automation reshape labor markets. For household net worth 2024 planners, the challenge is clear: how to build wealth in an economy where job stability is increasingly tied to portfolio income rather than paychecks. The answer may lie in alternative strategies—cash-value life insurance policies, micro-investing apps, or peer-to-peer lending—but these require financial literacy that many gig workers lack.6. Inflation’s Lasting Scar: The Erosion of Savings
The household net worth 2024 recovery from the 2020 pandemic dip was never complete for one critical group: those who relied on cash savings. Between 2021 and 2023, inflation eroded the purchasing power of liquid assets by 15–20%, according to Federal Reserve estimates. For households with modest savings—often those already on the financial margins—the effect was devastating. Emergency funds vanished. Retirement contributions stalled. And the psychological toll was severe: a 2023 survey found that 60% of Americans reported stress over inflation, with nearly a third skipping medical care or delaying major purchases. The household net worth 2024 implications are twofold. First, the era of "saving aggressively" has given way to a new mantra: save and invest defensively. Second, the data suggests that future shocks—whether another inflation spike or a recession—will hit cash-dependent households harder than ever. For wealth managers, this means a shift toward inflation-protected assets (TIPS, real estate, commodities) and diversified income streams.7. The Inheritance Boom—and Its Dark Side
Blockquote: "Wealth isn’t just made; it’s inherited. And in 2024, the numbers don’t lie: the largest intergenerational wealth transfer in history is underway." — Edward N. Wolff, Professor of Economics at NYU and author of The Assets of the Very Rich The household net worth 2024 landscape is being reshaped by demographics. The $30 trillion in wealth expected to change hands over the next 25 years—primarily from Baby Boomers to Gen X and Millennials—will dwarf even the dot-com boom. Yet the distribution is anything but equal. The top 1% of heirs will receive 35% of total transfers, while the bottom 50% will get less than 5%. The result? A household net worth 2024 divide where inheritance becomes a zero-sum game: those who inherit climb the ladder, while those who don’t are left scrambling. The dark side? Inherited wealth often comes with strings attached—family businesses, real estate tied to emotional (rather than financial) value, or illiquid assets that don’t translate to spending power. For household net worth 2024 planners, this means a new set of challenges: how to manage sudden windfalls, how to avoid lifestyle inflation traps, and how to ensure wealth persists across generations.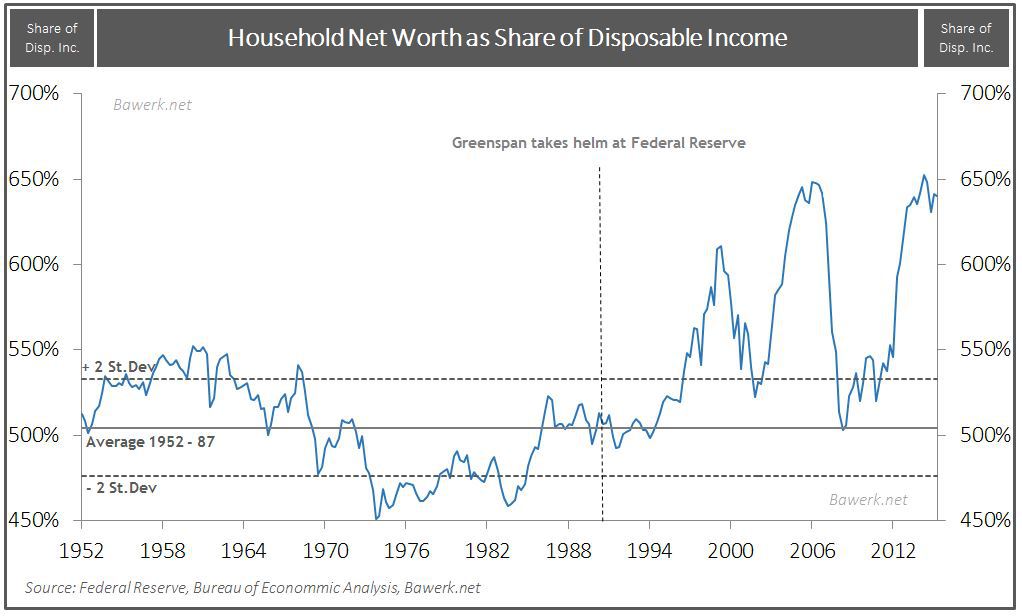
How These Facts Connect
The household net worth 2024 picture isn’t just a collection of statistics—it’s a system where each trend reinforces the others. Take homeownership, for example. Rising prices benefit existing owners but lock out first-time buyers, who then rely on renting—an arrangement that offers no wealth accumulation. Those renters, in turn, may turn to gig work or student debt to make ends meet, further suppressing their ability to save. Meanwhile, stock market gains flow disproportionately to older, wealthier households, while younger generations inherit a debt-laden economy. The cycle is self-perpetuating: wealth begets more wealth, while scarcity begets more scarcity. The policy implications are equally stark. Tax reforms that favor capital gains over labor income widen the gap. Housing policies that don’t address affordability deepen regional divides. And social safety nets that assume traditional employment structures are increasingly outdated. For individuals, the message is clear: household net worth 2024 is no longer just a function of income—it’s a game of asset access, timing, and luck. The question isn’t whether you’ll build wealth; it’s whether you’ll play by the rules of a system that’s stacked against you—or find a way to rewrite them.| Trend | Impact on Wealth | Who Benefits | Who Loses | Policy/Leverage Point |
|---|---|---|---|---|
| Aggregate vs. Median Wealth | Top 10% drive 80% of gains; median stagnates | Homeowners, stock investors, retirees | Young adults, renters, service workers | Progressive taxation, wealth redistribution |
| Homeownership Gap | Equity growth for owners; no growth for renters | Suburban/midwest homeowners | Urban renters, first-time buyers | Housing supply reforms, down payment assistance |
| Stock Market Concentration | Top decile holds 80% of stock wealth | Retirees, high-net-worth individuals | Young investors, low-income households | Retirement plan expansions, ESG investing incentives |
| Student Debt Burden | Net worth suppressed by 30–40% for borrowers | Debt-free graduates, public university attendees | Private college borrowers, minority students | Loan forgiveness, tuition caps, income-based repayment |
| Inheritance Boom | $30T transfer over 25 years, but top 1% gets 35% | Heirs of wealth, family business owners | Non-heirs, low-income families | Estate tax reforms, financial literacy programs |

Conclusion
The household net worth 2024 story isn’t one of uniform progress. It’s a tale of haves and have-nots, of asset inflation masking real economic strain, and of a system where opportunity is increasingly tied to who you know—or who you inherited from. For policymakers, the challenge is addressing the structural imbalances before they become permanent. For individuals, the takeaway is simpler: household net worth 2024 is no longer a passive outcome. It’s a strategy game, and the players who adapt—whether by diversifying assets, advocating for systemic change, or rethinking traditional wealth-building paths—will be the ones who thrive. The data won’t lie forever. But the choices made in 2024—from interest rate decisions to housing policy shifts—will determine whether the household net worth 2024 snapshot becomes a blueprint for the next decade or a cautionary tale of missed opportunities.Comprehensive FAQs
Q: How does household net worth 2024 compare to pre-pandemic levels?
The recovery has been uneven. While aggregate household net worth 2024 in the U.S. exceeds pre-2020 peaks by 15–20%, median figures remain 5–10% below where they would have been without the pandemic’s economic disruptions. The gap is widest for younger cohorts, whose wages and savings were hit hardest by inflation and supply chain shocks.
Q: Are there regions where household net worth 2024 is growing faster than others?
Yes. Sunbelt states (Texas, Florida, Arizona) and Rust Belt cities with revitalized manufacturing sectors (Detroit, Pittsburgh) are seeing household net worth 2024 growth outpace coastal hubs. The drivers include lower housing costs relative to wages, remote-work migration, and industrial rebirth. Meanwhile, cities like San Francisco and New York—once wealth magnets—are now seeing net worth stagnation for middle-class households due to high costs and slower job growth.
Q: How does household net worth 2024 differ by generation?
Gen X leads in household net worth 2024 per capita, thanks to the housing boom of the 2000s and strong stock market returns. Millennials trail by 30–40% due to student debt, lower homeownership rates, and stagnant wages. Baby Boomers, despite higher debt levels, benefit from inherited wealth and asset appreciation. Gen Z, still early in their earning years, has the lowest median household net worth 2024—but also the most exposure to gig economy volatility.
Q: Can I improve my household net worth 2024 if I’m not a homeowner or stock investor?
Absolutely, but the strategies differ. Non-homeowners can focus on high-yield savings accounts, index funds, or peer-to-peer lending to build liquid assets. Renters in high-appreciation areas might explore rent-to-own programs or co-op housing. For those without stock market access, employer-matched retirement plans or community investment programs (like credit unions) can bridge the gap. The key is leveraging what’s available—even if it’s not traditional.
Q: What’s the biggest risk to household net worth 2024 in the next 12 months?
The biggest wild card is interest rates. If the Federal Reserve cuts rates aggressively in 2024, home prices could surge in refinancing-friendly markets—but it could also trigger a stock market correction if growth slows. Conversely, if rates stay elevated, mortgage costs will suppress homeownership rates, and household net worth 2024 growth will rely even more on corporate profits than wages. Geopolitical shocks (e.g., trade wars, energy crises) could further destabilize asset prices.
Q: How does household net worth 2024 affect political debates?
It’s shaping the 2024 election in three key ways:
- Tax policy: Candidates are split on whether to raise capital gains taxes (which would hit stock-heavy household net worth 2024 holders) or expand deductions for homeowners.
- Student debt: Loan forgiveness is a litmus test for young voters, while debt relief proposals are being framed as household net worth 2024 boosters.
- Housing: Zoning reforms and first-time buyer incentives are gaining traction as parties vie to appeal to swing-state demographics.
Q: Are there alternative ways to measure household net worth 2024 beyond traditional assets?
Yes. Some economists track adjustable net worth, which includes human capital (skills, education) and social capital (networks, community ties). Others focus on liquid net worth (cash, stocks, bonds) to assess financial resilience. For gig workers, portfolio income potential (e.g., side hustle earnings, digital assets) is increasingly relevant. The shift reflects a reality where household net worth 2024 is no longer just about what you own—but what you can create or access.
