Common Myths About Hong Kong Average Net Worth
The narrative around Hong Kong average net worth is littered with oversimplifications. One persistent myth is that the city’s wealth is uniformly distributed, a claim reinforced by headlines touting high GDP figures. In reality, wealth concentration in Hong Kong is among the most extreme in the developed world. The top 10% of households hold roughly 60% of the city’s total wealth, according to estimates from the Hong Kong Institute of Economics and Business Strategy. This disparity is not just a statistical footnote; it shapes everything from political discourse to social mobility. The Hong Kong average net worth masks this reality because it includes outliers—billionaire tycoons and offshore investors—whose wealth inflates the mean while leaving the median stagnant. Another misconception is that high property prices automatically translate to high net worth for all. While homeownership is often seen as a path to wealth accumulation, the city’s property market operates as a zero-sum game. Rising prices benefit existing owners but price out younger generations, creating a wealth gap between those who inherited property and those who must rent. For first-time buyers, the Hong Kong average net worth becomes a moving target, as savings are devoured by down payments and mortgage costs. Even for those who eventually own, the lack of affordable housing means that wealth is often tied to location rather than liquidity. This dynamic is further complicated by the city’s high cost of living, where even middle-class households may appear financially secure on paper but struggle with day-to-day expenses. A third myth is that financial literacy or education levels directly correlate with higher net worth. While Hong Kong ranks well in global financial literacy surveys, the city’s wealth inequality suggests that knowledge alone does not bridge systemic barriers. The Hong Kong average net worth is influenced more by access to capital—whether through inheritance, property ownership, or corporate ties—than by individual financial acumen. For example, young professionals may score highly on financial literacy tests but still find themselves priced out of the property market, leaving their net worth stagnant despite their knowledge.Myth 1: Hong Kong’s wealth is evenly distributed
The idea that Hong Kong’s prosperity is shared equally is a relic of outdated economic narratives. Data from the Hong Kong Census and Statistics Department shows that the top 1% of households control nearly 30% of the city’s total wealth, a figure that aligns with global trends in wealth concentration. This is not a recent phenomenon but a structural outcome of policies that favor asset accumulation over income redistribution. For instance, the city’s lack of capital gains tax means that property values can skyrocket without directly benefiting public services or social welfare programs. The Hong Kong average net worth thus becomes a misleading average when the median—where half the population falls below—is closer to figures seen in developed economies with far less wealth disparity. The reality is that wealth in Hong Kong is inherited as much as it is earned. A study by the Hong Kong University’s Institute of Economics found that intergenerational wealth transfer accounts for nearly 40% of the city’s wealth accumulation. This means that for many, financial security is not a product of individual effort but of family resources. The Hong Kong average net worth obscures this by including both self-made fortunes and inherited wealth in the same statistic. Without policies addressing this inheritance gap, the city’s wealth inequality will persist, regardless of economic growth.Myth 2: Property ownership guarantees financial security
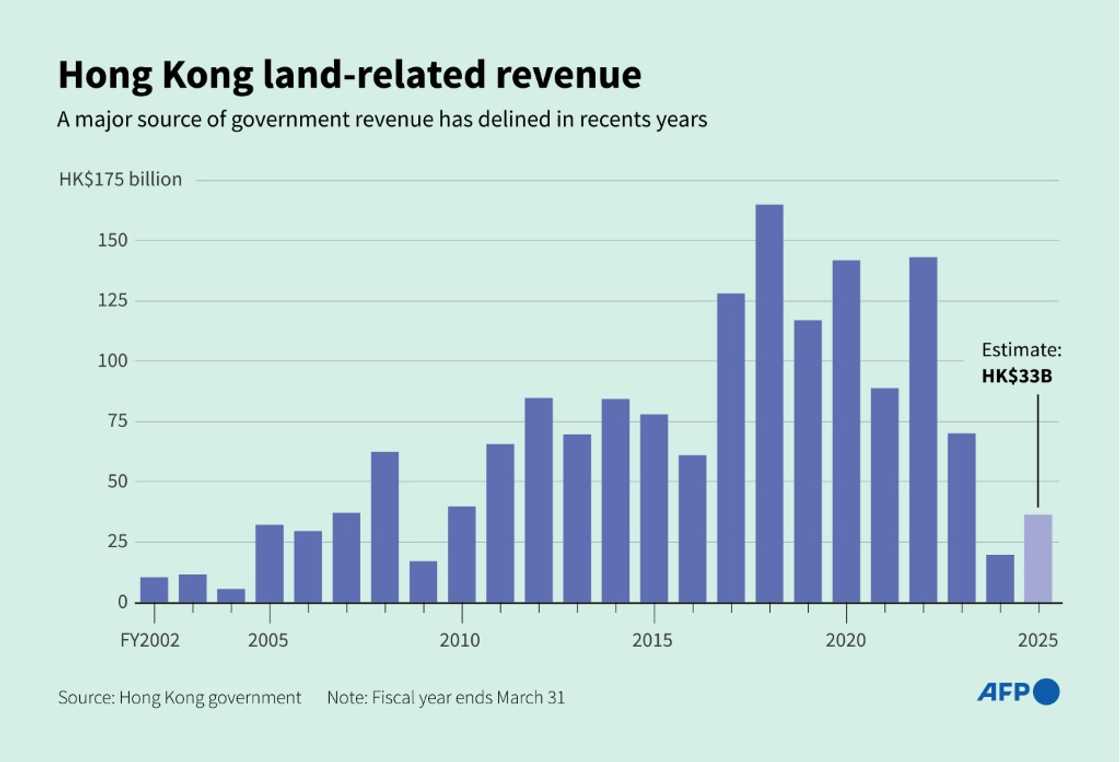
The assumption that owning a home in Hong Kong equates to financial stability ignores the city’s unique housing market dynamics. While property is often the largest component of a household’s net worth, it is also the most illiquid asset in an economy where prices are volatile and tied to global capital flows. During the 2008 financial crisis and the COVID-19 pandemic, property values in Hong Kong dropped sharply, eroding the net worth of owners overnight. For those who rely solely on their home’s value for retirement planning, this volatility becomes a risk rather than a safety net. The Hong Kong average net worth is thus inflated by property values that can fluctuate wildly, leaving owners exposed to market downturns. Moreover, the city’s housing shortage means that even those who own may face financial strain. With nearly 70% of Hong Kong’s land designated as green belts or reserved for public housing, private developers have limited space to build, driving up prices. This creates a paradox: homeowners may have high net worth on paper, but their ability to leverage that wealth—whether for business opportunities or emergencies—is constrained by the lack of affordable alternatives. For renters, the Hong Kong average net worth is a distant concept, as their financial health depends on income rather than asset appreciation.Myth 3: High net worth means high quality of life
Wealth in Hong Kong does not always translate to well-being. The city’s high cost of living—ranked among the most expensive in the world—means that even households with substantial net worth may struggle with affordability. For example, a family with a net worth in the top 20% might still face financial stress due to exorbitant education costs, healthcare expenses, or the pressure to maintain a certain lifestyle. The Hong Kong average net worth does not account for these liabilities, which can drain liquid assets even as property values rise. Additionally, the city’s lack of social safety nets means that wealth does not always insulate individuals from economic shocks, such as job losses or medical emergencies. Psychologically, the pressure to maintain a high net worth can also take a toll. In a city where status is often tied to property ownership and brand-name consumption, financial insecurity can persist even among the wealthy. The Hong Kong average net worth is a static figure, but the anxiety of maintaining it is a daily reality for many. This paradox is evident in surveys showing that despite high net worth, residents report lower life satisfaction compared to peers in cities with more equitable wealth distribution.What Holds Up to Scrutiny
When examining the Hong Kong average net worth, the most reliable data comes from official sources like the Hong Kong Census and Statistics Department, as well as independent studies from universities such as HKU and CityU. These reports consistently show that while the overall net worth per adult may appear robust—figures around the HK$5 million range have been suggested—median net worth is significantly lower, often below HK$2 million. This discrepancy highlights the importance of distinguishing between mean and median in discussions about wealth. The median provides a clearer picture of the typical household’s financial health, whereas the mean is skewed by ultra-high-net-worth individuals. Property remains the dominant factor in Hong Kong’s wealth equation. According to the Hong Kong Mortgage Corporation, residential property accounts for nearly 60% of household wealth, a figure that underscores the city’s reliance on real estate as a wealth accumulator. However, this concentration also makes the Hong Kong average net worth highly sensitive to market fluctuations. For instance, during the 2018 property downturn, net worth figures dropped by nearly 10% as home values declined. This volatility is a double-edged sword: while property ownership can rapidly increase net worth during bull markets, it can just as quickly erode it during downturns."Wealth in Hong Kong is not just about money; it’s about access. The city’s financial system rewards those who already have a foothold, whether through property, education, or family connections. The average net worth figures we see are less about individual success and more about systemic advantages." — Dr. Alice Chan, Associate Professor of Economics, HKU
| Common Belief | What the Evidence Says |
|---|---|
| Hong Kong’s wealth is evenly distributed. | The top 10% hold ~60% of total wealth; median net worth is far lower than the average. |
| Owning property guarantees financial security. | Property is illiquid and volatile; renters have no net worth tied to housing. |
| High net worth equals high quality of life. | Cost of living erodes wealth; social safety nets are minimal, increasing stress. |
Why the Confusion Persists
The persistence of myths around Hong Kong average net worth stems from the city’s dual identity as a global financial hub and a high-cost living space. International reports often aggregate Hong Kong’s data with other Asian economies, obscuring its unique challenges. For example, comparisons with Singapore or Shanghai can be misleading because Hong Kong’s wealth is more concentrated in property and offshore assets, which behave differently in economic downturns. Additionally, the city’s lack of transparency in wealth reporting—due to its status as a tax haven—makes it difficult to separate speculative estimates from verified data. Locally, the confusion is fueled by cultural narratives that glorify wealth accumulation without addressing its distribution. The Hong Kong average net worth is frequently discussed in the context of individual achievement, rather than structural inequalities. This narrative is reinforced by media coverage that highlights billionaire success stories while downplaying the struggles of the middle class. Without a robust public discourse on wealth redistribution or housing reform, the myths persist, and the gap between perception and reality widens.
Conclusion
The Hong Kong average net worth is more than a statistical footnote; it is a reflection of the city’s economic contradictions. While Hong Kong’s financial sector drives global capital flows, its domestic wealth distribution tells a different story—one of concentration, volatility, and systemic barriers. The data shows that property ownership remains the primary driver of net worth, but this asset class is also the most precarious, subject to market whims and policy decisions. For the majority of residents, financial security is not a given but a precarious balance between income, debt, and liquidity. Moving forward, the conversation around Hong Kong average net worth must shift from celebration of high figures to an examination of equity. Policies addressing housing affordability, inheritance taxation, and social safety nets could reshape the city’s wealth landscape. Until then, the Hong Kong average net worth will remain a double-edged sword: a testament to economic success for some, and a reminder of inequality for others.Comprehensive FAQs
Q: How is the Hong Kong average net worth calculated?
The Hong Kong average net worth is typically derived from household surveys conducted by the Census and Statistics Department, which assess assets (property, investments, cash) minus liabilities (mortgages, debts). However, these figures are often aggregated with median data, which can differ significantly due to wealth concentration.
Q: Is Hong Kong’s net worth higher than mainland China’s?
On a per capita basis, Hong Kong’s average net worth tends to be higher than mainland China’s due to its financial sector and property market. However, when considering total wealth, China’s larger population means its aggregate net worth surpasses Hong Kong’s. The comparison is complex because mainland data is less transparent.
Q: Does property ownership alone determine net worth in Hong Kong?
While property constitutes the bulk of household wealth, net worth also includes investments, cash reserves, and liabilities. For renters, net worth is primarily liquid assets, making the Hong Kong average net worth a misleading benchmark for their financial health.
Q: How does wealth inequality affect the average net worth?
Extreme wealth inequality inflates the Hong Kong average net worth because it includes ultra-high-net-worth individuals. The median net worth—where half the population falls below—is far lower, often less than half the average, highlighting the disparity.
Q: Are there government policies to address wealth inequality?
Hong Kong’s government has implemented limited measures, such as the Home Ownership Scheme for first-time buyers and tax incentives for property developers. However, critics argue these policies favor asset appreciation over income redistribution, leaving wealth inequality largely unaddressed.
Q: How does the Hong Kong average net worth compare to other Asian cities?
Hong Kong’s average net worth is competitive with Singapore and Tokyo but lags behind cities like Zurich or New York due to its smaller economy. However, its wealth concentration is more extreme, with a higher Gini coefficient than most developed nations.
Q: Can young professionals in Hong Kong achieve a high net worth?
Achieving a high net worth in Hong Kong is challenging for young professionals due to high property costs and stagnant wages. Many rely on inheritance or family support to bridge the gap, making intergenerational wealth transfer a critical factor in financial success.
Q: What are the biggest risks to Hong Kong’s net worth stability?
The primary risks include property market downturns, political instability, and global economic shocks. Given Hong Kong’s reliance on real estate, a correction could significantly reduce household net worth, as seen during the 2008 crisis and 2019 protests.
