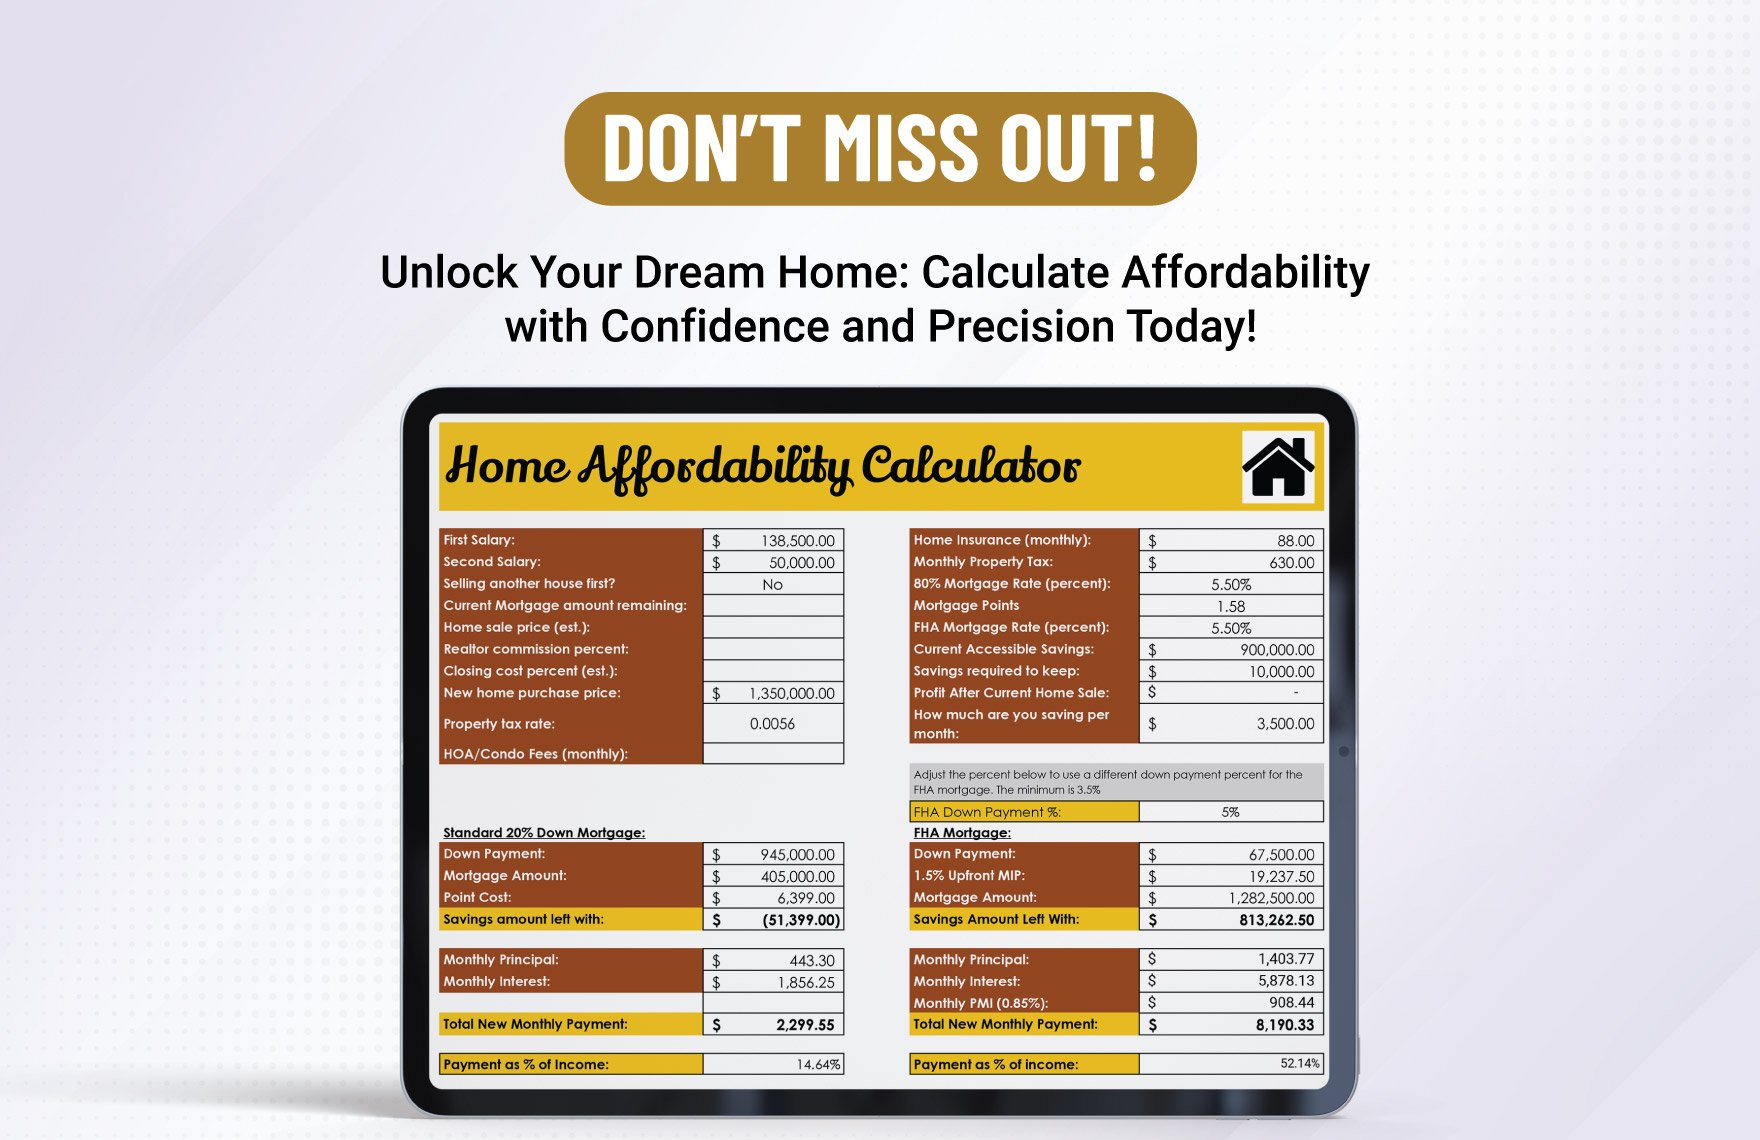
5 Things Worth Knowing About Home Affordability Calculator Net Worth
The relationship between a home affordability calculator and net worth is more nuanced than most realize. Calculators provide a starting point, but net worth introduces variables that can shift affordability thresholds dramatically. Here’s what you need to know:1. Net Worth Multipliers Vary by Region
A home affordability calculator in Austin, Texas, will yield wildly different results than one in San Francisco or Detroit. The discrepancy isn’t just about home prices—it’s about how net worth translates into buying power. In coastal cities, where home values are inflated by investor demand, a $500,000 home might require a 20% down payment ($100,000) plus closing costs, leaving little room for error if your net worth is concentrated in illiquid assets like a 401(k). Conversely, in Rust Belt markets, the same $500,000 home could be within reach with a 10% down payment if your net worth includes high-liquidity savings or a stable income stream. The catch? Home affordability calculator net worth interactions are skewed by regional tax burdens. In states with high property taxes (like New Jersey or Illinois), a $600,000 home might eat up 5–7% of your gross income annually—far more than the calculator’s debt-to-income ratio suggests. Your net worth must absorb not just the mortgage but the hidden costs of ownership. Pre-tax income alone won’t cut it; after-tax cash flow and asset liquidity become decisive.2. Debt Leverage Distorts Affordability Perceptions
Most home affordability calculators treat debt as a static line item, but in reality, your net worth is a moving target. Student loans, credit card debt, or a second mortgage can inflate your debt-to-income ratio while simultaneously reducing your liquid net worth. For example, a buyer with $80,000 in student loans might qualify for a $350,000 mortgage based on their $120,000 salary, but their net worth—after setting aside emergency funds—could be too thin to handle a 3% interest rate hike. The calculator doesn’t account for the opportunity cost: the lost investment returns from tying up cash in a down payment versus keeping it liquid. This is where home affordability calculator net worth misalignment becomes dangerous. Lenders focus on income; your net worth must consider the risk of that income disappearing. A freelancer with a six-figure net worth but irregular cash flow might be approved for a $700,000 loan, only to face foreclosure if a single client contract falls through. The calculator doesn’t model black swan events—your net worth must.3. Down Payment Strategies Can Amplify or Mask Affordability
The down payment is where net worth and affordability collide. A 20% down payment reduces private mortgage insurance (PMI) and improves loan terms, but it also locks up a chunk of your net worth in a single asset. For a $450,000 home, that’s $90,000 tied up—money that could otherwise fund retirement, education, or business ventures. Calculators often suggest down payment assistance programs, but these may come with strings (e.g., seller concessions, higher interest rates). Your net worth must factor in whether the long-term savings from PMI avoidance outweigh the opportunity cost of illiquid capital. Here’s the paradox: Home affordability calculator net worth analysis shows that smaller down payments (e.g., 3–5%) can make homeownership accessible, but they also expose you to negative equity risks. In 2008, buyers with low down payments saw home values plummet by 30% in some markets—erasing years of wealth-building. Your net worth isn’t just about the numbers on paper; it’s about whether you can survive a market correction without selling at a loss.4. Retirement Accounts and Home Equity Are Not Equal
A common mistake is treating home equity as a retirement asset. While home equity can be leveraged via reverse mortgages or HELOCs, it’s not liquid like a 401(k) or IRA. Calculators rarely distinguish between these asset classes, yet the rules governing them couldn’t be more different. Withdrawing from a retirement account triggers taxes and penalties; tapping home equity often requires refinancing, which resets your mortgage term and increases long-term costs. Consider this: A 65-year-old with a $1 million net worth—$800,000 in home equity and $200,000 in retirement savings—might assume they can afford a $1.2 million home. But if they take a HELOC for the down payment, they’re now on the hook for two mortgages: the original loan and the new HELOC debt. The calculator doesn’t show the compounding interest or the risk of outliving the home’s value. Home affordability calculator net worth must account for asset liquidity, not just balance sheet totals.5. The "Affordable" Home May Not Align With Your Goals
Calculators are designed to maximize borrowing capacity, not life satisfaction. A $300,000 home might fit your budget, but if it’s in a neighborhood with poor schools or high crime, the true cost of ownership includes stress, resale depreciation, and potential safety risks. Conversely, a $500,000 home in a walkable city could save you $20,000 annually in commuting and dining costs—offsetting the higher price tag. Your net worth isn’t just a number; it’s a tool for achieving lifestyle objectives. The disconnect here is that home affordability calculator net worth often ignores non-financial trade-offs. A young couple might qualify for a $400,000 home but realize they’d rather spend $300,000 on a smaller place to have more cash flow for travel or childcare. The calculator doesn’t weigh these priorities—your net worth must.
How These Facts Connect
The five points above reveal a fundamental truth: a home affordability calculator is a starting point, not a verdict. Net worth introduces dimensions that calculators can’t quantify—liquidity, regional tax impacts, debt leverage, and lifestyle alignment. The most dangerous assumption is that because a calculator says you can afford a home, you should buy it. In reality, the calculator’s output is a function of your net worth’s resilience to unseen variables: job loss, medical emergencies, or market downturns. The table below compares how these factors interact across different financial profiles:| Factor | Young Professional (Net Worth: $150K) | Mid-Career Family (Net Worth: $500K) | Retiree (Net Worth: $2M) |
|---|---|---|---|
| Debt Leverage | Student loans reduce liquidity; calculator overestimates affordability. | Mortgage + college savings strain cash flow; net worth buffers risk. | Low debt but high property taxes eat into fixed income. |
| Down Payment Strategy | 3–5% down risks negative equity; net worth lacks emergency cushion. | 20% down avoids PMI but ties up capital; opportunity cost of illiquidity. | HELOC for down payment creates dual mortgage burden. |
| Regional Taxes | High state taxes in coastal cities reduce take-home pay. | School districts and local taxes vary widely; net worth must absorb hidden costs. | Property taxes in high-tax states can exceed 3% of home value annually. |
| Asset Liquidity | 401(k) withdrawals trigger penalties; home equity is illiquid. | Balanced portfolio allows flexibility; home equity is a last resort. | Reverse mortgages deplete home equity; retirement savings remain untouched. |
| Lifestyle Trade-Offs | Smaller home frees cash for experiences; calculator ignores non-financial costs. | Larger home may reduce commuting costs; net worth must prioritize. | Downtown condo vs. suburban home: maintenance vs. walkability trade-offs. |
Conclusion
The gap between what a home affordability calculator suggests and what your net worth can sustain is where most buyers make irreversible mistakes. Calculators are tools, not oracles; they don’t account for the human element—career instability, health shocks, or shifting priorities. Your net worth is the lens through which you should evaluate affordability, not the other way around. Start by running the calculator, but don’t stop there. Stress-test your net worth against three scenarios: a 20% market downturn, a 5% interest rate spike, and a 12-month unemployment period. If your net worth holds, you’re likely in a strong position. If not, the calculator’s output is a red herring. The goal isn’t to buy the most house you can afford—it’s to buy a home that aligns with your net worth’s ability to protect and grow over time.Comprehensive FAQs
Q: How does a home affordability calculator differ from a net worth analysis?
A: A home affordability calculator focuses on income, debt, and loan eligibility, while a net worth analysis evaluates your total assets minus liabilities. The calculator ignores liquidity, regional tax impacts, and opportunity costs—factors that net worth analysis addresses. For example, a calculator might approve you for a $400,000 mortgage, but your net worth could be too thin to handle a 3% rate hike without selling investments at a loss.
Q: Can I use retirement funds to improve my home affordability calculator results?
A: Technically, yes—but strategically, no. Withdrawing from a 401(k) or IRA to boost your down payment triggers taxes and penalties, reducing your net worth long-term. A better approach is to use a home affordability calculator net worth strategy that prioritizes liquid assets (e.g., savings accounts, brokerage funds) over retirement accounts. If you must tap retirement funds, consider a 401(k) loan (if your plan allows it) to avoid immediate tax hits.
Q: Why does my home affordability calculator give me a higher loan amount than my bank pre-approval?
A: Calculators often use optimistic assumptions (e.g., no PMI, fixed rates, or best-case debt ratios), while pre-approvals factor in credit score, employment history, and lender overlays. For instance, a calculator might assume a 7% interest rate, but your pre-approval could reflect the current 7.5% rate—reducing your actual borrowing power. Always compare the calculator’s output to your pre-approval’s terms, not just the loan amount.
Q: How do property taxes affect my home affordability calculator net worth?
A: Property taxes are a silent affordability killer. In high-tax states (e.g., New Jersey, Illinois), annual taxes on a $500,000 home can exceed $10,000—equivalent to an extra $833/month. Calculators rarely include this in their debt-to-income ratios, but your net worth must account for it. Run a home affordability calculator net worth scenario with your local tax rate to see the true cost of ownership.
Q: Is it better to have a higher net worth or a higher income for home affordability?
A: Net worth matters more than income for long-term affordability. A high income without assets (e.g., a freelancer with $200K/year but $50K in savings) may qualify for a large mortgage but lacks a buffer for emergencies. Conversely, a moderate income with a $1M net worth (e.g., a retiree with a pension and investments) can afford a home without stretching. Home affordability calculator net worth prioritizes the latter—assets over income—because they provide resilience.
Q: What’s the biggest mistake people make when relying on a home affordability calculator?
A: Assuming the calculator’s output is the same as real-world affordability. Many buyers ignore: 1. Hidden costs (HOA fees, maintenance, insurance). 2. Opportunity costs (tying up cash in a down payment vs. investing). 3. Market risks (negative equity, job loss). A calculator doesn’t simulate these—your net worth analysis must.
Q: How often should I update my home affordability calculator net worth analysis?
A: At least annually, or whenever: - Your income or debt changes (e.g., new job, student loan repayment). - Interest rates shift by 0.5% or more. - Your net worth grows/shrinks by 10%+ (e.g., stock market swings, inheritance). - You’re considering a move to a new state (tax laws vary wildly). A static analysis is obsolete within 12–18 months.
