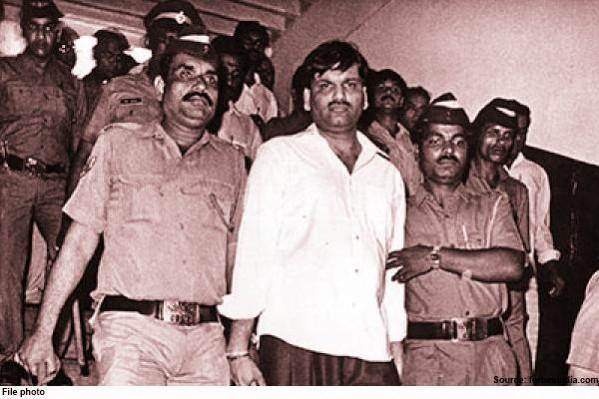
The Short Answers
- Harshad Mehta’s net worth at its peak (pre-scandal) is estimated to have exceeded ₹1,000 crore (around $250 million at the time), though exact figures remain disputed due to the fraudulent nature of his wealth.
- After his conviction in 2001, his assets were seized, and his remaining Harshad Mehta net worth was reportedly liquidated to settle debts, leaving his family with minimal financial standing.
- The 1992 scam involved fake bank guarantees worth over ₹4,000 crore, artificially inflating stock prices and his personal fortune before the crash.
- Mehta’s trading empire collapsed due to a banking system failure—when the Reserve Bank of India froze his accounts, triggering a market panic and exposing the fraud.
Deep Dive: The Full Picture
Harshad Mehta’s net worth wasn’t built through traditional investing; it was a construct of leverage, deception, and institutional collusion. By the early 1990s, he had positioned himself as a market hero, using a network of cooperating banks to issue fake "bank guarantees" that served as collateral for his stock purchases. These guarantees—worth billions—were never verified, yet they allowed him to borrow heavily, driving up share prices in a self-reinforcing cycle. His Harshad Mehta net worth ballooned as he traded in futures, options, and even government securities, all while maintaining a public image of infallibility. The system only worked as long as the banks kept issuing guarantees and the market kept rising. When the Reserve Bank of India finally intervened in April 1992, freezing his accounts, the illusion shattered. Overnight, his Harshad Mehta net worth—which had been inflated by the very institutions meant to regulate him—evaporated. The scandal revealed a net worth that was never real: a house of cards built on forged documents, complicit bankers, and a stock market primed for manipulation.The Context You Need
India’s financial sector in the late 1980s and early 1990s was in transition. The government had just liberalized foreign investment, and the stock market was booming, but oversight was lax. Mehta exploited this environment, using a tactic called "ready forward deals"—where he borrowed money against fake bank guarantees to buy stocks, then sold them forward to other investors. This created the illusion of liquidity and demand, artificially inflating prices. His Harshad Mehta net worth grew not from profits but from the ability to keep the cycle going, with banks turning a blind eye to the lack of collateral. The scandal’s scale became apparent only after the crash. Investigations later uncovered that over ₹4,000 crore in fake guarantees had been issued by banks, including names like the Bank of Baroda and the Punjab National Bank. These figures dwarfed the Harshad Mehta net worth he had publicly flaunted, proving that his fortune was a mirage. The collapse didn’t just wipe out his personal wealth—it triggered a market crash, leading to the Securities and Exchange Board of India (SEBI) overhauling regulations to prevent such frauds in the future.The Mechanics
Mehta’s operation relied on three key pillars: fake bank guarantees, insider information, and a compliant banking system. The guarantees were the linchpin. By forging documents, he convinced banks to issue letters of undertaking (LOUs) that appeared legitimate, allowing him to borrow against non-existent funds. This enabled him to buy stocks on margin, then sell them at inflated prices to other investors—who, in turn, were often his own associates or shell companies. The Harshad Mehta net worth thus became a byproduct of this circular fraud, where the only real money was the interest he paid on the borrowed funds. The second layer was his control over information. Mehta had access to advance knowledge of corporate actions, government policies, and even bank inspections—leaks that allowed him to time his trades perfectly. When the market moved in his favor, his Harshad Mehta net worth surged; when it didn’t, he used his network to manipulate prices. The final piece was the banking system’s complicity. Multiple bank officials were later convicted for issuing guarantees without due diligence, knowing full well that the collateral didn’t exist. Their roles ensured that his Harshad Mehta net worth could expand unchecked, at least until the system failed.Details That Change the Picture
The Harshad Mehta net worth at its zenith was less about personal wealth and more about systemic exploitation. While he owned luxury properties, a fleet of cars, and even a private jet, these were financed through the same fraudulent structure that inflated his trading empire. His real power lay in his ability to control narratives—both in the market and in the media. Before the scandal, he was hailed as a visionary; after, he became a pariah. The shift underscores how Harshad Mehta net worth was never just a personal balance sheet but a reflection of broader institutional failures. One often overlooked aspect is the human cost. Thousands of small investors lost life savings in the crash, while Mehta’s associates—including bankers and brokers—faced legal consequences. His Harshad Mehta net worth after the scandal? Near zero. By the time he was convicted in 2001, his assets had been seized, and his family was left with little. The irony is that the man who had once symbolized financial prowess ended his days in obscurity, his name forever tied to one of India’s greatest financial crimes."Mehta didn’t just break the rules; he exposed how easily they could be bent when greed met opportunity." — R. N. Malhotra, former RBI governor and key figure in the scandal’s investigation.
| Key Figure | Role in the Scandal |
|---|---|
| Harshad Mehta | Mastermind; used fake guarantees to inflate Harshad Mehta net worth and manipulate markets. |
| Bank of Baroda | Issued ₹1,500 crore in fake guarantees; later fined and penalized. |
| Reserve Bank of India (RBI) | Delayed intervention; freezing Mehta’s accounts in 1992 triggered the crash. |
| SEBI (Securities Exchange Board of India) | Post-scandal, introduced stricter regulations to prevent similar frauds. |

Conclusion
The story of Harshad Mehta net worth is a study in how financial systems can be gamed when oversight is weak. His case didn’t just reveal the extent of his personal greed; it laid bare the vulnerabilities in India’s banking and securities framework. The scandal forced a reckoning, leading to reforms that still shape the market today. Yet the question of what his Harshad Mehta net worth could have been—had the system not collapsed—remains a haunting "what if" in financial history. Mehta’s legacy is a reminder that wealth built on deception is always temporary. While his name is now synonymous with fraud, his methods exposed flaws that persist in modern markets. The Harshad Mehta net worth debate isn’t just about numbers; it’s about the ethics of finance, the cost of unchecked ambition, and the lessons learned from one of India’s most audacious scams.Comprehensive FAQs
Q: How did Harshad Mehta inflate his net worth?
Mehta used fake bank guarantees to borrow heavily against non-existent collateral. These guarantees—issued by complicit banks—allowed him to buy stocks on margin, artificially inflating his Harshad Mehta net worth and the market itself. The scheme collapsed when the RBI froze his accounts in 1992.
Q: What was Harshad Mehta’s net worth at his peak?
Estimates suggest his Harshad Mehta net worth exceeded ₹1,000 crore (roughly $250 million at the time), though exact figures are impossible to verify due to the fraudulent nature of his wealth. His assets were largely illusory, backed by forged documents.
Q: Did Harshad Mehta keep any of his wealth after the scandal?
No. After his conviction in 2001, his assets were seized, and his remaining Harshad Mehta net worth was liquidated to settle debts. His family reportedly received minimal compensation, and he died in 2012 with no significant personal fortune.
Q: Were any bankers or officials convicted for their role in the scam?
Yes. Multiple bank officials, including those from the Bank of Baroda and Punjab National Bank, were convicted for issuing fake guarantees. The scandal led to stricter banking regulations and the eventual resignation of key RBI officials.
Q: How did the 1992 scam affect India’s stock market?
The crash triggered by Mehta’s downfall wiped out ₹4,000 crore in investor wealth and led to a market slump. The scandal prompted SEBI to introduce stricter disclosure norms, margin requirements, and surveillance systems to prevent similar frauds.
Q: Is there any truth to claims that Harshad Mehta’s family still benefits from his wealth?
There is no verified evidence that his family retained significant assets. Post-scandal, his legal troubles and asset seizures left them with minimal financial standing. Any lingering claims are speculative.
Q: Could a similar scam happen today?
While regulations have tightened, experts argue that advanced fraud techniques—such as synthetic collateral or AI-driven manipulation—could still exploit loopholes. The Harshad Mehta net worth case remains a cautionary tale about systemic risks in financial markets.
