The Complete Overview of Google’s Financial Dominance
Alphabet’s financial reports read like a manifesto of modern capitalism: search ads as the cash cow, YouTube as the content engine, and Google Cloud as the growth play. The company’s Google net worth analysis must account for three layers: public-facing revenue streams, private investments (like Waymo or DeepMind), and intangible assets like brand equity. In 2023, Alphabet’s annual revenue topped $300 billion, with Google Search and Ads contributing roughly 60% of total income. This isn’t just a business—it’s a monetization platform for the internet itself. The catch? Google’s valuation isn’t linear. While its core ad business grows incrementally, AI and cloud represent exponential bets. Google Cloud’s revenue has surged from $1 billion in 2013 to over $30 billion annually, but it remains a distant third behind AWS and Azure. Meanwhile, AI investments—like Vertex AI and Gemini—are designed to flip the script: instead of selling ads, Google will sell predictive infrastructure. The tension between legacy cash flows and futuristic gambles defines Alphabet’s net worth volatility.Historical Background and Evolution
Google’s financial ascent began with a search monopoly that predates the term "Big Tech." Founders Larry Page and Sergey Brin recognized early that user attention was the ultimate currency. By 2004, Google’s IPO valued the company at $23 billion—a fraction of today’s Google net worth analysis benchmarks. The real inflection point came with mobile dominance: Android’s 2008 launch and Chrome’s adoption turned Google into a two-sided marketplace, where users and advertisers became interchangeable revenue drivers. The 2015 restructuring into Alphabet was less about financial engineering and more about psychological signaling. By separating Google’s core from experimental ventures (like Verily or Wing), the company created a valuation shield. Investors could now parse risk: Google’s ad business was "safe," while "Other Bets" could fail without dragging the entire enterprise down. This strategy paid off when Google Cloud and AI began delivering outsized returns, proving that Alphabet’s net worth growth wasn’t just about ads—it was about redefining infrastructure.Core Mechanisms: How It Works
At its core, Google’s financial model operates on three pillars: 1. Data arbitrage—extracting value from user behavior without direct payment. 2. Platform lock-in—Android, Chrome, and Search create switching costs that trap users. 3. Vertical integration—from hardware (Pixel, Nest) to software (TensorFlow), Google controls the entire AI pipeline. The Google net worth analysis must dissect how these pillars interact. For example, Android’s dominance (70%+ global market share) ensures Google’s ad network reaches billions. Meanwhile, Chrome’s market share (65%+) guarantees that ads are served in the most efficient auction environment. Even "loss leaders" like Google Fiber or Stadia serve a purpose: they train AI models that later power ad targeting. The system is self-optimizing. The dark side? Regulatory risk. Antitrust cases in the EU and U.S. could force Google to unbundle these assets, directly impacting its net worth stability. A forced divestiture of Android or ad tech could slash margins overnight. Yet Google’s legal team has mastered the art of delay tactics, buying time for moats to deepen further.Key Benefits and Crucial Impact
Google’s financial model isn’t just profitable—it’s structurally advantageous. While competitors like Meta or Amazon rely on direct transactions, Google profits from indirect value extraction. Its net worth isn’t just a reflection of revenue; it’s a measure of global digital dependency. Governments, businesses, and individuals all rely on Google’s infrastructure, creating a feedback loop of necessity. The implications are profound. When Google raises prices for cloud services or ad inventory, clients have little choice but to comply. This pricing power is the ultimate financial moat. Even during economic downturns, Google’s ad revenue resilience stems from its ability to shift spend from offline to online—a dynamic it helped engineer."Google doesn’t just sell ads; it sells the infrastructure that makes ads inevitable." — Ben Thompson, Stratechery
Major Advantages
- Search dominance: 90%+ market share in global search ensures recurring revenue from advertisers.
- Data network effects: More users → better ads → higher valuations for AI assets.
- Cloud cost leadership: Google Cloud’s $30B+ revenue is growing at 30%+ annually, outpacing AWS.
- AI first-mover advantage: TensorFlow and Vertex AI give Google control over future infrastructure layers.
- Regulatory arbitrage: Google operates in jurisdictions with lighter antitrust enforcement (e.g., U.S. vs. EU).

Comparative Analysis
| Metric | Google (Alphabet) | Microsoft | Meta |
|---|---|---|---|
| Primary Revenue Driver | Search/Advertising (60%+) | Cloud/Enterprise (50%+) | Social Ads (98%) |
| Net Margin (2023) | 20-25% | 35-40% | 30-35% |
| AI/Cloud Growth Rate | 30%+ (Google Cloud) | 25%+ (Azure) | Minimal (focus on Meta AI) |
| Regulatory Risk | High (antitrust cases) | Moderate (lobbying success) | Low (social media focus) |
Future Trends and Innovations
Google’s next decade hinges on AI monetization. While today’s Google net worth analysis celebrates ad revenue, tomorrow’s will pivot to predictive infrastructure. Projects like Gemini and AI-driven ad personalization suggest a future where Google doesn’t just sell ads—it sells outcomes. If successful, this shift could double Alphabet’s valuation by 2030. The wild card? Regulation. If governments force Google to open its data troves or limit ad targeting, its net worth growth could stall. Yet Google’s legal playbook—acquiring rivals before they scale (e.g., Mandatory View, AdSense competitors)—has historically neutralized threats. The bigger risk is internal. Can Google Cloud compete with AWS/Azure without cannibalizing Google’s ad business? The answer will define whether Alphabet’s net worth trajectory remains exponential or plateaus.
Conclusion
Google’s financial empire isn’t built on a single innovation—it’s the result of decades of ecosystem control. From search to AI, every move reinforces its net worth dominance. Yet the company’s greatest strength—data dependency—is also its Achilles’ heel. As regulators and competitors circle, Google’s ability to reinvent its valuation drivers will determine whether it remains untouchable or becomes another cautionary tale. The lesson? Google’s net worth analysis isn’t just about numbers—it’s about power. And in the digital age, power isn’t measured in dollars alone. It’s measured in attention, infrastructure, and the ability to predict human behavior before it happens.Comprehensive FAQs
Q: How does Google’s net worth compare to other Big Tech firms?
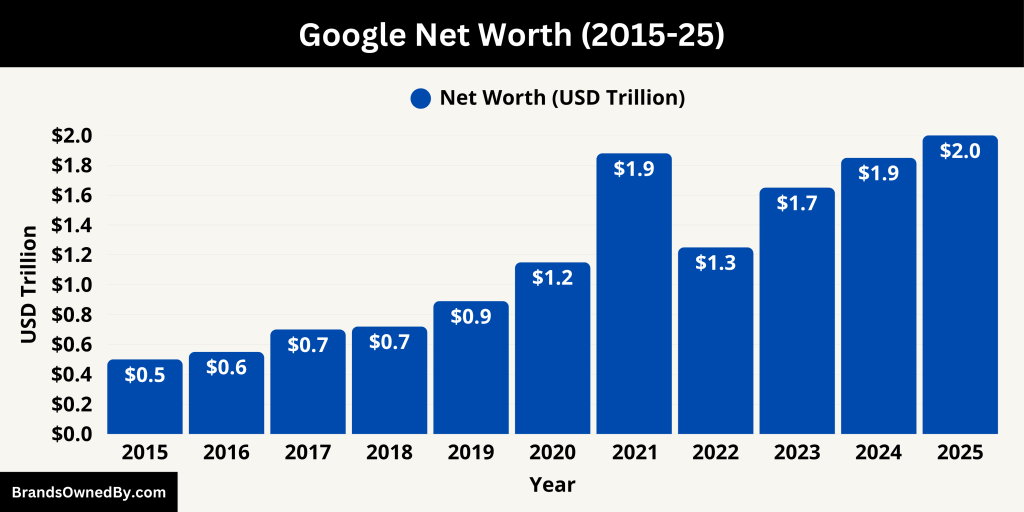
As of 2024, Alphabet’s market cap fluctuates between $1.4 trillion and $1.8 trillion, positioning it behind Microsoft (~$2.5T) but ahead of Meta (~$1T). The key difference is revenue diversity: Google’s ad-heavy model is more volatile than Microsoft’s cloud/enterprise mix.
Q: What percentage of Google’s revenue comes from ads?
Approximately 60-65% of Alphabet’s total revenue is generated by Google Search, YouTube, and Display Network ads. This dominance makes ad performance the primary driver in any Google net worth analysis.
Q: How does Google Cloud’s growth affect Alphabet’s valuation?
Google Cloud’s 30%+ annual growth is critical for long-term net worth expansion, but it remains a small fraction (~10%) of total revenue. Analysts watch closely for profitability improvements, as losses in cloud historically dragged margins down.
Q: Are there risks to Google’s financial model?
Yes. Regulatory actions (e.g., forced divestitures), ad fraud, and AI disruption (if competitors like Microsoft or Amazon build superior infrastructure) could erode its net worth stability. Dependence on a few advertisers (e.g., Amazon, Walmart) also introduces concentration risk.
Q: How does Android contribute to Google’s net worth?
Android’s 70%+ market share ensures Google’s ad network reaches billions of devices. While Android itself isn’t profitable, it fuels Google Play revenue (~$40B/year) and data collection that improves ad targeting—indirectly boosting Google’s overall valuation.
Q: What’s the biggest threat to Google’s long-term net worth?
AI competition. If Microsoft or China’s tech giants (e.g., Baidu, Tencent) build superior AI infrastructure, Google’s ad-driven revenue could face disruption. Additionally, privacy laws (e.g., GDPR, U.S. federal regulations) may limit data access, hurting targeting precision.
Q: How does Google’s stock perform during economic downturns?
Google’s stock is resilient but not immune. During recessions, ad spend drops (especially in retail/automotive), but Google’s cloud and enterprise businesses often offset losses. The 2022 downturn saw a ~20% stock decline, but recovery was swift as advertisers shifted budgets online.
Q: Can Google’s net worth grow without ads?
Unlikely in the short term. While AI and cloud are high-growth areas, they contribute <20% of revenue. A post-ad world would require Google to monetize AI directly—something it’s testing with ad-free YouTube tiers and enterprise AI tools. Success here could redefine Google’s net worth drivers entirely.
