The Complete Overview of Weapons Sales by Country
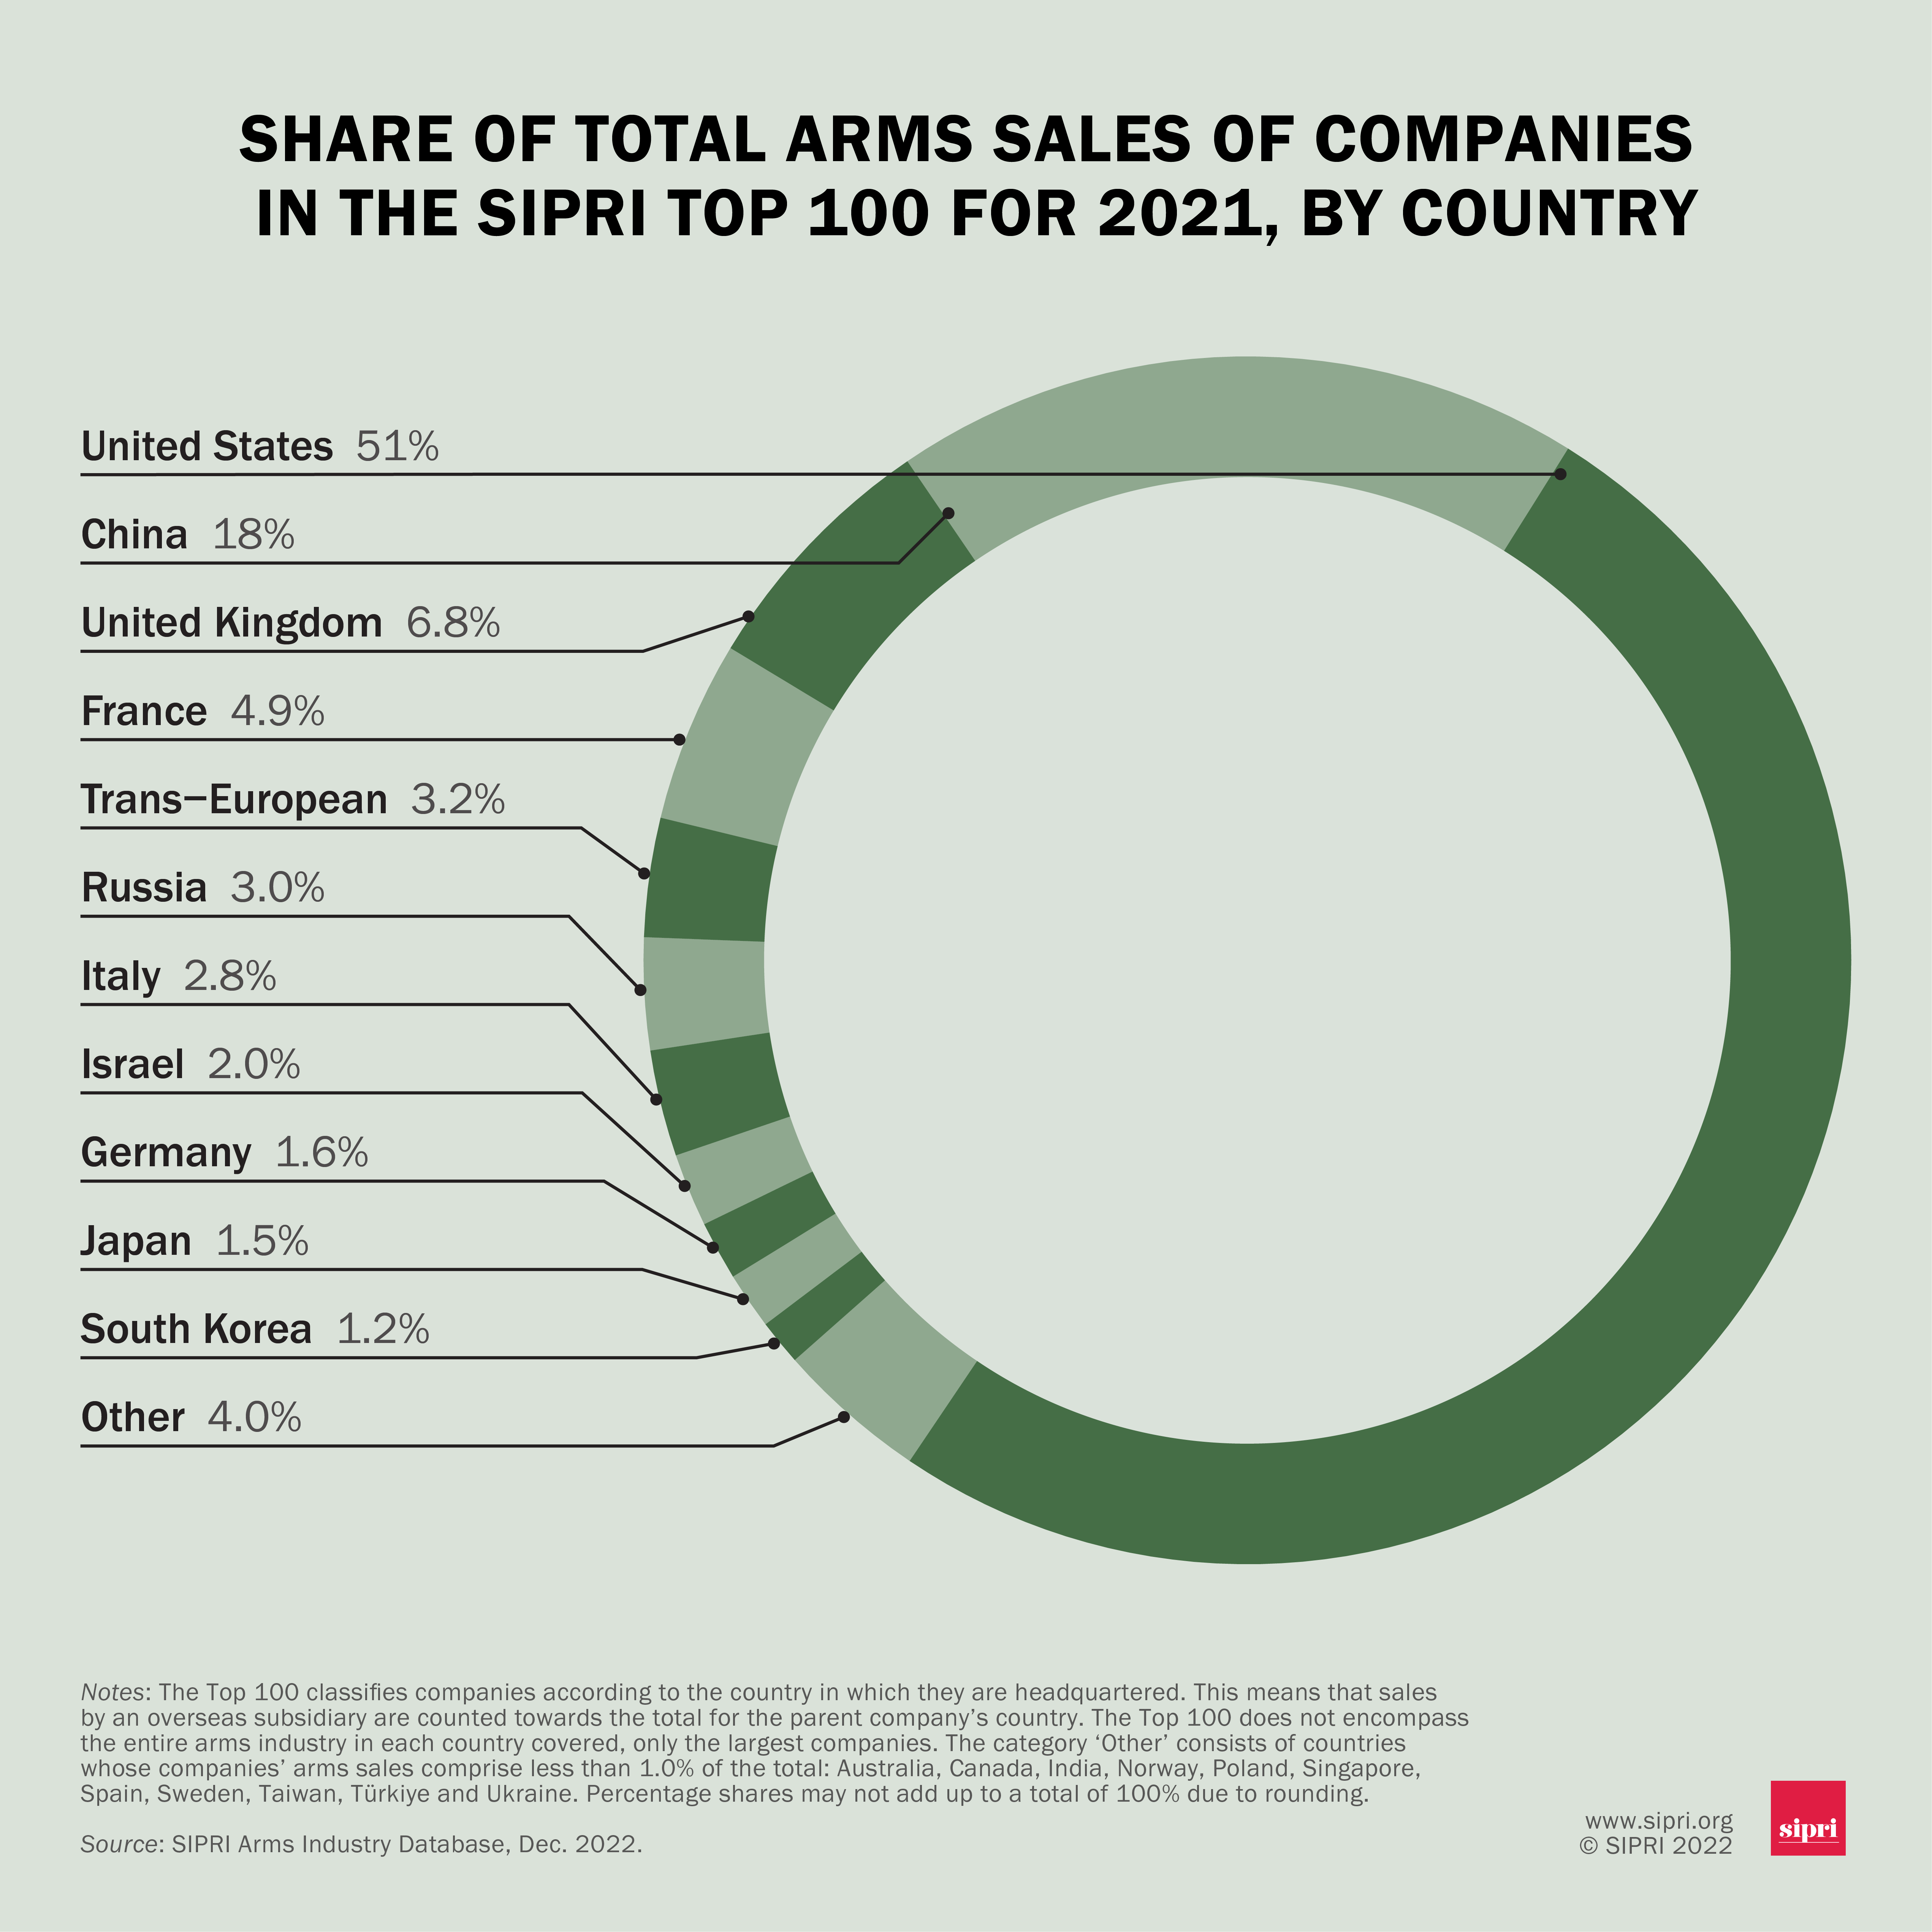
The modern arms trade emerged from the ashes of World War II, when the U.S. and Soviet Union locked in a decades-long competition to export military technology as a proxy for ideological dominance. The Cold War era saw weapons sales by country become a battleground for influence, with Washington supplying NATO allies and Moscow arming non-aligned movements. By the 1980s, the U.S. alone accounted for nearly half of global arms exports, a lead it maintains today—though China and Russia have closed the gap significantly. The end of the Cold War didn’t dismantle the system; it simply decentralized it. Regional powers like Turkey, South Korea, and Israel entered the fray, while emerging markets in the Middle East and Asia became voracious buyers. Today, the landscape is fragmented but no less competitive. The top five exporters—the U.S., Russia, France, Germany, and China—dominate, but their strategies differ sharply. The U.S. relies on long-term partnerships (e.g., F-35 sales to Japan and the UAE) and offset agreements that tie buyers to American supply chains. Russia, meanwhile, leverages its energy leverage to secure deals, while European nations like France and Germany emphasize dual-use technology with civilian applications. Meanwhile, weapons sales by country in the Global South have surged, with nations like India and Saudi Arabia becoming pivotal hubs for both imports and re-exports. The result? A market where no single player holds a monopoly, and every transaction is a calculated move in a larger game.Historical Background and Evolution
The origins of weapons sales by country as a structured industry can be traced to the 19th century, when European powers began selling rifles and artillery to colonial forces and local warlords. However, it was the post-WWII era that formalized the trade. The U.S. Foreign Military Sales (FMS) program, established in 1948, set the template for government-backed arms exports, blending commercial incentives with strategic interests. The Soviet bloc followed suit, with COMECON states supplying weapons to allies at subsidized rates—a practice that continued even after the USSR’s collapse, as Russia repurposed its military-industrial complex for civilian and export markets. The 1990s marked a turning point. The dissolution of the Soviet Union left Russia with a vast arsenal and a desperate need for revenue, leading to aggressive weapons sales by country campaigns across Africa, the Middle East, and Asia. Meanwhile, the U.S. pivoted to Asia-Pacific, signing deals with Taiwan, Japan, and Australia to counter China’s rise. The 21st century brought new dynamics: sanctions on Russia after its annexation of Crimea accelerated China’s arms exports, while Europe’s defense industry consolidated to remain competitive against American and Russian dominance. Today, the market is defined by three key trends: the rise of non-traditional exporters (e.g., Turkey’s Bayraktar drones), the digitalization of arms trade (cyber warfare tools, AI-driven targeting systems), and the growing influence of private military companies (PMCs) in gray-area operations.Core Mechanisms: How It Works
At its core, weapons sales by country operate through a mix of direct government-to-government contracts, commercial offsets, and indirect transfers via third-party brokers. The U.S. model, for instance, relies on the Defense Security Cooperation Agency (DSCA), which vets foreign requests for military hardware. Approved deals often include training programs, maintenance agreements, and technology transfers—all designed to lock buyers into long-term dependencies. Russia’s approach is more hands-off: its Rosoboronexport agency markets weapons through direct negotiations, often bundling them with energy deals or debt forgiveness to sweeten the pitch. The financing of these transactions is equally complex. Many buyers—particularly in the Global South—rely on export credit agencies (ECAs) like the U.S. Export-Import Bank or France’s COFACE, which provide low-interest loans to cover purchases. This creates a perverse incentive: nations can acquire advanced weaponry without immediate budgetary strain, only to face repayment crises later. Meanwhile, weapons sales by country in conflict zones often involve cash payments or barter arrangements, bypassing formal financial channels entirely. The result is a system where transparency is the exception, and accountability is rare.Key Benefits and Crucial Impact
For exporting nations, weapons sales by country serve as a critical tool for foreign policy. The U.S. uses arms exports to strengthen alliances, as seen with its $38 billion sale of F-16s to Taiwan in 2020—a move framed as a check against China’s aggression. For Russia, weapons sales provide hard currency and geopolitical leverage, with contracts in Syria and India helping Moscow project power despite Western sanctions. Even smaller players like Israel and South Korea benefit: their advanced drones and submarines are in high demand, allowing them to punch above their weight in global affairs. Yet the impact extends far beyond diplomacy. The arms trade fuels domestic industries, creating high-skilled jobs in aerospace, shipbuilding, and cybersecurity. For buyers, the stakes are equally high: modern militaries rely on weapons sales by country to counter asymmetric threats, from drone swarms to hybrid warfare tactics. The downside? The human cost. Studies link arms proliferation to prolonged conflicts, as seen in Yemen and Libya, where foreign-supplied weapons have fueled civilian casualties. The economic toll is also significant: nations like Saudi Arabia and Egypt spend upwards of 10% of their GDP on military imports, diverting funds from education and infrastructure. > "The arms trade isn’t just about selling steel and missiles—it’s about selling access. Whoever controls the flow of weapons controls the narrative of global security." — Mark B. Schneider, former U.S. Defense Department officialMajor Advantages
- Strategic leverage: Arms exports allow nations to bind allies to their sphere of influence, as seen with U.S. sales to Gulf states or Russian deals in Africa.
- Economic stimulus: Defense industries generate jobs and R&D breakthroughs, from hypersonic missiles to unmanned systems.
- Technology transfer: High-end sales often include training and maintenance contracts, embedding foreign expertise in local militaries.
- Geopolitical signaling: A single deal—like France’s Rafale sales to India—can counterbalance rival exporters (e.g., Russia’s Su-35 offers).
- Sanctions circumvention: Nations under embargo (e.g., Iran, North Korea) often acquire weapons through intermediaries or black-market networks.
- Soft power projection: Arms sales reinforce a nation’s image as a reliable partner, as demonstrated by Germany’s recent push to sell submarines to Australia.

Comparative Analysis
| Key Metric | United States | Russia | China | France | Germany |
|---|---|---|---|---|---|
| Market Share (2022) | 40% | 16% | 5% | 8% | 5% |
| Primary Buyers | Middle East, Asia-Pacific, Europe | Africa, Middle East, Asia | Africa, Latin America, Southeast Asia | Middle East, Africa, Europe | Europe, Middle East |
| Signature Products | F-35, Abrams tanks, Tomahawk missiles | Su-35, S-400 air defense, Kalashnikov rifles | J-20 fighter, Type 055 destroyer, drones | Rafale, Mistral-class frigates, SCORPION tanks | Eurofighter, Leopard tanks, submarines |
| Financing Model | Export credits, FMS program | Barter deals, energy-linked sales | State-backed loans, ODA (Official Development Assistance) | Government guarantees, COFACE loans | ECAs, joint ventures |
| Geopolitical Goal | Alliance consolidation, countering China/Russia | Reasserting great-power status, countering NATO | Expanding Belt and Road influence | Maintaining EU defense autonomy | Strengthening transatlantic ties |
Future Trends and Innovations
The next decade of weapons sales by country will be defined by three disruptive forces. First, autonomous and AI-driven systems are reshaping the market. Drones like Turkey’s Bayraktar TB2 and China’s Wing Loong have already proven their lethality in Ukraine and Libya, while AI-powered cyber weapons are becoming a new frontier. Second, hypersonic and directed-energy weapons—such as lasers and railguns—are poised to redefine naval and air superiority, with the U.S. and China leading the race. Third, supply chain diversification is accelerating as nations seek alternatives to traditional exporters. India’s push for indigenous production (e.g., Tejas fighter) and Africa’s growing defense manufacturing sector signal a shift toward regional self-sufficiency. Yet challenges loom. The proliferation of micro-drones and 3D-printed firearms complicates arms control efforts, while climate change may force militaries to adapt their procurement strategies (e.g., Arctic warfare capabilities). The biggest wild card remains great-power competition: if U.S.-China tensions escalate, weapons sales by country could become a proxy battleground for technological dominance, with emerging markets caught in the crossfire.
Conclusion
The arms trade is far more than a commercial enterprise—it’s the backbone of modern geopolitics. Weapons sales by country reflect the priorities of nations, whether it’s the U.S. locking down Asia-Pacific allies, Russia leveraging energy deals, or China embedding its influence through infrastructure-linked arms transfers. The opacity of the industry ensures that every transaction carries unintended consequences, from fueling conflicts to distorting local economies. Yet the demand for military hardware isn’t going away. As new threats emerge—cyber warfare, space militarization, and climate-driven migrations—the stakes will only rise. For policymakers, the challenge is balancing security needs with ethical constraints. For businesses, the opportunity lies in adapting to a market where technology and geopolitics are inseparable. And for the public, the question remains: how much influence should commerce have over the tools of war?Comprehensive FAQs
Q: Which country is the world’s largest arms exporter?
A: The United States has consistently held the top spot, accounting for nearly 40% of global weapons sales by country in recent years. Its lead is attributed to its advanced technology, established export programs, and deep ties with key buyers like Saudi Arabia and Taiwan.
Q: How do sanctions affect arms sales?
A: Sanctions can severely limit a nation’s ability to participate in weapons sales by country. For example, Russia’s exclusion from Western defense markets after its 2022 invasion of Ukraine accelerated its push for arms deals with India, China, and African nations. Meanwhile, Iran and North Korea rely on smuggling networks and intermediaries to bypass sanctions.
Q: Are there any ethical regulations on arms sales?
A: The Arms Trade Treaty (ATT), adopted in 2013, aims to regulate the international trade in conventional arms by requiring states to assess risks of misuse. However, enforcement is weak, and many major exporters—including the U.S., Russia, and China—have not ratified the treaty. Ethical concerns often arise when weapons are sold to regimes with poor human rights records.
Q: How do smaller nations compete in the arms market?
A: Nations like Israel, Turkey, and South Korea have carved niches by specializing in high-tech, cost-effective systems (e.g., drones, cyber tools). They often leverage weapons sales by country to smaller buyers who can’t afford Western or Russian platforms, then use profits to fund R&D for more advanced systems.
Q: What role do private military companies (PMCs) play?
A: PMCs like Russia’s Wagner Group or the U.S.-based Academi (formerly Blackwater) operate in gray areas, providing logistics, training, and even combat support. They blur the line between weapons sales by country and direct military intervention, often working in conflict zones where governments hesitate to deploy troops.
Q: How does corruption impact arms deals?
A: Corruption is rampant in weapons sales by country, particularly in the Global South. Kickbacks, inflated contracts, and embezzlement have plagued deals in nations like Nigeria, Pakistan, and Indonesia. Transparency International estimates that up to 20% of defense budgets in some countries are lost to graft.
Q: Can arms sales be traced effectively?
A: Tracking weapons sales by country is notoriously difficult due to shell companies, mislabeled shipments, and informal networks. Organizations like Amnesty International and Conflict Armament Research use forensic analysis and open-source intelligence to trace weapons, but many transfers remain undocumented.
Q: What’s the future of drone sales?
A: Drones are becoming the fastest-growing segment of weapons sales by country, with Turkey’s Bayraktar TB2 and China’s Wing Loong leading the market. Their low cost and high effectiveness make them attractive to non-state actors, raising concerns about proliferation. Meanwhile, larger nations are developing AI-driven autonomous systems for future conflicts.
