
Breaking Down the Numbers
Geotab’s valuation isn’t a static number but a moving target, influenced by macroeconomic trends, competitor activity, and the shifting priorities of its investors. The company’s last major funding round, reported in 2021, valued it at hundreds of millions less than today’s estimates, yet the gap between then and now isn’t just about revenue growth—it’s about the premium placed on data-driven fleet solutions in an era where operational efficiency is non-negotiable. Private equity firms and strategic buyers increasingly view Geotab not as a niche player but as a platform with enterprise-grade scalability, a shift that has quietly inflated its market position and perceived worth.
The challenge in pinning down Geotab’s net worth lies in the nature of private valuations. Unlike a publicly traded company, where share price and market cap provide a daily snapshot, Geotab’s figures are derived from internal financials, investor negotiations, and industry benchmarks. Analysts often rely on multiples of revenue or EBITDA—common in private tech assessments—to estimate its current standing. While exact figures remain confidential, the consensus among observers suggests its valuation has more than doubled over the past five years, aligning with the broader trend of SaaS and IoT companies commanding higher multiples as data becomes the new currency.
The Verified Baseline
Publicly available data confirms Geotab’s revenue trajectory and market reach. The company, founded in 2000, has consistently expanded its customer base, now serving over 1.2 million vehicles across 150 countries. Its MyGeotab platform, a cloud-based telematics suite, processes billions of data points daily, a metric that underpins its recurring revenue model. While exact revenue figures aren’t disclosed, industry reports place annual sales in the $200–300 million range, a figure that would position Geotab among the top-tier players in fleet management software.
Geotab’s growth strategy has relied on organic expansion and strategic acquisitions, including the 2021 purchase of ClearPath, a fleet management software provider, for an undisclosed sum. The acquisition broadened its toolkit for electric vehicle (EV) fleets, a sector poised for explosive growth as governments and corporations rush to decarbonize transportation. This move wasn’t just about adding features—it was about future-proofing Geotab’s valuation in a market where sustainability is increasingly tied to profitability.
What the Estimates Suggest
Industry estimates, based on comparable private SaaS companies and Geotab’s reported growth rates, suggest its net worth could now exceed $1 billion. These figures are speculative but grounded in recent funding trends: private equity firms have shown willingness to pay 10x–15x revenue multiples for tech companies with strong unit economics, particularly those with sticky, subscription-based models. Geotab’s ability to renew contracts at rates above 90%—a testament to its platform’s stickiness—bolsters its appeal to potential acquirers or investors eyeing an exit.
The wild card in these estimates is the EV and autonomous vehicle (AV) market. Geotab’s early investments in EV fleet analytics have positioned it as a key player in a sector where data is critical for optimizing battery life, charging infrastructure, and route planning. If the transition to electric fleets accelerates, Geotab’s valuation could see a second-order effect, as its technology becomes indispensable to logistics giants and municipal governments. Conversely, economic downturns or slower-than-expected EV adoption could temper growth, making its current net worth a moving target rather than a fixed benchmark.
Case Study: A Closer Look
Geotab’s 2020 partnership with Volvo Trucks offers a microcosm of how its valuation is shaped by real-world impact. The collaboration, which integrated Geotab’s telematics into Volvo’s electric fleet solutions, wasn’t just a sales win—it was a proof point for investors. By demonstrating how its platform could reduce operational costs by 15–20% for EV fleets, Geotab reinforced its narrative as a cost-saving enabler, not just a software vendor. This alignment with a global OEM like Volvo elevated its perceived strategic value, a factor that likely influenced subsequent funding rounds.
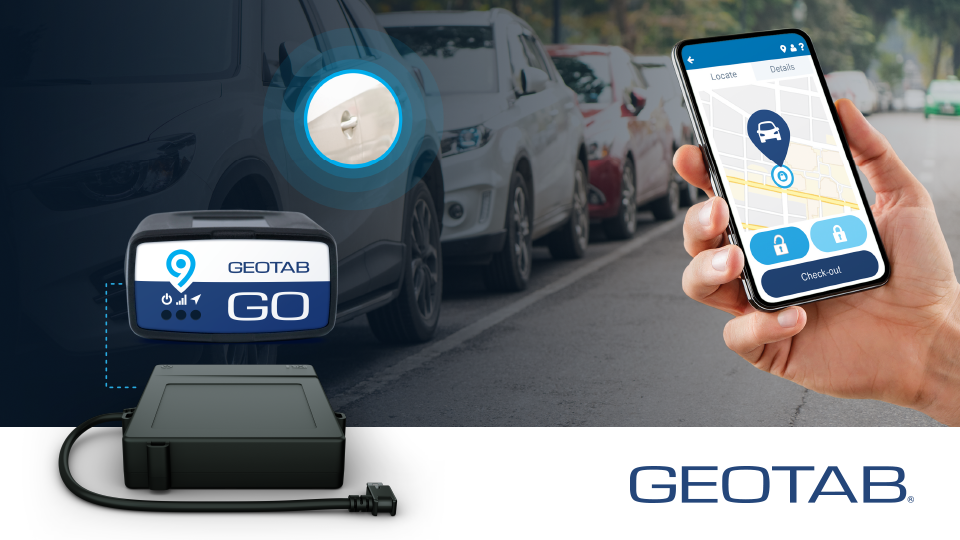
The partnership also highlighted Geotab’s ability to cross-sell services, from hardware (like its GO devices) to analytics and compliance tools. This ecosystem approach is a hallmark of high-growth private companies, where adjacent revenue streams can significantly boost valuation. For example, while its core SaaS revenue remains the backbone, upsells into EV optimization and predictive maintenance could add $50–100 million annually to its top line—a figure that would further justify its estimated net worth in the eyes of potential buyers.
"Geotab isn’t just selling software; it’s selling a competitive advantage. The more fleets rely on data to cut costs, the less they’ll tolerate inferior tools. That’s why its valuation isn’t just about today’s revenue—it’s about tomorrow’s inevitability." — Private equity analyst, 2023
| Factor | Estimated Impact on Valuation |
|---|---|
| EV Fleet Adoption Growth | Could add $200M–$400M if Geotab captures 20% of the North American EV fleet market by 2026. |
| Recurring Revenue Retention | 92%+ renewal rates justify 12x–14x revenue multiples, a premium over legacy fleet software. |
| Strategic Acquisitions (e.g., ClearPath) | Expanded EV toolkit may increase valuation by $150M–$300M if integrated successfully. |
| Macroeconomic Conditions | Inflation or recession could reduce growth projections by 10–20%, pressuring valuation. |
| Potential IPO or Acquisition | Exit event could realize $1B–$1.5B if sold at current multiples; IPO would depend on market conditions. |
What This Means Going Forward
Geotab’s net worth isn’t just a number—it’s a reflection of the broader shift toward data-driven fleet operations. As cities and corporations prioritize sustainability, Geotab’s role in optimizing EV fleets could become a valuation accelerant, pushing its worth beyond current estimates. The company’s ability to monetize data without overpaying for customer acquisition (its customer acquisition cost is reportedly $500–$800 per user) further strengthens its appeal to investors seeking high-margin growth.
The biggest variable remains how it deploys capital. If Geotab chooses to stay private and reinvest profits, its valuation could grow organically, albeit slowly. But if it pursues an IPO or acquisition within the next three years, the timing will hinge on market conditions and the perceived urgency of its EV solutions. Either path presents risks: an IPO could dilute early investors, while a sale might cap its growth potential. The sweet spot may lie in strategic partnerships—like its Volvo collaboration—that extend its reach without diluting control.
Conclusion
Geotab’s journey from a niche telematics provider to a highly valued private tech asset underscores a fundamental truth: in the fleet management space, data isn’t just a byproduct—it’s the product. Its net worth, while impossible to pinpoint precisely, is a function of its ability to turn vehicle data into actionable insights, a capability that has made it indispensable to industries from logistics to public transit. The next phase will test whether Geotab can leverage its valuation to dominate new markets—or whether its worth will plateau if it fails to adapt to the next wave of fleet innovation.
For now, the most compelling narrative isn’t about its exact dollar figure but about the principles that underpin it: a relentless focus on retention, a willingness to bet on emerging trends like EVs, and the discipline to grow without sacrificing profitability. In a world where fleet management is becoming synonymous with digital transformation, Geotab’s valuation is less about the past and more about what it can become.
Comprehensive FAQs
#### Q: Is Geotab’s valuation public?
A: No. As a private company, Geotab does not disclose its valuation. Estimates—typically ranging from $800 million to over $1 billion—are derived from industry benchmarks, funding rounds, and comparable SaaS valuations. The last confirmed funding round (2021) valued it at a lower figure, but strategic acquisitions and market trends have likely increased its worth since then.
####Q: How does Geotab’s valuation compare to competitors?
A: Geotab’s estimated net worth places it among the top-tier private fleet management firms, alongside companies like Samskip (public, ~$500M market cap) and Webfleet Solutions (acquired by Geotab’s rival, Samsara, in a deal rumored to exceed $100M). Publicly, Samsara (NASDAQ: IOT)—a direct competitor—has a market cap of $3.5 billion, but its valuation includes hardware revenue and a broader IoT play, making direct comparisons difficult. Geotab’s focus on pure-play telematics and EV optimization gives it a niche advantage in private markets.
####Q: Could Geotab go public?
A: It’s possible, but not imminent. Geotab has no stated IPO plans, and private equity backers may prefer an acquisition by a larger player (e.g., Trimble, Oracle, or a logistics giant) to unlock value. An IPO would depend on market conditions, particularly investor appetite for SaaS stocks post-2022 correction. If it were to list, analysts suggest a $1B+ valuation could be achievable, but timing would be critical to avoid the pitfalls of a downturn.
####Q: What drives Geotab’s valuation most?
A: Three factors dominate: recurring revenue retention (90%+), its EV fleet analytics expertise, and strategic acquisitions that expand its toolkit. Unlike hardware-dependent competitors, Geotab’s subscription model and high renewal rates make it attractive to private equity firms seeking scalable, low-churn businesses. Its EV focus also aligns with government incentives, adding a regulatory tailwind to its growth projections.
####Q: Has Geotab ever been acquired?
A: No, but it has acquired competitors, including ClearPath (2021) and Webfleet (2018, though Webfleet was later spun off to Samsara). These moves were growth-driven, not defensive. Geotab’s own acquisition potential remains speculative; if it were to be bought, likely suitors would include public IoT firms (Samsara, Trimble) or logistics conglomerates (Maersk, DHL) looking to integrate fleet data into their operations.
####Q: How does Geotab’s valuation affect its customers?
A: Indirectly, a higher valuation signals investor confidence, which can translate to faster product innovation, broader feature sets, and potentially lower prices as Geotab competes for market share. Customers also benefit from strategic partnerships (e.g., Volvo) that stem from its strong financial backing. However, if Geotab were acquired, customers might face integration risks or shifts in product roadmaps, depending on the buyer’s priorities.
####Q: What risks could hurt Geotab’s valuation?
A: Macroeconomic downturns (reducing fleet budgets), slower EV adoption than projected, or competition from larger tech firms (e.g., Google’s entry into fleet management) could pressure growth. Internally, execution risks—such as failing to integrate acquisitions smoothly or losing key talent—could also dampen investor enthusiasm. Geotab’s reliance on North American and European markets further exposes it to regional economic shocks.
####Q: Are there rumors of Geotab being sold?
A: Speculation occasionally surfaces, particularly after major fleet tech deals (e.g., Samsara’s acquisitions). However, no credible rumors of an imminent sale have emerged. Geotab’s leadership has signaled a long-term growth strategy, and its recent investments in EV analytics suggest a focus on organic expansion rather than an exit. That said, private equity firms often hold assets for 7–10 years, so a sale isn’t off the table—but it would likely require a strategic buyer willing to pay a premium for its EV capabilities.
