Where It All Began
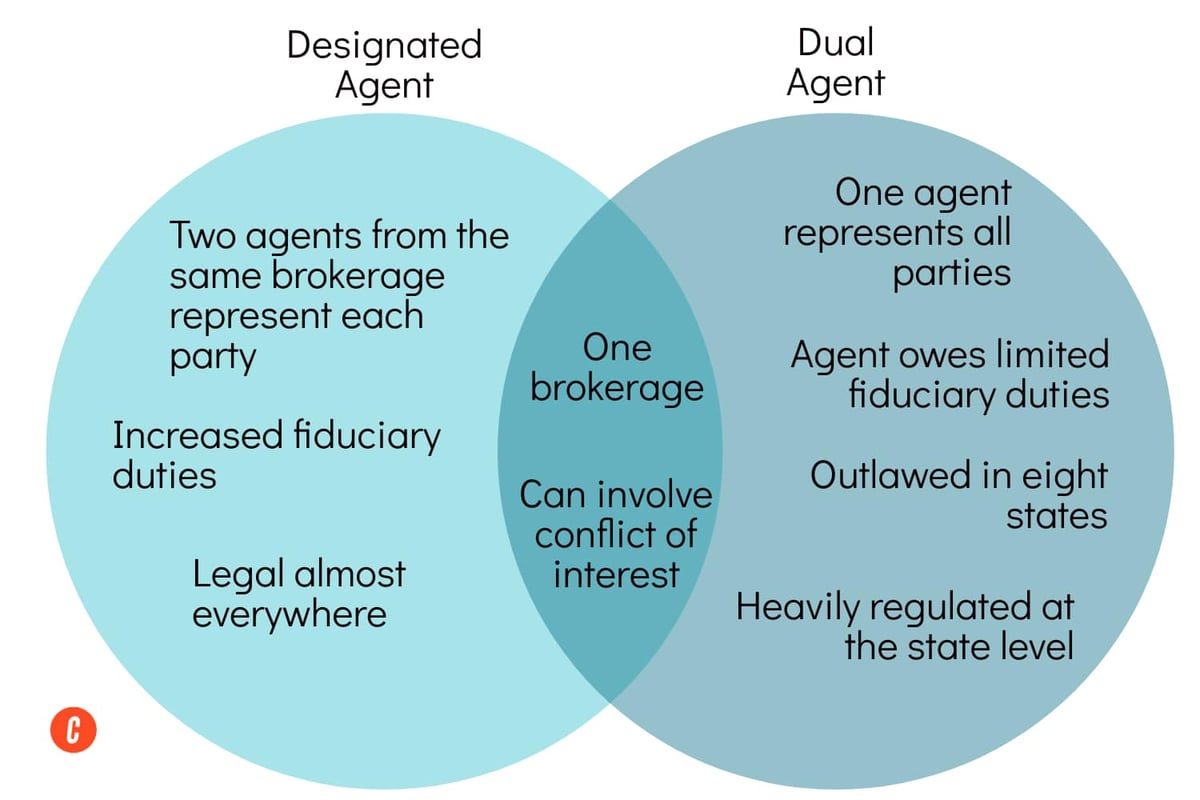
Florida’s flirtation with dual agency dates back to the 1990s, when the state’s real estate commission (FREC) first grappled with how to regulate brokers acting as intermediaries. At the time, dual agency—the practice of representing both parties in a single deal—was widely condemned as a conflict of interest. Most states banned it outright, while others restricted it to transactions where the broker’s role was strictly transactional, with no fiduciary duty to either side. Florida leaned toward the restrictive camp, requiring brokers to choose one party to represent or designate a transaction broker for neutral facilitation. The early signs of change came in 2000, when FREC proposed amendments to its licensing rules. The debate centered on whether Florida’s ban was stifling efficiency, especially in commercial real estate where deals often hinged on speed and discretion. Proponents argued that dual agency could streamline negotiations in high-value transactions, where buyers and sellers might otherwise walk away due to delays. Opponents, including consumer advocacy groups, warned that allowing dual agency—even with disclosures—would inevitably lead to brokers prioritizing commissions over clients’ best interests.The Early Signs
By 2005, the tension had crystallized. A series of high-profile lawsuits emerged, with brokers alleging that Florida’s strict rules put them at a competitive disadvantage compared to states like Texas or California, where dual agency was permitted under certain conditions. Meanwhile, commercial brokers—particularly those handling luxury condos, industrial properties, and land deals—lobbied for exceptions. Their argument was simple: if a broker’s net worth and reputation were already on the line, why shouldn’t they be allowed to earn fees from both sides? The turning point arrived in 2010, when Florida’s legislature began considering a bill that would carve out an exemption for brokers with commercial net worth of at least $1 million. The bill’s sponsors framed it as a way to attract top talent to Florida’s booming markets while maintaining protections for ordinary homebuyers. Critics, however, saw it as a backdoor to legitimizing dual agency for the wealthy. The debate wasn’t just about money—it was about whether Florida’s real estate industry could reconcile its image as a consumer-friendly state with the realities of a cutthroat market.The Turning Point
The bill passed in 2011, but the real battle was in the implementation. FREC spent two years drafting rules that would govern dual agency allowed if commercial net worth $1 million, including mandatory disclosures, client consent forms, and audits to verify net worth claims. The rules were designed to assuage critics: only brokers with verifiable assets could participate, and every transaction would require written acknowledgment from both parties that they understood the conflicts. The policy’s defenders pointed to early adopters—brokers who’d already been operating in a dual-capacity gray area—as proof it wouldn’t lead to abuse. "If you’re a millionaire broker with a sterling reputation, clients trust you more than they trust a faceless transaction broker," said one industry insider at the time. But skeptics argued the rule was a Trojan horse, allowing the wealthiest players to game the system while smaller brokers were left out."Florida told the world it was protecting consumers, but what it really did was open the door for brokers who could afford to take the risk—and leave everyone else behind." — Consumer Protection Attorney, 2013
The Build-Up, Year by Year
| Period | What Happened |
|---|---|
| 2012–2014 | FREC began approving dual agency exemptions for brokers with commercial net worth exceeding $1 million, though enforcement was inconsistent. Some brokers reported difficulties proving their net worth without triggering tax scrutiny. |
| 2015–2017 | Commercial brokers in Miami and Orlando increasingly used the exemption, particularly in deals over $5 million. Residential brokers, however, remained largely excluded, leading to a two-tiered system. |
| 2018–2020 | FREC tightened disclosure requirements after complaints that some brokers weren’t fully explaining conflicts. Meanwhile, a Florida appeals court upheld the net worth threshold, dismissing a challenge from a brokerage that argued it was arbitrary. |
Lessons From the Journey
- Wealth as a proxy for trust: The rule assumed that a broker’s net worth correlated with their integrity—a risky assumption in an industry where reputation is intangible.
- Market segmentation: The exemption deepened divisions between commercial and residential brokers, with the former gaining flexibility the latter lacked.
- Enforcement gaps: Verifying net worth proved difficult, leading to instances where brokers allegedly inflated assets to qualify.
- Consumer confusion: Many clients didn’t realize they could opt out of dual agency, assuming the broker’s wealth meant impartiality.
Where Things Stand Today
A decade after the rule’s introduction, dual agency allowed if commercial net worth $1 million remains a defining feature of Florida’s real estate landscape. Commercial brokers in high-end markets—especially Miami, Palm Beach, and Tampa—routinely use the exemption, often framing it as a way to offer "white-glove service" that transaction brokers can’t match. Meanwhile, residential brokers continue to operate under stricter rules, though some have pushed for parity, arguing that the $1 million threshold is outdated in today’s market. The policy’s longevity hasn’t silenced criticism. Consumer groups still argue that dual agency, regardless of net worth, creates inherent conflicts. Brokers who’ve crossed the $1 million line often defend the rule by citing their ability to close deals that would stall under traditional models. Yet the debate persists: Is Florida’s approach a pragmatic solution, or a concession to the industry’s most powerful players?
Conclusion
Florida’s experiment with wealth-based dual agency is less about net worth and more about who gets to call the shots in real estate. The rule didn’t just change who could represent both sides of a deal—it reinforced the idea that in Florida, access to opportunity often depends on how much you’re worth. For brokers, it’s been a double-edged sword: more deals, but at the cost of trust. For consumers, it’s meant navigating a system where the broker’s balance sheet might matter more than their ethics. As Florida’s markets continue to evolve, the $1 million threshold may yet become a relic—or a standard others adopt. One thing is certain: the debate over dual agency isn’t going away. It’s just gotten more expensive.Comprehensive FAQs
Q: Does Florida’s rule apply to residential brokers?
The exemption for dual agency allowed if commercial net worth $1 million primarily targets commercial transactions. Residential brokers must still follow Florida’s stricter dual agency prohibitions unless they meet additional criteria, such as designating a transaction broker.
Q: Can a broker with $1 million in net worth still represent one party exclusively?
Yes. The rule only permits dual agency if the broker qualifies under the net worth exemption and obtains written consent from both clients. Brokers can still choose to represent one side, just as they could before the rule changed.
Q: How does Florida verify a broker’s net worth?
FREC requires brokers to submit financial statements, tax returns, or third-party valuations to prove their commercial net worth exceeds $1 million. Audits can be triggered if discrepancies arise, though enforcement varies by region.
Q: Are there states with similar rules?
No state has adopted an identical net worth-based exemption. Some, like Texas and California, allow dual agency under broader conditions (e.g., disclosed conflicts, client consent), but none tie eligibility to a specific asset threshold.
Q: What happens if a broker’s net worth drops below $1 million?
The broker must immediately cease dual agency activities. FREC can impose penalties for continuing to operate under the exemption without meeting the threshold.
Q: Has the rule led to more complaints?
Industry reports suggest complaints related to dual agency have risen, though not all are tied to the net worth exemption. Many stem from clients who later realize they were represented by the same broker on both sides without full disclosure.
Q: Could Florida raise or lower the $1 million threshold?
Legislative changes are possible, but any adjustment would face scrutiny. Raising the threshold could exclude more brokers; lowering it might erode consumer protections. The current balance reflects Florida’s attempt to walk a fine line between flexibility and accountability.
