Common Myths About Excel Templates to Calculate Net Worth
The assumption that Excel templates to calculate net worth are only for the wealthy persists, even though personal finance experts—including those who advise clients with modest incomes—recommend them. The reasoning? Complexity. Many templates include advanced features like Monte Carlo simulations or tax-loss harvesting, which are irrelevant to someone tracking a $50,000 net worth. Yet the core function—summing assets minus liabilities—applies universally. The mistake isn’t in the tool’s capability; it’s in assuming that sophistication equals necessity. Another myth treats these templates as passive records rather than active management systems. Users often input data once and revisit it annually, if at all. But net worth isn’t static. A single stock sale, a medical bill, or an unexpected bonus can shift the equation. The best net worth calculation spreadsheets aren’t just calculators; they’re early-warning systems. They flag anomalies—like a sudden drop in liquid assets—or project future scenarios based on current trends. Ignoring this dynamic aspect turns a useful tool into a historical footnote.Myth 1: All Excel Templates to Calculate Net Worth Are the Same
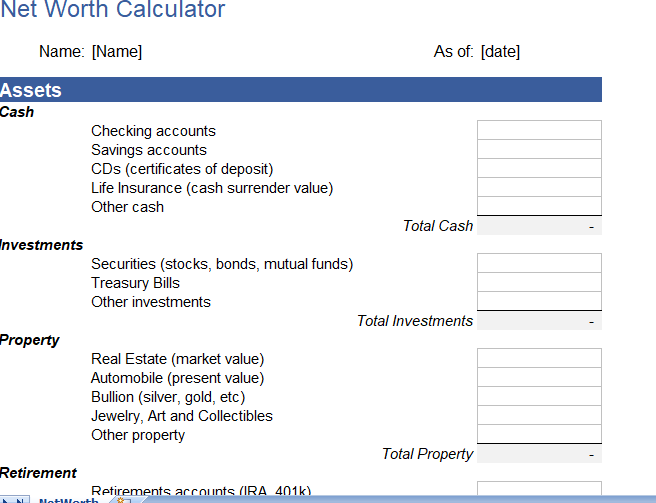
Templates vary as much as financial portfolios do. Some focus on simplicity, offering basic columns for cash, investments, and debt. Others dive deep, separating retirement accounts by tax-advantaged status or distinguishing between primary and secondary real estate. A template designed for a physician tracking practice goodwill won’t work for a remote worker with a side hustle. The categories matter: omitting intangible assets (like a freelancer’s client list) or failing to account for inflation-adjusted values skews results. The structure also differs. Some templates use separate sheets for assets, liabilities, and cash flow; others consolidate everything into one tab. A few integrate with bank feeds or investment platforms, while others require manual entry. The key isn’t to find the most feature-rich option but the one that aligns with your financial complexity. A net worth tracker Excel template tailored to a landlord’s rental properties will include columns for vacancy rates and maintenance reserves—details absent in a generic version.Myth 2: You Need Advanced Excel Skills to Use These Templates
Most Excel templates to calculate net worth are designed for users with basic proficiency. They rely on simple formulas (SUM, VLOOKUP) and pre-built tables. The real skill lies in data hygiene: ensuring every asset and liability is accurately categorized and updated. A template won’t prevent you from mislabeling a car loan as a mortgage or forgetting to adjust for depreciation. Those errors stem from user input, not spreadsheet limitations. That said, some advanced templates use macros or pivot tables to automate reporting. If you’re unfamiliar with these functions, stick to static or semi-automated versions. The goal isn’t to master Excel—it’s to leverage its precision. Even a rudimentary net worth calculation Excel template will outperform mental math or a handwritten ledger.Myth 3: The Most Detailed Template Is Always the Best
Over-engineering a net worth tracker adds noise without insight. A template with 50 columns for niche assets (like collectibles or digital royalties) may impress but overwhelm. The best Excel templates to calculate net worth strike a balance: they capture what’s material to your situation while excluding irrelevant details. For example, tracking the exact model of your car isn’t useful—only its current market value matters. Detail should serve a purpose. If you’re planning to sell a property, include columns for recent appraisals and holding costs. If you’re monitoring a stock portfolio, link to a separate investment tracker. The template’s job is to highlight what needs attention, not bury you in data.
What Holds Up to Scrutiny
At their core, Excel templates to calculate net worth perform two critical functions: aggregation and benchmarking. Aggregation ensures no asset or liability is overlooked. Benchmarking compares your current net worth to past periods or industry averages (e.g., median net worth by age group). These functions are verifiable because they rely on observable data—not speculation. The most reliable templates also incorporate liquidity adjustments. Not all assets are equally accessible. A 401(k) has withdrawal rules; real estate requires a sale. The best net worth calculation spreadsheets distinguish between liquid and illiquid assets, providing a clearer picture of true financial flexibility. This isn’t optional; it’s foundational. Without it, a high net worth number can mask a cash-flow crisis."A net worth statement is like a financial X-ray—it reveals what’s solid and what’s fragile. But the image only helps if you know how to read it." — Jane Smith, Certified Financial Planner (CFP)
| Common Belief | What the Evidence Says |
|---|---|
| A higher net worth means better financial health. | Not necessarily. A net worth of $2 million could include illiquid assets (e.g., a business) and high debt. Liquidity and debt-to-equity ratios matter more. |
| You should update your net worth annually. | Quarterly updates are better for tracking volatility (e.g., stock markets, property values). Monthly works for those with frequent transactions. |
| Free templates are as accurate as paid ones. | Free templates often lack customization or support. Paid versions may include audit trails, tax-optimized categories, or integration with financial tools. |
| Net worth only matters for retirement planning. | It’s also critical for risk management (e.g., insurance needs), estate planning, and major life events (buying a home, starting a business). |
Why the Confusion Persists
Part of the confusion stems from how net worth is portrayed in media. Financial gurus often simplify it to "assets minus debt," ignoring the nuances of valuation, timing, and personal context. Meanwhile, accountants and tax professionals use industry-specific templates that exclude everyday assets like furniture or a personal vehicle. The gap between these perspectives leaves individuals unsure where to start. Another factor is the halo effect of financial tools. Just because a template is used by wealth managers doesn’t mean it’s right for you. A hedge fund’s net worth tracker—with columns for private equity stakes and currency hedges—is useless for a teacher saving for a down payment. The tools’ flexibility is also a double-edged sword: too many customization options can lead to paralysis. Users either overcomplicate their setup or underutilize the template’s potential.
Conclusion
Excel templates to calculate net worth aren’t a silver bullet, but they are the closest thing to one for personal finance tracking. Their power lies in their adaptability—whether you’re a first-time homebuyer, a small-business owner, or someone nearing retirement. The key is to treat them as living documents, not static snapshots. Regular updates, clear categorization, and a focus on liquidity will turn a spreadsheet into a strategic asset. The best template isn’t the one with the most features; it’s the one that fits your financial reality. Start with a simple version, refine it as your needs evolve, and use it to ask better questions: Where should I allocate my next raise? Can I afford to take this risk? The numbers will answer—but only if you’ve set up the framework to listen.Comprehensive FAQs
Q: Are free Excel templates to calculate net worth reliable?
A: Free templates can be reliable if they’re well-structured and regularly updated. Look for versions with clear instructions, sample data, and user reviews. Avoid templates that lack categories for common assets (e.g., retirement accounts, vehicles) or don’t account for inflation. Paid templates often include validation checks or integration with financial tools, which can improve accuracy.
Q: How often should I update my net worth using these templates?
A: For most people, quarterly updates are ideal—especially if you have volatile assets (e.g., stocks, cryptocurrency). Monthly updates work well for those with frequent transactions (e.g., freelancers, small-business owners). Annual updates may suffice if your financial situation is stable (e.g., fixed income, minimal investments). The goal is to catch significant changes before they become trends.
Q: Can I customize an existing Excel template to calculate net worth for my specific needs?
A: Absolutely. Most templates are designed to be adapted. Start by identifying missing categories (e.g., digital assets, side-hustle income) and add them as new columns or sheets. Use conditional formatting to highlight outliers (e.g., liabilities exceeding 30% of net worth). Just ensure any formulas you modify are accurate—double-check with a financial calculator or advisor if unsure.
Q: Do these templates account for inflation when calculating net worth?
A: Basic templates don’t adjust for inflation by default, but you can add a column for inflation-adjusted values. Use the Consumer Price Index (CPI) or a personal inflation tracker (e.g., a 3% annual adjustment for simplicity). For long-term tracking, this is critical—$1 million in 2010 isn’t the same as $1 million in 2030. Some advanced templates include built-in inflation calculators.
Q: Should I include my home’s current market value or its original purchase price in my net worth calculation?
A: Always use the current market value, not the purchase price. Market value reflects what you’d realistically sell the home for today, minus any outstanding mortgage balance. If you’re unsure of the current value, use a recent appraisal or a tool like Zillow’s Zestimate (with a 10–20% buffer for accuracy). Overestimating home value is a common mistake that inflates net worth artificially.
Q: Can I use Excel templates to calculate net worth for a business or only personal finances?
A: Both. Personal finance templates can be adapted for small businesses by adding columns for inventory, accounts receivable/payable, and business liabilities. For larger businesses, you’ll need an accounting system (e.g., QuickBooks) linked to a separate net worth tracker. The principle remains the same: assets minus liabilities, but the categories expand to include operational metrics.
Q: What’s the best way to back up my net worth Excel template?
A: Store multiple copies in secure locations: a cloud service (Google Drive, Dropbox), an external hard drive, and your email (as a PDF). Use version control (e.g., naming files with dates: NetWorth_2024_Q2.xlsx) to track changes. Avoid storing sensitive data (e.g., Social Security numbers) in the spreadsheet itself—keep those in a separate, encrypted file. Automate backups if possible to prevent data loss.
Q: Are there Excel templates to calculate net worth that integrate with banking or investment apps?
A: Some templates offer limited integration via plugins (e.g., Power Query for bank feeds) or manual import options (CSV/Excel exports from platforms like Mint or Personal Capital). For deeper integration, use APIs if available (e.g., Fidelity’s API for investment data). However, most templates rely on manual entry for flexibility. If automation is a priority, consider dedicated financial software (e.g., YNAB, Quicken) that syncs directly with accounts.
