5 Things Worth Knowing About Excel Templates for Personal Finance Net Worth
The most effective personal finance net worth trackers share five core principles. These aren’t just features; they’re the difference between a ledger and a financial command center.1. The Single Most Critical Formula Isn’t What You Think
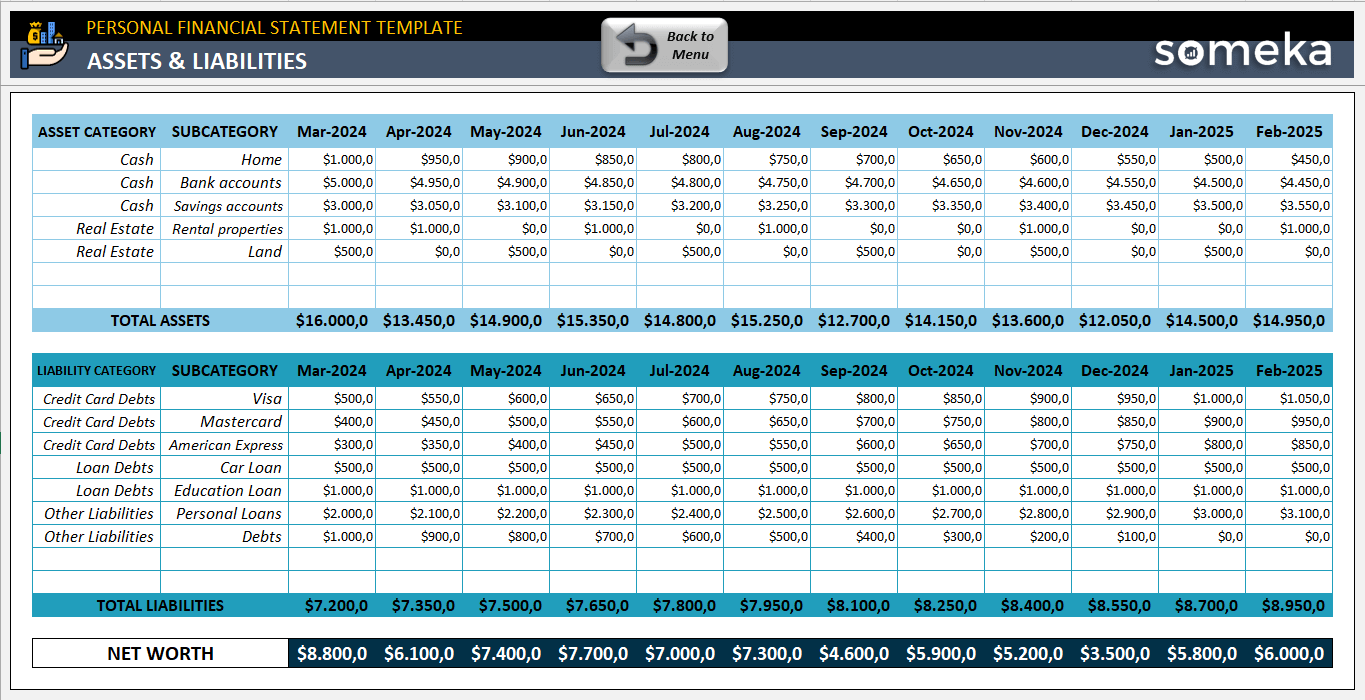
Most templates simplify net worth to assets minus liabilities, but the real value lies in how those components are categorized and recalculated. A static formula misses two critical dynamics: liquidity risk (e.g., an illiquid investment like real estate) and time decay (e.g., a car losing value faster than projected). Advanced Excel templates for personal finance net worth separate assets into tiers—high-liquidity (cash, brokerage accounts), medium-liquidity (retirement accounts, rental properties), and low-liquidity (collectibles, private equity). Liabilities are similarly segmented: fixed (mortgage, student loans) vs. variable (credit cards, medical debt). The formula then adjusts for expected cash flow from assets (e.g., rental income) and debt repayment schedules. This isn’t just accounting—it’s a stress-test for financial resilience. The second layer is automated recalculation triggers. A template that only updates manually becomes obsolete within weeks. The best systems pull data from bank feeds (via Power Query or third-party tools) or require weekly input to reflect market changes, new debts, or one-time expenses. Without this, a net worth figure from January might be 15% off by March—even for disciplined savers.2. The Hidden Danger of Over-Categorizing
Paradoxically, the more granular a personal finance net worth tracker in Excel becomes, the less useful it can be. A template with 50 asset classes and 20 liability subcategories creates analysis paralysis. The sweet spot is three to five primary categories that align with your financial goals. For example: - Growth assets (stocks, ETFs) tracked by cost basis and current valuation. - Stable assets (cash, bonds) with yield projections. - Leveraged assets (real estate, business equity) with debt service ratios. Liabilities should similarly group by repayment horizon: short-term (under 2 years), medium-term (2–7 years), and long-term (beyond 7 years). The goal isn’t perfection—it’s actionable clarity. A template that forces you to log every $5 Amazon purchase but ignores a $50,000 student loan is failing its purpose.3. Net Worth Isn’t Just a Number—It’s a Story
The most powerful Excel templates for personal finance net worth don’t just display a total; they visualize trends over time. A static net worth figure tells you where you stand today. A line graph spanning five years reveals: - Seasonality (e.g., bonuses in December boosting net worth temporarily). - Inflection points (e.g., a job change, inheritance, or market crash). - Goal alignment (e.g., tracking progress toward a $500K target). Tools like conditional formatting can highlight when net worth dips below a threshold (e.g., 3x monthly expenses) or when asset allocation drifts from your target. Some templates even include narrative fields where you can annotate why a spike or drop occurred—turning raw data into a financial diary. This is how professionals spot leaks before they become crises.4. The Tax and Legal Layers Most Templates Ignore
A net worth statement is useless if it doesn’t account for tax liabilities and legal encumbrances. For example: - Unrealized capital gains (stocks held long-term) can distort liquidity. - Pending lawsuits or judgments might not appear on a balance sheet but could wipe out assets. - Trust structures or LLCs complicate ownership—do you count the asset at fair market value or its book value? Advanced personal finance net worth trackers include: - A tax liability tracker (estimated capital gains, AMT risk, state taxes). - A legal risk column flagging assets tied to lawsuits or liens. - Projections for tax-efficient withdrawals (e.g., Roth conversions vs. traditional IRA). Even high-net-worth individuals have seen their Excel templates for personal finance net worth become obsolete overnight when an unanticipated tax bill or legal claim surfaces. The best templates treat these as non-negotiable add-ons, not optional extras.5. The Best Template Is One You’ll Actually Use
"A spreadsheet is only as useful as the person using it. The fanciest Excel template for personal finance net worth won’t save you if it’s locked in a drawer." — Jane Smith, Certified Financial Planner (CFP®)The most sophisticated template fails if it requires PhD-level Excel skills to maintain. Key usability factors: - Input frequency: Weekly updates for cash flow, monthly for investments, quarterly for tax adjustments. - Mobile accessibility: Cloud-based templates (Google Sheets or OneDrive-linked Excel) that sync across devices. - Error tolerance: Built-in checks for duplicate entries or impossible values (e.g., negative cash). - Scalability: Room to add new categories without restructuring the entire sheet. The gold standard? A template that reduces friction—not one that adds steps. For example, linking directly to bank APIs (via tools like YNAB or Mint) eliminates manual data entry. The trade-off? Less control over categorization. The solution? Use APIs for transactions but manually review at least one category per month to catch misclassifications.
How These Facts Connect
The five principles above don’t exist in isolation. They form a feedback loop where each element reinforces the others. A template that ignores tax implications (Point 4) will mislead you about true liquidity, undermining the liquidity tiers (Point 1). Over-categorization (Point 2) clutters the narrative (Point 3), making it harder to spot trends. And no matter how elegant the design, if it’s not used consistently (Point 5), the entire system collapses. The synthesis reveals two truths: 1. Net worth is a verb, not a noun. It’s not a static number but a living metric that responds to market shifts, personal decisions, and external shocks. A great Excel template for personal finance net worth isn’t a snapshot—it’s a simulation engine. 2. The best templates are anti-fragile. They don’t just track data; they anticipate failure modes. A well-built system will warn you if your emergency fund is too small relative to your liabilities, or if your asset allocation is too concentrated in a single sector.| Key Principle | What It Solves | Common Mistake | Pro Tip |
|---|---|---|---|
| Dynamic asset/liability tiers | Liquidity mismatches, debt repayment risks | Treating all assets as equally liquid | Use conditional formatting to color-code tiers by risk. |
| Minimalist categorization | Analysis paralysis, irrelevant data overload | Over-segmenting (e.g., 15 expense categories) | Limit to 3–5 primary asset classes and 2 liability types. |
| Visual trend tracking | Ignoring seasonality, missing inflection points | Static net worth figures without time-series data | Embed a line graph that auto-updates with new entries. |
| Tax and legal layers | Underestimating liabilities, unrealized gains risks | Skipping tax projections or legal encumbrances | Add a "Pending Risks" tab linked to your estate plan. |
Conclusion
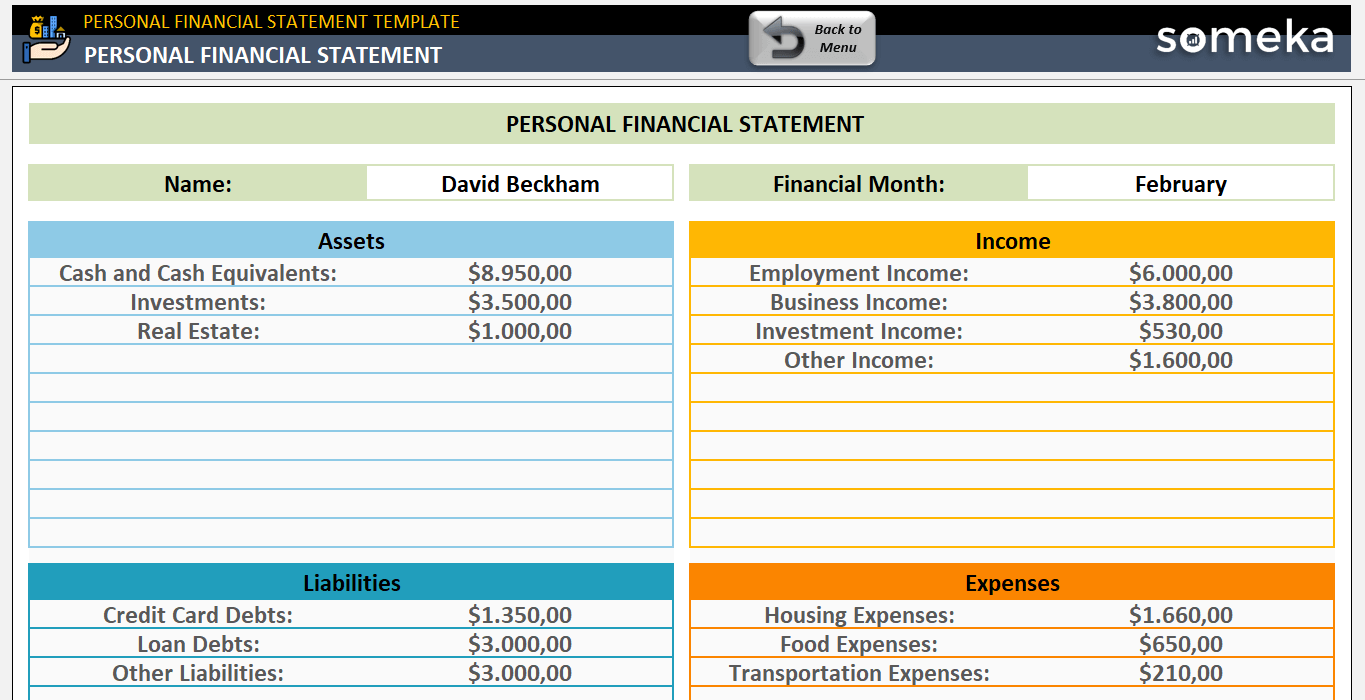
Excel templates for personal finance net worth aren’t a luxury—they’re a necessity for anyone serious about financial control. The difference between a template that gathers dust and one that transforms your money management lies in intentional design. It’s not about the number of cells or the complexity of formulas; it’s about building a system that reflects your financial personality—whether you’re a hands-on micro-manager or a big-picture investor. The most effective tools don’t just track; they challenge. They ask: Why did your net worth drop last quarter? Are your liabilities growing faster than your assets? What would happen if you lost 20% of your liquid assets tomorrow? A template that answers these questions isn’t just a spreadsheet—it’s a financial early-warning system.Comprehensive FAQs
Q: Can I use free Excel templates for personal finance net worth, or do I need a paid one?
A: Free templates (from Microsoft’s template gallery or Vertex42) work for basic tracking, but they lack automation, tax layers, and dynamic recalculations. Paid templates (e.g., Tiller Money, Personal Capital’s tools) or custom-built ones cost $20–$100 but save hours annually. The trade-off? Free templates require more manual effort to adapt.
Q: How often should I update my net worth tracker?
A: Monthly for cash flow and liabilities, quarterly for investments (to avoid tax-lot tracking errors), and annually for major assets (real estate, business equity). Market fluctuations justify more frequent updates if you’re heavily invested in volatile assets.
Q: What’s the best way to handle fluctuating asset values (e.g., stocks, crypto)?
A: Use real-time pull from brokerage APIs (via Power Query) or manual entry with a "last known value" fallback. For crypto, add a volatility buffer (e.g., ±10% margin) since prices swing daily. Never rely on static values—even "stable" assets like bonds can shift with interest rates.
Q: Should I include my spouse’s or partner’s finances in the same template?
A: Yes, if finances are combined, but no if they’re separate. Use a separate sheet or color-coding to avoid confusion. For joint accounts, create a "Shared Assets" category with clear ownership percentages. If you’re legally separated, document this in a notes field to avoid disputes.
Q: How do I protect my Excel template from errors or corruption?
A: 1) Auto-save to cloud storage (OneDrive/Google Drive) with version history enabled. 2) Use data validation to prevent impossible entries (e.g., negative cash). 3) Backup critical files to a secondary location. 4) Test formulas quarterly by re-entering a sample dataset. Most corruption stems from manual overwrites or link failures.
Q: Can I use these templates for business net worth tracking?
A: No, not directly. Personal finance templates lack depreciation schedules, inventory tracking, or revenue projections. For businesses, use QuickBooks + Excel or specialized tools like Xero. However, you can adapt a personal template’s categorization logic for a simplified business overview (e.g., separating operating assets from owner equity).
