Breaking Down the Numbers
Europe’s europes net worth cannot be summed up in a single ledger, but key indicators provide a framework. The continent’s gross household wealth—a broader measure than GDP—was estimated at €75 trillion in 2022, according to the European Central Bank. This figure includes everything from pension funds to art collections, though it excludes the trillions held in tax havens or unlisted family trusts. When contrasted with the €12 trillion in public debt across the Eurozone, the disparity underscores a systemic reliance on private capital to offset fiscal deficits. The breakdown varies sharply by region. Northern Europe—Sweden, Denmark, and the Netherlands—boasts net positive wealth per capita, driven by strong labor markets, high savings rates, and a culture of equity ownership. Southern Europe, meanwhile, grapples with negative net worth for many households, where property values stagnate and youth unemployment erodes intergenerational wealth transfer. Even within Germany, Europe’s largest economy, the europes net worth story is bifurcated: Munich’s real estate market trades at premiums unseen in Berlin, where renters outnumber homeowners by a 2:1 margin.The Verified Baseline
Publicly available data offers a few certainties. The European Union’s combined GDP—the most cited metric—stood at €15.5 trillion in 2023, making it the world’s second-largest economy after the U.S. Yet GDP alone obscures wealth distribution. The Eurostat Household Finance and Consumption Survey reveals that the top 10% of Europeans hold 60% of all financial assets, while the bottom 50% own just 3%. This concentration is most extreme in offshore finance hubs like Monaco, where the average net worth per adult exceeds €10 million, and in Switzerland, where private banking assets under management hit CHF 3.2 trillion in 2023. What is undeniable is the real estate anchor propping up Europe’s europes net worth. Property accounts for 40-60% of household assets across the continent, with London, Paris, and Milan leading as liquidity hubs. Even in crisis-hit Spain, real estate values have rebounded to pre-2008 levels in prime markets, though affordability remains a political flashpoint. The luxury goods sector—another pillar—generated €360 billion in 2023, with Swiss watchmakers and Italian fashion houses contributing disproportionately to export-led wealth.What the Estimates Suggest
Private wealth estimates carry wider margins of error. Credit Suisse’s Global Wealth Report suggests that Europe’s ultra-high-net-worth individuals (UHNWIs)—those with €50 million+—number around 1.3 million, controlling assets worth €15 trillion. However, this figure likely undercounts unlisted family wealth, particularly in Germany, where Mittelstand firms (privately held mid-sized companies) dominate the economy. The Stiftung Familienunternehmen estimates that 30% of Germany’s GDP is generated by family-owned businesses, many with valuations exceeding €1 billion but no public disclosure. Offshore holdings add another layer of opacity. The Panama Papers and Paradise Papers leaks revealed that €1.5 trillion in European wealth was parked in tax havens as of 2016—a figure that has likely grown. While the EU’s Common Consolidated Corporate Tax Base (CCCTB) aims to curb profit-shifting, enforcement remains patchy. Meanwhile, digital assets—crypto, NFTs, and private equity stakes—are reshaping valuations. The European Blockchain Association estimates that €100 billion in crypto assets are held by Europeans, though regulatory crackdowns (e.g., France’s 30% tax on crypto gains) may suppress future growth.
Case Study: A Closer Look
Few entities embody Europe’s europes net worth paradox better than LVMH, the luxury conglomerate headed by Bernard Arnault. With a market capitalization hovering around €400 billion, LVMH’s valuation exceeds the GDP of 20 EU member states. Yet Arnault’s personal fortune—€180 billion at its peak—rests on assets that are largely illiquid: stakes in Louis Vuitton, Dior, and Bulgari, which cannot be easily monetized without diluting brand value. This liquidity mismatch is a defining feature of Europe’s wealth structure, where family-controlled empires coexist with publicly traded giants like ASML (Dutch semiconductor maker) or SAP (German software leader). The Arnault case also highlights Europe’s brand-driven wealth. Unlike tech fortunes tied to volatile stock prices, luxury goods derive value from perceived exclusivity—a model resilient to recessions. Yet this resilience comes at a cost: labor exploitation in supply chains (e.g., Italian leather workshops) and tax avoidance through holding companies in Luxembourg. The 2023 EU Digital Markets Act aims to address the latter, but enforcement will test whether Europe can repatriate wealth without stifling growth."Europe’s wealth is not just about numbers—it’s about control. The families who built these dynasties understand that liquidity is secondary to legacy. They’d rather hold a brand than a bank balance." — Jean-Pierre Mustier, former CEO of BNP Paribas Wealth Management
| Factor | Estimated Impact on Europe’s Net Worth |
|---|---|
| Real Estate (Prime Markets) | €5–7 trillion in combined value; London, Paris, and Munich drive liquidity but face affordability crises. |
| Private Equity & Unlisted Firms | €3–5 trillion in hidden wealth (Germany’s Mittelstand alone); low transparency, high barriers to entry. |
| Luxury & Brand Assets | €1–1.5 trillion in intangible value (LVMH, Richemont, Kering); recession-resistant but vulnerable to geopolitical boycotts. |
| Offshore & Tax Haven Holdings | €1.5–2 trillion estimated; enforcement gaps persist despite EU crackdowns. |
| Digital & Crypto Assets | €100–200 billion; regulatory uncertainty limits institutional adoption. |
What This Means Going Forward
The future of Europe’s europes net worth hinges on three forces: demographics, technology, and geopolitics. An aging population will pressure pension systems, forcing a rethink of how wealth is transferred. Meanwhile, AI and automation threaten traditional wealth-generation sectors (manufacturing, agriculture) while creating new valuation paradigms—think data-driven assets or carbon credits. The EU’s Green Deal could revalue industries overnight, turning polluters into liabilities and renewables into gold mines. Geopolitically, Europe’s europes net worth is increasingly weaponized. Sanctions on Russian oligarchs froze €300 billion in European assets, exposing the continent’s reliance on foreign capital. The U.S. Inflation Reduction Act has lured €50 billion in green tech investments away from Europe, accelerating a brain drain of talent and capital. If Europe fails to retain and repatriate wealth, its financial sovereignty will erode further.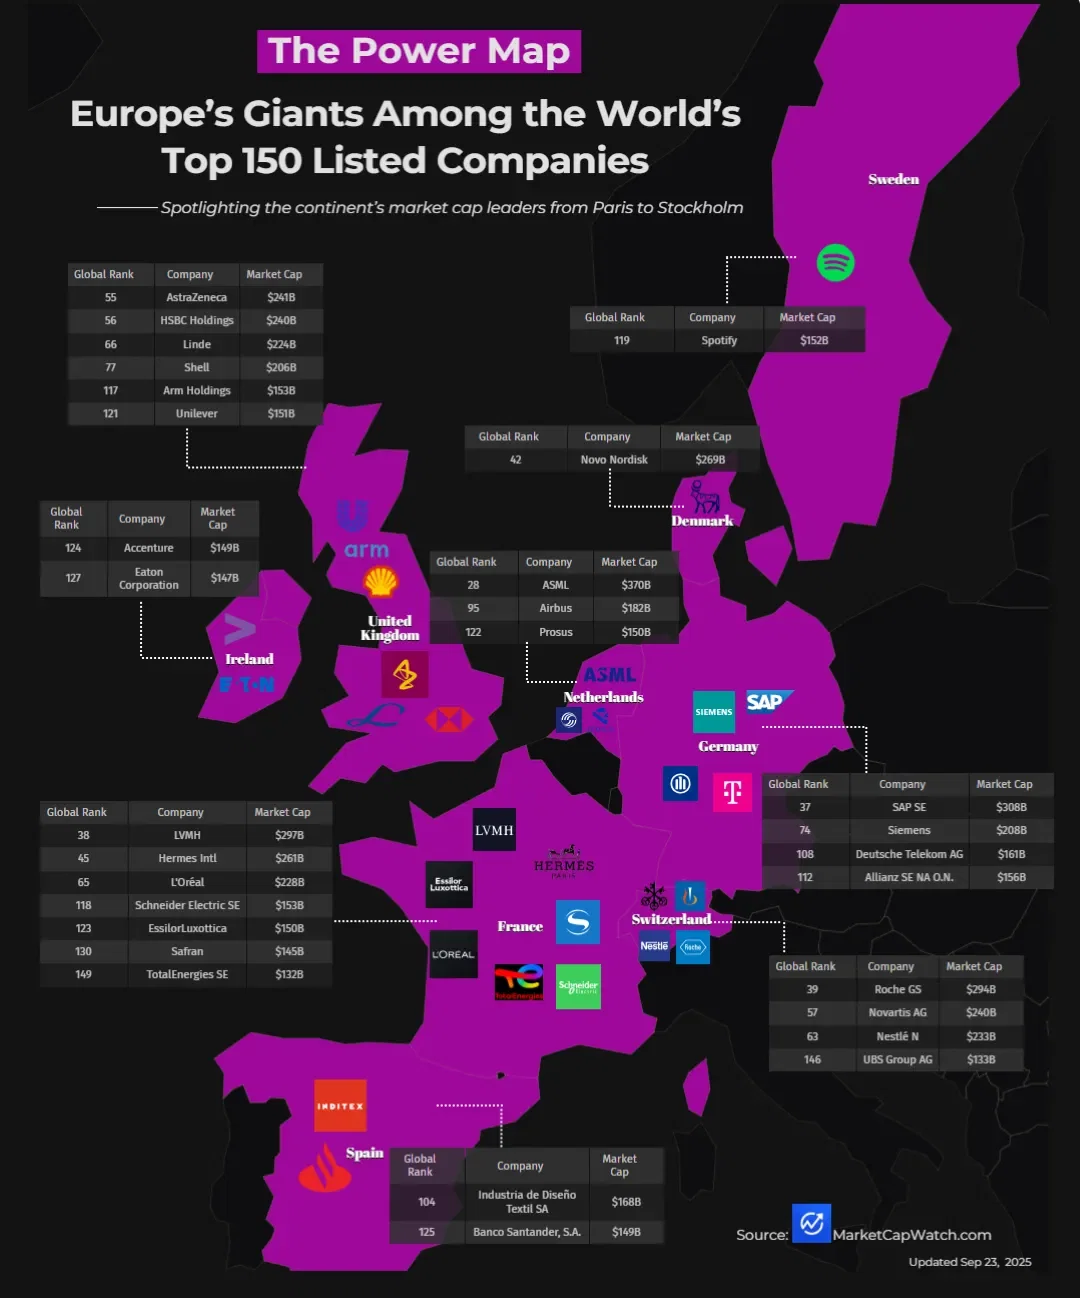
Conclusion
Europe’s europes net worth is a story of contrasts and contradictions: public debt crises coexisting with private opulence, digital innovation alongside analog wealth hoarding. The continent’s strength lies in its diversity of assets—from Swiss francs to Italian vineyards—but its weakness is the lack of cohesion between fiscal policy and private wealth strategies. Without structural reforms, the gap between the wealthy few and the struggling many will widen, risking social instability. The path forward requires transparency without stifling growth, taxation that doesn’t drive capital flight, and innovation that doesn’t leave legacy sectors behind. Whether Europe can navigate these tensions will determine whether its europes net worth remains a source of global influence—or becomes a relic of a bygone era.Comprehensive FAQs
Q: How does Europe’s net worth compare to the U.S.?
The U.S. holds a clear advantage in liquid wealth: its top 1% own 35% of all assets, while Europe’s wealth is more fragmented and tied to illiquid assets (real estate, family businesses). The U.S. also benefits from higher corporate profitability and tech-driven valuation surges, whereas Europe’s wealth is more tradition-bound. However, Europe’s brand and luxury sectors (e.g., LVMH, Richemont) rival U.S. conglomerates in market concentration.
Q: Are there any European countries with negative net worth?
Italy and Greece are the most prominent cases, where public debt exceeds asset values for many households. Italy’s debt-to-GDP ratio (140%) means its europes net worth is effectively negative at the national level, though private wealth (e.g., Ferrari, Prada) offsets some losses. Greece’s post-bailout recovery has improved household balances, but youth unemployment and emigration keep per-capita wealth depressed.
Q: How do tax havens affect Europe’s net worth?
Tax havens inflated Europe’s net worth on paper by allowing wealth to be parked in jurisdictions with lower (or zero) taxation. The Panama Papers estimated €1.5 trillion was held offshore as of 2016—a figure that has likely grown. While the EU’s blacklist of tax havens (e.g., Cayman Islands, Panama) aims to curb this, enforcement remains weak, and legal loopholes (e.g., Luxembourg’s holding companies) persist. The net effect? Wealth is hidden from public view, distorting true europes net worth metrics.
Q: Can Europe’s wealth be accurately measured?
No. Official statistics (GDP, household surveys) exclude unlisted assets, offshore holdings, and intangibles like brand value. The European Central Bank’s wealth data is the most comprehensive, but it still underestimates private equity and real estate. For a true picture, one would need mandatory disclosure of ultra-high-net-worth portfolios—something no EU member state enforces. Thus, Europe’s europes net worth remains a best-guess estimate, not a precise figure.
Q: What’s the biggest threat to Europe’s net worth?
The demographic time bomb: Europe’s aging population will shrink the workforce, reducing tax revenues and increasing pension burdens. Coupled with low birth rates, this could shrink GDP by 10–15% by 2050 (OECD projections). Geopolitical risks (energy dependence, U.S.-China rivalry) and climate-related asset revaluations (e.g., stranded fossil fuel investments) add layers of uncertainty. Unlike the U.S., Europe lacks a unified fiscal policy to mitigate these shocks, making its europes net worth more vulnerable to fragmentation.
