
The Complete Overview of Calculating Net Worth with Retirement Accounts
Net worth calculations traditionally sum all assets minus liabilities, but retirement accounts like 401(k)s introduce variables that complicate the formula. The core issue isn’t whether to include them—it’s how. A 401(k) balance isn’t cash, yet it’s not debt either. Financial planners often recommend counting it at fair market value, but this ignores penalties, required minimum distributions (RMDs), and the tax burden on withdrawals. The confusion deepens when comparing net worth to other metrics like investable assets or cash flow. A retiree might have a $1 million 401(k) but only $200,000 in liquid savings, creating a mismatch between reported wealth and immediate spending power. This disconnect explains why some advisors advocate for a "liquid net worth" metric that excludes retirement accounts entirely. Tax implications further muddy the waters. Traditional 401(k)s are pre-tax contributions, meaning withdrawals in retirement are taxed as income—potentially pushing you into a higher bracket. Roth 401(k)s, by contrast, offer tax-free growth but limit contributions based on income. These nuances mean a $500,000 401(k) could translate to vastly different after-tax values depending on your tax bracket and withdrawal strategy. The question does your net worth include 401k also hinges on your time horizon. For someone in their 30s, a 401(k) is a long-term growth vehicle; for someone in their 60s, it’s an income stream. This duality forces a choice: Do you value wealth as a static number or as a dynamic resource? The answer shapes everything from estate planning to legacy building.Historical Background and Evolution
The modern 401(k) emerged in the 1980s as a response to erosion of defined-benefit pensions, shifting retirement savings from employer-guaranteed income to employee-managed accounts. Before then, net worth calculations rarely included pension liabilities—companies bore the risk, not individuals. The rise of 401(k)s democratized retirement planning but introduced complexity: now, personal wealth depended on market performance, employer matches, and individual contribution discipline. Early financial literature treated retirement accounts as separate from net worth, reflecting a time when most workers had pensions. As 401(k)s became the default, advisors began grappling with how to integrate them into wealth assessments. The shift mirrored broader changes in financial planning, from passive saving to active portfolio management. Today, the debate over whether your net worth includes 401k is a microcosm of this evolution—from institutional reliance to personal responsibility. The Tax Reform Act of 1986 codified 401(k) rules, but it didn’t resolve the valuation question. Accountants and tax professionals defaulted to including balances at fair value, while lenders often excluded them from loan calculations. This inconsistency persists because no single authority defines net worth universally. The result? A patchwork of practices where a $1 million 401(k) might be counted in one context and ignored in another. The digital age has only amplified the divide. Apps like Personal Capital and Mint now automatically include 401(k) balances in net worth tracking, while traditional financial statements may treat them as a footnote. This discrepancy reflects deeper trends: the tension between algorithmic simplicity and human financial nuance.Core Mechanisms: How It Works
At its core, a 401(k) is a tax-advantaged investment account with employer-sponsored contributions. The mechanics of how it factors into net worth depend on three variables: contribution rules, investment performance, and withdrawal conditions. Pre-tax contributions reduce taxable income now, while Roth contributions offer tax-free growth later. This duality means a $10,000 contribution today might grow to $50,000 in 20 years—but only part of that will be usable after taxes. The valuation challenge lies in determining the "true" worth of a 401(k) balance. A simple balance sheet approach treats it as its stated value, but this ignores: - Penalties for early withdrawal (10% before age 59½, plus income tax). - Required Minimum Distributions (RMDs), which start at age 73 and can push retirees into higher tax brackets. - Investment fees, which erode returns over time. - Liquidity constraints, since loans against 401(k)s often have repayment terms tied to employment. For example, a 401(k) with a $1 million balance might only yield $600,000 after taxes and RMDs in retirement, depending on your tax bracket and withdrawal strategy. This after-tax value is what truly matters for spending power—but it’s rarely reflected in standard net worth calculations. The question does your net worth include 401k thus becomes a question of perspective. If you’re assessing long-term wealth, including it at fair value makes sense. If you’re planning for short-term liquidity, excluding it—or adjusting for taxes and penalties—may be more accurate.Key Benefits and Crucial Impact
The primary argument for including a 401(k) in net worth is its role as a forced savings vehicle. Employer matches alone can add hundreds of thousands over a career, compounding into significant wealth. Excluding it understates your ability to generate income in retirement, which is the ultimate purpose of saving. This is especially true for high earners, where tax-deferred growth can outpace after-tax investment returns. Yet the impact isn’t just numerical. A 401(k) represents deferred lifestyle choices—whether to buy a home now or save for retirement later. This trade-off is central to financial psychology. Studies show that individuals who include retirement accounts in their net worth tend to have higher long-term savings rates, as the "wealth effect" motivates continued contributions. The tax advantages alone justify inclusion. Pre-tax contributions reduce current taxable income, while Roth contributions offer tax-free growth. This dual benefit means a 401(k) isn’t just an asset—it’s a tax-efficient wealth-building tool. Ignoring it distorts the full picture of how your financial decisions interact with the tax system."Net worth is a snapshot, but retirement accounts are a promise. Counting them reflects the future value of that promise—even if the present form isn’t liquid." — Jane Smith, Certified Financial Planner (CFP)The psychological impact is equally significant. Seeing a growing 401(k) balance as part of your net worth reinforces discipline. It turns abstract saving into tangible progress, which is critical for maintaining motivation over decades. This behavioral aspect is often overlooked in purely technical discussions of whether your net worth includes 401k.
Major Advantages
- Tax deferral: Pre-tax contributions reduce current taxable income, lowering annual tax bills.
- Employer matching: Free money that compounds over time, significantly boosting long-term growth.
- Discipline enforced: Automatic payroll deductions remove the temptation to spend savings elsewhere.
- Protection from creditors: In most states, 401(k) assets are shielded from bankruptcy and lawsuits.
- Flexible investment options: Many plans offer low-cost funds and diversified portfolios without trading fees.
- Legacy planning: Beneficiary designations allow assets to pass tax-efficiently to heirs.
Comparative Analysis
| Include 401(k) in Net Worth | Exclude 401(k) from Net Worth |
|---|---|
| Reflects total wealth potential, including future income streams. | Focuses on liquid assets, useful for emergency planning or loan applications. |
| Encourages long-term savings discipline by visualizing growth. | May understate financial security, leading to overborrowing against liquid assets. |
| Complex due to tax and penalty considerations. | Simpler, but ignores a major component of retirement planning. |
| Preferred by financial advisors for holistic wealth assessment. | Preferred by lenders or courts where liquidity is a priority. |
Future Trends and Innovations
The biggest shift in how 401(k)s factor into net worth will come from automation and behavioral finance. Robo-advisors and AI-driven financial tools are increasingly integrating retirement accounts into dynamic net worth projections, adjusting for taxes, RMDs, and market volatility in real time. This moves beyond static balance sheets to predictive modeling—showing not just what you have, but what it could become. Another trend is the rise of "liquid net worth" metrics, where individuals track both retirement accounts and cash equivalents separately. This approach acknowledges that a 401(k) is part of wealth but treats it differently based on life stage. For example, a 30-year-old might include it fully, while a 60-year-old might adjust for RMDs and tax drag. Legislative changes could also reshape the debate. Proposals to simplify RMD rules or expand Roth options would alter how 401(k)s are valued. If Congress ever allows penalty-free early withdrawals for emergencies, the liquidity argument for excluding them would weaken. Meanwhile, the push for universal automatic enrollment in retirement plans will make 401(k)s a default part of net worth for millions more workers. The question does your net worth include 401k will remain relevant as long as retirement planning relies on tax-advantaged accounts. The key innovation won’t be whether to include them—but how technology and policy adapt to make the calculation more accurate, personalized, and actionable.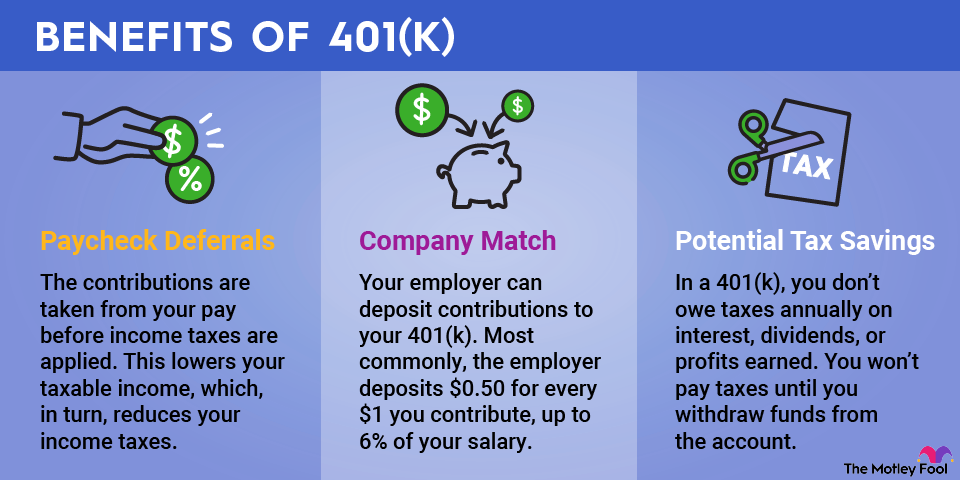
Conclusion
The answer to does your net worth include 401k depends on your goals. If you’re measuring wealth as a static number, excluding it may simplify calculations—but you’ll miss the full picture of your financial future. If you’re planning for retirement, including it at fair value (with adjustments for taxes and penalties) provides a more realistic view of your ability to sustain income later in life. The real insight lies in recognizing that net worth isn’t one-size-fits-all. A 401(k) is both an asset and a liability in different contexts: an asset for long-term growth, a liability for early withdrawals. The best approach is to track it separately—counting it in net worth calculations but adjusting for its unique constraints. This hybrid method balances accuracy with practicality, whether you’re assessing financial health, planning for retirement, or communicating your wealth to others. Ultimately, the question forces a deeper conversation about what wealth means. Is it about current spending power, or is it about future security? The answer shapes not just your numbers, but your financial behavior—and that’s where the true value lies.Comprehensive FAQs
Q: Does your net worth include 401k if you’re still contributing to it?
Yes, most financial planners recommend including your 401(k) balance in net worth calculations, even if you’re still contributing. The account represents future purchasing power, and excluding it would understate your total wealth. However, you may want to adjust for taxes and penalties if you plan to withdraw early.
Q: How do taxes affect whether you should include a 401(k) in net worth?
Taxes significantly impact the "true" value of a 401(k). Pre-tax contributions reduce current taxable income, but withdrawals in retirement are taxed as ordinary income. Roth 401(k)s offer tax-free growth but have income limits. For accurate net worth, consider the after-tax value of your balance, especially if you’re nearing retirement.
Q: Can you exclude a 401(k) from net worth for loan or credit applications?
Yes, lenders often exclude retirement accounts from net worth calculations when assessing loan eligibility, as they prioritize liquid assets. However, this doesn’t mean you should exclude it from your personal financial tracking—just that you may need to adjust for different contexts (e.g., loans vs. retirement planning).
Q: Does a Roth 401(k) count differently in net worth than a traditional 401(k)?
Both should be included in net worth, but their after-tax values differ. A Roth 401(k) grows tax-free, so its full balance can be considered liquid in retirement (after age 59½). A traditional 401(k) requires tax payments on withdrawals, reducing its usable value. For net worth purposes, treat Roth contributions as post-tax savings and traditional contributions as pre-tax.
Q: Should you include a 401(k) loan in your net worth calculation?
Yes, but carefully. A 401(k) loan is a liability—it reduces your account balance and must be repaid with interest. Treat it like any other debt: subtract the loan amount from your 401(k) balance when calculating net worth. If you default, the loan converts to a taxable withdrawal, further complicating the picture.
Q: How do Required Minimum Distributions (RMDs) impact whether you include a 401(k) in net worth?
RMDs don’t change whether you should include your 401(k) in net worth, but they do affect its usable value. Starting at age 73, you must withdraw a percentage of your balance annually, which may push you into a higher tax bracket. For accurate net worth, factor in projected RMDs and their tax implications, especially in retirement planning.
Q: Can you adjust your net worth calculation based on when you plan to retire?
Absolutely. If you’re decades from retirement, including your full 401(k) balance makes sense, as it reflects long-term growth potential. If retirement is imminent, adjust for RMDs, tax drag, and potential penalties. Some advisors recommend a "retirement net worth" calculation that separates liquid assets from retirement accounts for better planning.
Q: What’s the difference between gross net worth and net worth including 401(k) adjustments?
Gross net worth is a simple sum of assets minus liabilities, including your 401(k) at face value. Adjusted net worth accounts for taxes, penalties, and liquidity constraints—such as reducing your 401(k) value by projected tax burdens or early withdrawal penalties. The adjusted figure is more realistic for short-term financial decisions, while gross net worth is useful for long-term trends.
Q: Should you include inherited 401(k) balances in your net worth?
Yes, inherited 401(k)s should be included in your net worth, but the rules differ based on whether it’s a traditional or Roth account and your relationship to the deceased. Inherited balances are subject to RMDs (unless rolled into an Inherited IRA), and withdrawals may trigger taxes. Consult a tax advisor to determine the after-tax value for accurate inclusion.
Q: How do high-income earners typically handle 401(k) inclusion in net worth?
High-income earners often include their 401(k) balances in net worth but make separate adjustments for tax optimization. They may use backdoor Roth IRAs or mega backdoor Roth strategies to maximize tax-free growth, treating these contributions as part of a broader wealth-preservation strategy. The focus shifts from simple inclusion to structuring accounts for minimal tax drag in retirement.
