The Complete Overview of Accredited Investor Net Worth and Real Estate
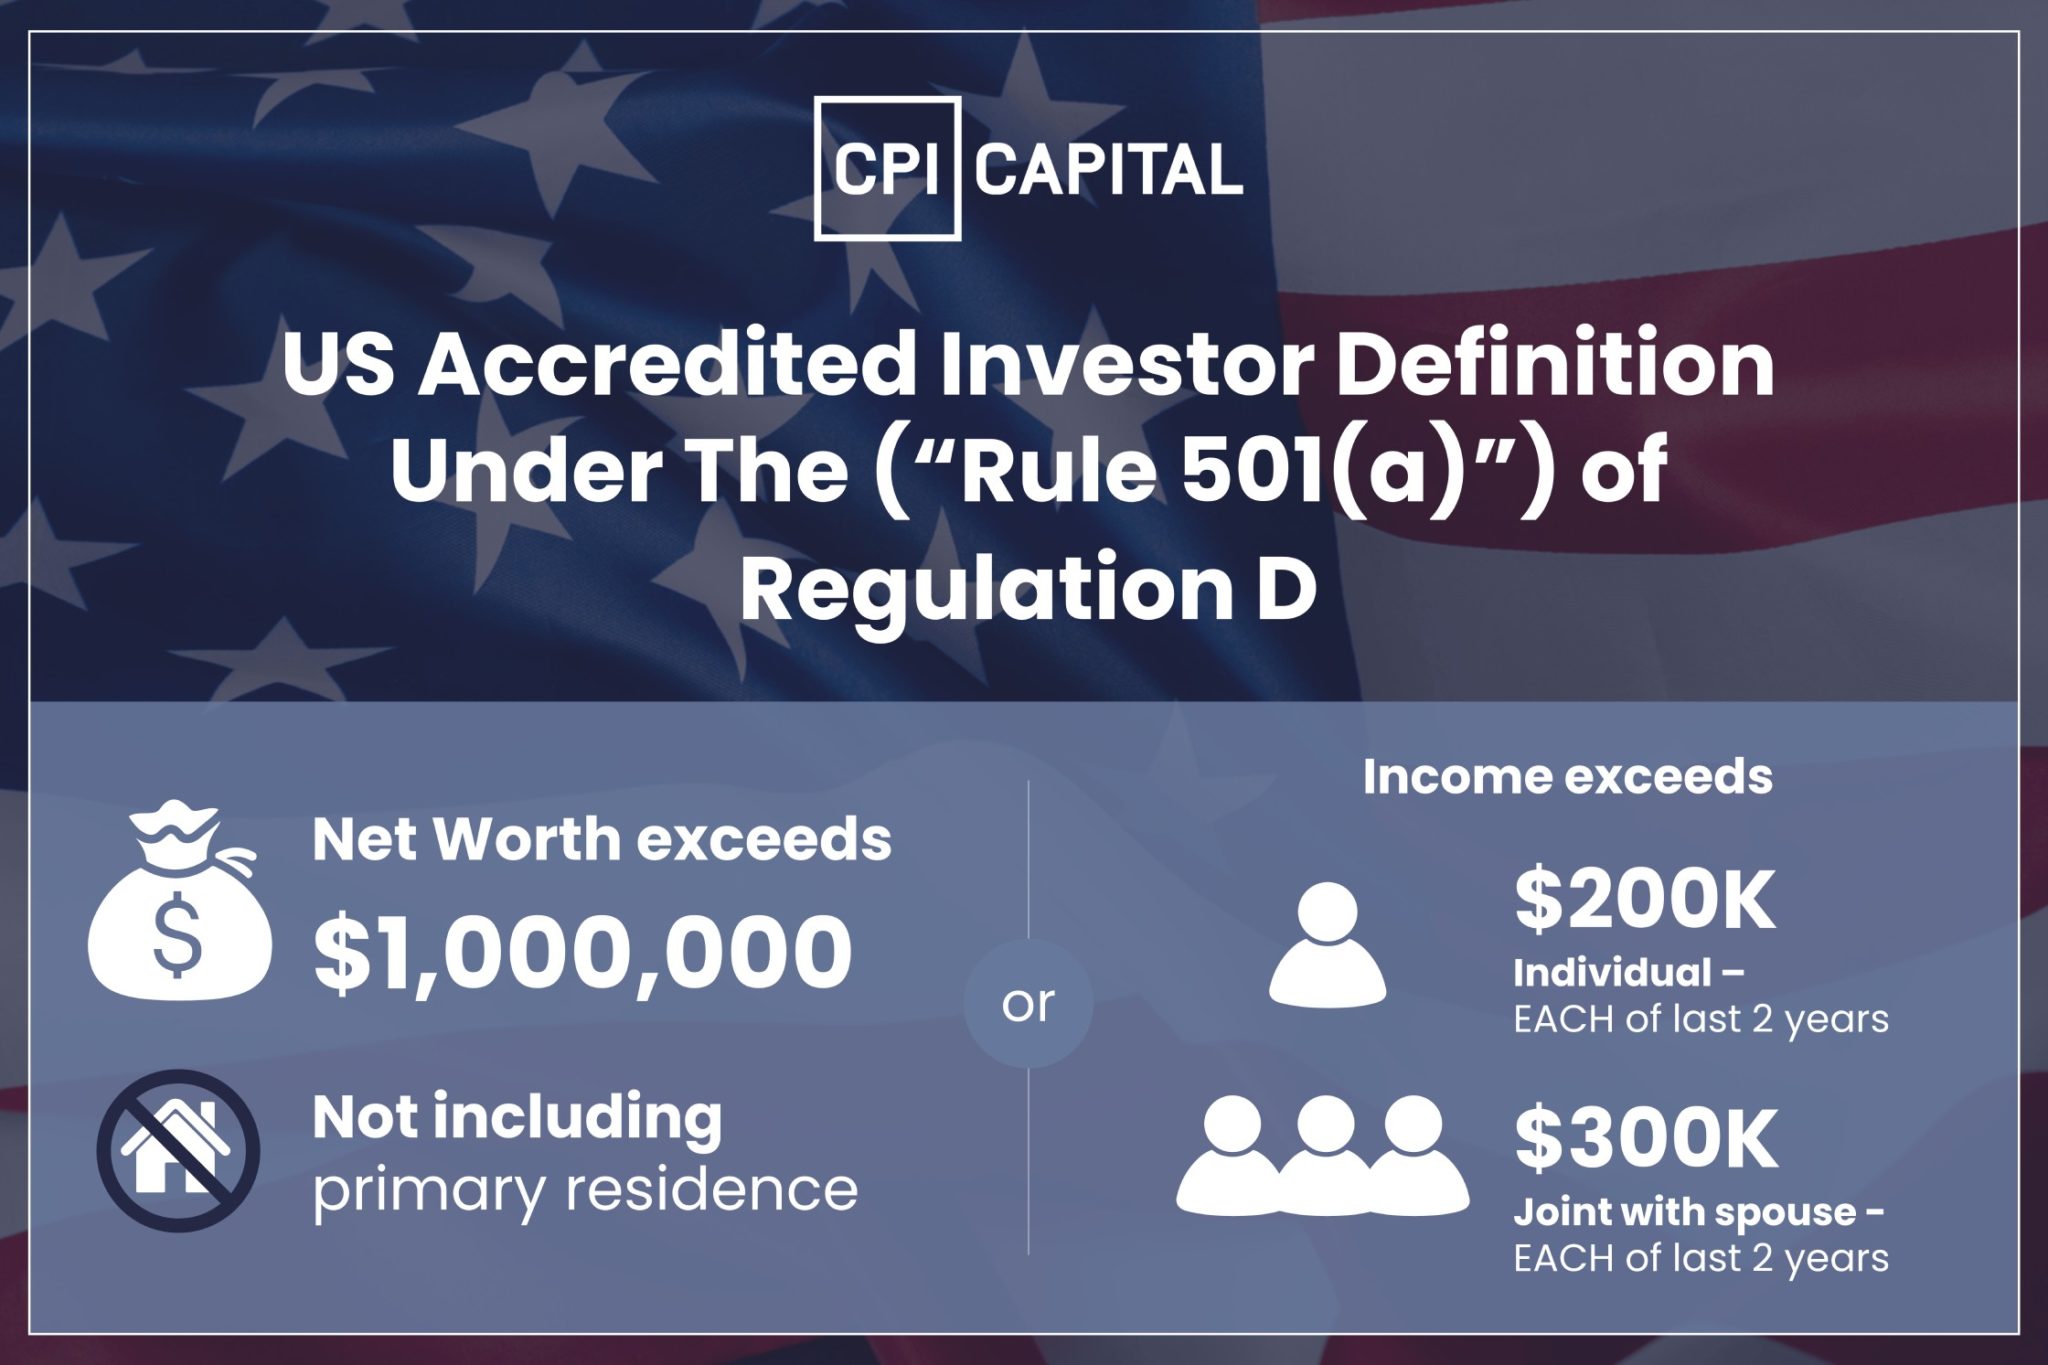
The net worth definition for accredited investors under Regulation D of the Securities Act is deceptively simple: an individual must have a net worth of at least $1 million (excluding the value of their primary residence) or earn $200,000 annually for the prior two years (or $300,000 jointly with a spouse). Where the complexity lies is in the exclusion of the primary residence. The SEC’s intent was to prevent individuals from inflating their net worth by leveraging home equity, but the definition doesn’t specify how secondary properties—such as vacation homes, investment rentals, or second residences—should be treated. The lack of clarity has led to inconsistent practices across the financial industry. Some firms adopt a conservative approach, excluding all non-primary residences from net worth calculations, while others include them at full appraised value. This inconsistency becomes particularly problematic when investors apply for multiple funds or platforms within a short timeframe. A single miscalculation could result in disqualification, even if the investor meets the threshold when all assets are properly accounted for. The issue is further complicated by the fact that many high-net-worth individuals hold real estate in complex structures, such as family limited partnerships or trusts, which may not appear on personal financial statements.Historical Background and Evolution
The concept of accredited investors emerged in the 1980s as a way to streamline securities offerings for sophisticated investors while protecting retail investors from high-risk, illiquid assets. The SEC’s original rationale was that individuals with significant net worth or income were better equipped to evaluate and absorb the risks of private investments. Over time, the definition evolved to exclude primary residences, reflecting a concern that home equity could be artificially inflated through leverage or market fluctuations. However, the SEC’s rules have not kept pace with the diversification of high-net-worth portfolios. In the 1990s and 2000s, as real estate became a dominant asset class for wealthy individuals, the question of whether vacation properties should be included in net worth calculations became more pressing. The Dodd-Frank Act of 2010 introduced some reforms, but it did not address this specific issue. As a result, the burden of interpretation has fallen to financial advisors, compliance officers, and—frequently—individual investors themselves.Core Mechanisms: How It Works
At its core, the net worth calculation for accredited investor status is a balance sheet exercise. An individual’s total assets (cash, securities, real estate, etc.) minus total liabilities (mortgages, loans, credit card debt) must meet or exceed $1 million. The critical exclusion is the primary residence, which is not counted toward net worth—even if it’s heavily leveraged. This exclusion was designed to prevent individuals from using home equity to artificially meet the threshold. The challenge arises when determining whether a vacation property qualifies as a primary residence. The SEC does not provide explicit guidance, but industry practice suggests that a property used as a principal dwelling—where the individual spends the majority of their time—would be excluded. A secondary home, timeshare, or investment property, however, would typically be included in net worth calculations. This distinction is subjective and often depends on how the property is used, documented, and reported in financial disclosures.Key Benefits and Crucial Impact
Accredited investor status unlocks access to a broad range of investment opportunities that are otherwise restricted to institutional players. These include private equity funds, hedge funds, real estate syndications, and startup equity crowdfunding platforms. For high-net-worth individuals, this access can translate into higher returns, diversification, and exposure to emerging sectors before they hit public markets. However, the benefits are contingent on accurate and transparent reporting of net worth—including how real estate assets are classified. The impact of misclassifying a vacation property extends beyond missed opportunities. It can also trigger regulatory red flags, particularly if an investor is flagged for inconsistent disclosures across multiple platforms. Some firms conduct due diligence that includes verifying asset ownership through title searches or tax filings, which can expose discrepancies. In extreme cases, repeated misclassifications could lead to enforcement actions, though such instances are rare for individual investors."Accredited investor status is not just about meeting a numerical threshold—it’s about demonstrating financial sophistication and risk tolerance. The SEC’s rules are designed to protect investors, but they also create a gray area when it comes to real estate. A vacation home might be worth millions, but if it’s not properly accounted for, it could disqualify an investor from the very opportunities they’re trying to access." — Compliance Officer, Mid-Atlantic Private Equity Firm
Major Advantages
- Access to exclusive investments: Private equity, venture capital, and real estate funds often require accredited investor status, offering higher potential returns than public markets.
- Diversification opportunities: High-net-worth individuals can invest in sectors like biotech, renewable energy, or commercial real estate that are typically off-limits to retail investors.
- Tax advantages: Some private investments, such as opportunity zones or qualified small business stock, offer tax deferrals or exemptions available only to accredited investors.
- Networking and deal flow: Participation in accredited investor circles often provides early access to deals and connections with industry leaders.
- Leverage for larger deals: Meeting the net worth threshold can enable individuals to invest in high-ticket opportunities, such as commercial real estate or angel investments.
Comparative Analysis
| Primary Residence | Vacation Property |
|---|---|
| Excluded from net worth calculation under SEC rules. | Included at full appraised value unless classified as a primary residence. |
| Debt (e.g., mortgage) is not deducted from net worth. | Debt (e.g., vacation home mortgage) is deducted from the property’s value in net worth calculations. |
| Subjective determination based on usage (e.g., primary dwelling). | Typically included unless used as a principal residence or held in a structure that obscures ownership. |
Future Trends and Innovations
As the SEC continues to modernize its regulations, the treatment of real estate in accredited investor definitions may evolve. One potential shift could involve clearer guidance on how secondary properties should be valued, particularly in light of the rise of fractional ownership and digital assets. Additionally, the growing use of alternative data—such as rental income, property management records, and blockchain-based ownership—could provide more transparency in net worth assessments. Another trend is the increasing reliance on third-party verification services to confirm accredited investor status. These services aggregate financial data from multiple sources, reducing the risk of misclassification. However, they also raise privacy concerns and may not fully account for complex real estate holdings. As the financial industry becomes more data-driven, the question of whether vacation properties should be included in net worth calculations may become less about interpretation and more about standardized reporting.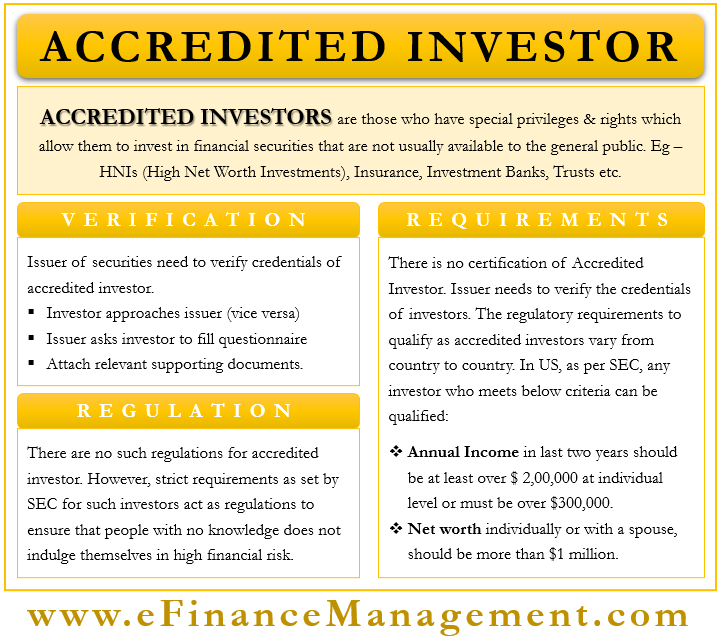
Conclusion
The question of whether a vacation property counts toward the net worth definition of an accredited investor is not just a technicality—it’s a critical factor in determining access to high-stakes investment opportunities. While the SEC’s rules provide a framework, the lack of explicit guidance on secondary properties leaves room for inconsistency and potential missteps. Investors must carefully document their real estate holdings, consult financial advisors, and understand how their properties are classified in net worth calculations. For those with significant real estate assets, the key takeaway is to err on the side of transparency. If a vacation property is a material part of one’s wealth, it should be included in accredited investor disclosures unless it clearly qualifies as a primary residence. The alternative—underreporting—risks disqualification from lucrative opportunities and could draw unwanted attention from regulators. As the investment landscape continues to evolve, so too will the standards for what constitutes net worth. Staying ahead of these changes will be essential for high-net-worth individuals seeking to maximize their investment potential.Comprehensive FAQs
Q: If I own a vacation home in a trust, does it count toward my accredited investor net worth?
A: It depends on how the trust is structured and whether the property’s value is reflected in your personal financial statements. If the trust is a revocable living trust or a pass-through entity, the property’s value may be included in your net worth. Irrevocable trusts or LLCs may obscure ownership, but some firms will still require verification through tax filings or other documentation.
Q: Can I exclude a vacation home if I spend more time there than at my primary residence?
A: The SEC does not provide explicit criteria for determining a "primary residence," but industry practice suggests that a property used as a principal dwelling—where you maintain legal residency, pay taxes, and spend the majority of your time—would be excluded. However, this is subjective, and firms may require additional documentation, such as utility bills or voter registration records, to verify usage.
Q: Does the value of a vacation home include outstanding mortgage debt in the net worth calculation?
A: Yes. Net worth is calculated as total assets minus total liabilities. If you have a mortgage on your vacation property, the outstanding balance is deducted from the property’s appraised value before including it in your net worth. This is different from a primary residence, which is excluded in full regardless of debt.
Q: What happens if I misclassify a vacation property and it’s later discovered?
A: Misclassification could result in disqualification from investment opportunities, and in some cases, it may trigger regulatory scrutiny if the discrepancy is significant or repeated. While enforcement actions against individual investors are rare, firms may impose penalties, such as revoking access to future offerings or requiring additional disclosures. It’s always best to consult a financial advisor or compliance professional to ensure accurate reporting.
Q: Are there any exceptions or special cases where a vacation property might be excluded?
A: The only clear exception is if the property is classified as a primary residence. Beyond that, there are no formal exceptions for vacation homes, timeshares, or investment properties. However, some firms may adopt a more lenient approach if the property is held in a structure that complicates valuation, such as a foreign entity or a complex trust. Always verify a firm’s specific policies before applying.
