The Complete Overview of How Real Estate Fits Into Net Worth
Net worth is the arithmetic of assets minus liabilities, but real estate complicates that equation. The question does net worth include real estate isn’t binary—it’s contextual. A primary residence might be included at its current market value, but only if that value exceeds the mortgage balance. A rental property, meanwhile, could be split between its equity and its income-generating potential. The key variable isn’t whether real estate should be included, but how it’s measured. Industry standards dictate that properties are typically valued at fair market price, but appraisals, tax assessments, and investor projections can diverge wildly. For example, a luxury condo in a gentrifying neighborhood might appraise at $2 million, but its tax-assessed value could be frozen at $1.5 million—a discrepancy that directly impacts net worth calculations for wealth tracking or inheritance purposes. The confusion deepens when considering different property types. Raw land, for instance, might be listed at its highest and best use value, while a distressed property could require a forced-sale discount. Even the method of financing plays a role: an owner-occupied home with a low-interest mortgage may hold more net-worth value than a rental property burdened by high debt. Financial advisors often warn against overvaluing real estate in net worth statements, particularly in volatile markets where liquidity risks loom. The bottom line? Real estate does belong in net worth calculations, but its inclusion demands precision—because a misstep here can distort financial reality by hundreds of thousands, if not millions.Historical Background and Evolution
The modern concept of net worth as a financial metric emerged alongside the rise of personal credit and property ownership in the 19th century. Before then, wealth was often measured in landholdings and livestock—tangible assets that required no complex calculations. As urbanization accelerated, the value of real estate became a proxy for financial stability, especially in societies where homeownership was (and remains) a cornerstone of middle-class identity. By the early 20th century, banks and lenders began standardizing property valuations to assess loan risk, embedding real estate firmly into net worth frameworks. The Great Depression forced a reckoning: when property values collapsed, so did net worth calculations, proving that real estate wasn’t just an asset—it was a volatile one. Today, the inclusion of real estate in net worth reflects broader economic shifts. The post-World War II housing boom cemented property as a default wealth-building tool, while the 2008 financial crisis exposed the dangers of overleveraging. Regulators and accountants now distinguish between "hard" assets (like cash or stocks) and "soft" assets (like real estate), where liquidity and market timing introduce uncertainty. High-net-worth individuals often face pressure to diversify away from property-heavy portfolios, as institutional investors prioritize liquidity. Yet for many, real estate remains the largest component of net worth—particularly in countries like the U.S., Canada, and Australia, where homeownership rates exceed 60%. The question does net worth include real estate thus isn’t just technical; it’s a reflection of how societies balance security against speculation.Core Mechanisms: How It Works
At its core, net worth is calculated by subtracting liabilities from assets. When real estate enters the equation, the process becomes twofold: first, determining the property’s value, and second, accounting for any debt attached to it. For a primary residence, most personal finance tools will subtract the remaining mortgage balance from the home’s appraised value to arrive at equity—a figure that then contributes to net worth. Rental properties, however, may be valued differently depending on whether they’re held for income or appreciation. Some wealth trackers use a conservative approach, deducting all debt and treating the property as a long-term holding, while others factor in potential rental income to justify a higher valuation. The method of valuation is critical. Appraisals, tax assessments, and Zillow’s Zestimates can all yield different numbers, and choosing the wrong one can skew net worth by 10% or more. For example, a property in a high-tax state might be assessed below market value to reduce property taxes, but that lower figure could understate its true contribution to net worth. Similarly, investment properties might be valued based on capitalization rates (the ratio of net operating income to property value), which can fluctuate with interest rates. The Internal Revenue Service (IRS) provides guidelines for reporting property values, but even these allow for discretion—particularly when dealing with inherited properties or those held in trusts. The bottom line? Does net worth include real estate? Absolutely, but the inclusion hinges on accurate, context-specific valuations.Key Benefits and Crucial Impact
Real estate’s role in net worth extends beyond simple arithmetic—it shapes financial behavior, tax strategies, and even personal freedom. For homeowners, a rising property value can act as a forced savings mechanism, building equity over time without active effort. Investors, meanwhile, leverage real estate to hedge against inflation, diversify portfolios, or generate passive income. The psychological impact is equally significant: owning property often correlates with perceived stability, even if the asset itself is illiquid. Yet this duality creates tension. A home’s equity might boost net worth on paper, but selling to access that cash can trigger capital gains taxes or disrupt living arrangements. The trade-off between liquidity and asset growth is a perennial challenge for those who rely on real estate as their primary wealth vehicle. The tax implications further complicate the picture. Primary residences benefit from capital gains exemptions (up to $250,000 for individuals, $500,000 for couples in the U.S.), but rental properties are subject to depreciation rules, 1031 exchanges, and passive activity loss limitations. High-net-worth individuals often structure property holdings through LLCs or trusts to manage tax burdens, but these strategies add layers of complexity to net worth calculations. The result? Real estate isn’t just an asset—it’s a financial ecosystem with its own rules, risks, and rewards."Real estate may be the world’s best performing asset class over time, but it’s also the most personal. Your net worth isn’t just numbers—it’s the story of how you’ve turned bricks and mortar into security, or sometimes, into a liability." — Robert Kiyosaki (adapted from Rich Dad Poor Dad)
Major Advantages
- Forced appreciation: Unlike stocks or bonds, real estate often gains value through inflation and local demand, even without active management.
- Leverage potential: Mortgages allow investors to control high-value assets with a fraction of the purchase price, amplifying returns (or losses).
- Tax benefits: Deductions for mortgage interest, property taxes, depreciation, and capital gains exemptions can significantly reduce taxable income.
- Hedge against volatility: Physical assets like land or rental properties tend to hold value better than paper assets during market downturns.
- Generational wealth: Property can be passed down with stepped-up basis (avoiding inheritance taxes in many jurisdictions), preserving wealth across families.

Comparative Analysis
| Primary Residence | Investment Property |
|---|---|
| Valued at market price minus mortgage balance. Tax exemptions apply to capital gains. | Valued based on income potential (cap rate) or comparable sales. Subject to depreciation and passive income rules. |
| Liquidity risk: Low (hard to sell quickly without penalty). | Liquidity risk: Moderate (depends on rental market and financing). |
| Net worth impact: Directly increases equity over time. | Net worth impact: Can fluctuate with rental demand and maintenance costs. |
| Tax strategy: Focus on mortgage interest deductions and principal reduction. | Tax strategy: Utilize 1031 exchanges, depreciation, and entity structuring (LLCs, trusts). |
Future Trends and Innovations
The relationship between real estate and net worth is evolving alongside technological and economic shifts. Proptech innovations—like AI-driven valuations, blockchain-based property records, and fractional ownership platforms—are making it easier to track and trade real estate assets, potentially increasing their liquidity. However, these tools also introduce new risks, such as algorithmic bias in appraisals or cybersecurity threats to digital property titles. Meanwhile, remote work trends are reshaping property values, with urban centers seeing declines in demand for office spaces while suburban and rural markets boom. The rise of co-living and co-working spaces further complicates net worth calculations, as individuals may hold partial ownership in shared assets. Regulatory changes will also play a critical role. Governments are increasingly scrutinizing property markets to curb speculation, with some jurisdictions imposing vacancy taxes or limiting short-term rentals. For high-net-worth families, estate planning will need to adapt to new rules around inherited property valuations and digital asset integration. The question does net worth include real estate will remain relevant, but the answer may soon depend on whether properties are held in traditional forms or as tokenized assets on blockchain platforms. One thing is certain: real estate’s role in net worth won’t disappear—it will simply become more dynamic, demanding even greater precision in valuation and strategy.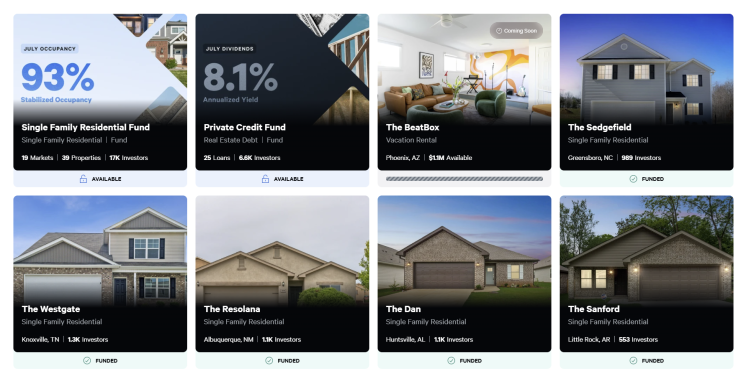
Conclusion
Real estate’s place in net worth calculations is neither simple nor static. It’s the asset class that blurs the line between security and speculation, between liquidity and leverage. The answer to does net worth include real estate is yes—but with critical caveats. Primary residences, rental portfolios, and undeveloped land all contribute differently, and their values must be assessed with an eye toward market realities, tax implications, and personal financial goals. Ignoring these nuances can lead to overinflated perceptions of wealth or, worse, financial blind spots that emerge only during crises. For individuals, the takeaway is clarity: track property values regularly, distinguish between equity and market hype, and align real estate holdings with broader wealth objectives. For advisors, it’s a reminder that net worth isn’t just a number—it’s a living document shaped by the assets you choose to hold, and how you choose to value them. In an era of rising home prices and record debt levels, understanding the true role of real estate in net worth has never been more urgent.Comprehensive FAQs
Q: Does net worth include real estate if the property is mortgaged?
A: Yes, but only the equity portion. Subtract the remaining mortgage balance from the property’s current market value to determine its net contribution to your net worth. For example, a home worth $500,000 with a $300,000 mortgage adds $200,000 to net worth.
Q: How often should I update real estate values in my net worth statement?
A: At least annually, or more frequently in volatile markets. Use professional appraisals for high-value properties or significant transactions (e.g., refinancing, selling). Online estimates (like Zillow) can provide a rough guide but may lack accuracy for unique properties.
Q: Does net worth include real estate held in a trust or LLC?
A: Yes, but the valuation method may differ. Trusts and LLCs require separate financial statements, and property values should reflect the entity’s ownership stake. Consult a CPA or estate planner to ensure compliance with tax and reporting rules.
Q: What if my property’s value drops below my mortgage balance?
A: This is called being "underwater," and it reduces your net worth by the full amount of the negative equity. For example, a home worth $250,000 with a $300,000 mortgage subtracts $50,000 from your net worth. This scenario is common in distressed markets and can limit refinancing options.
Q: Should I include land without improvements in my net worth?
A: Absolutely, but its value depends on highest and best use. Vacant land is typically valued based on zoning potential (residential, commercial, agricultural) or comparable sales. Raw land may hold speculative value, so conservative valuations are advisable unless you have a clear development plan.
Q: Does net worth include real estate if it’s part of a business (e.g., a rental empire)?
A: Yes, but it’s treated as a business asset rather than a personal one. The property’s value is offset by liabilities (mortgages, operational costs) and may be subject to depreciation for tax purposes. Business real estate is often valued using income-capitalization approaches rather than comparable sales.
Q: How do capital gains taxes affect real estate’s role in net worth?
A: Primary residences qualify for capital gains exemptions (up to $250K/$500K in the U.S.), but investment properties trigger taxes on profits at sale. This reduces net worth at tax time. Strategies like 1031 exchanges (deferring gains by reinvesting in like-kind property) can mitigate this impact for investors.
Q: Can I exclude real estate from net worth calculations for privacy reasons?
A: Yes, but it’s not recommended for accurate financial planning. Excluding property values can lead to misjudged loan applications, insurance needs, or estate distributions. If privacy is a concern, work with a fiduciary advisor to anonymize valuations while maintaining transparency.
