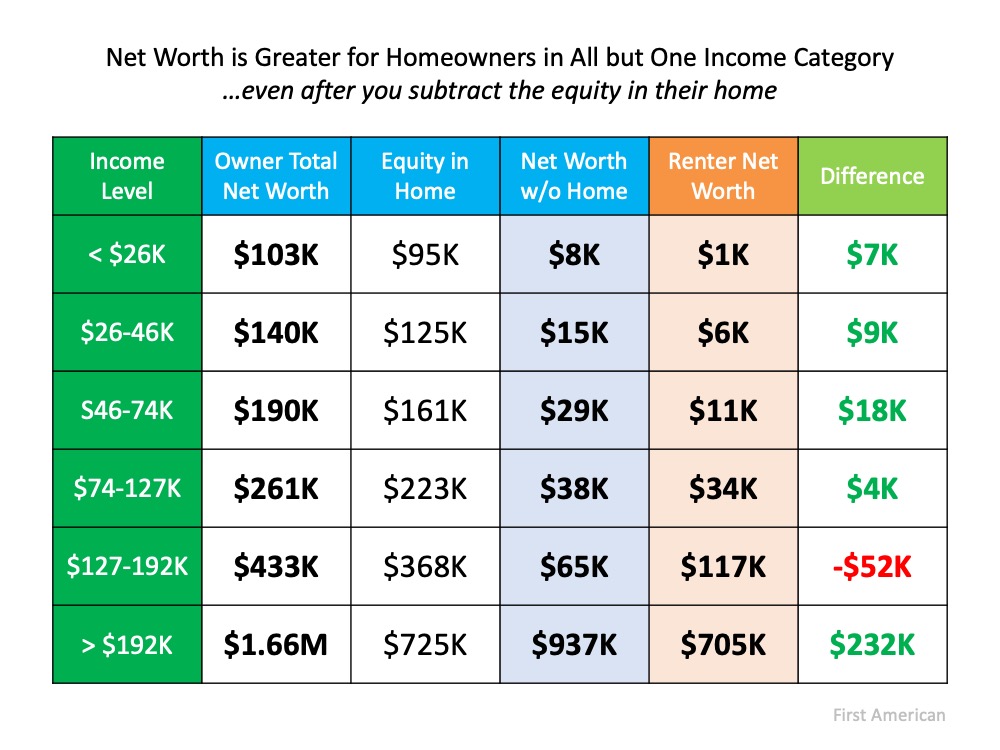
The Complete Overview of Home Equity in Net Worth
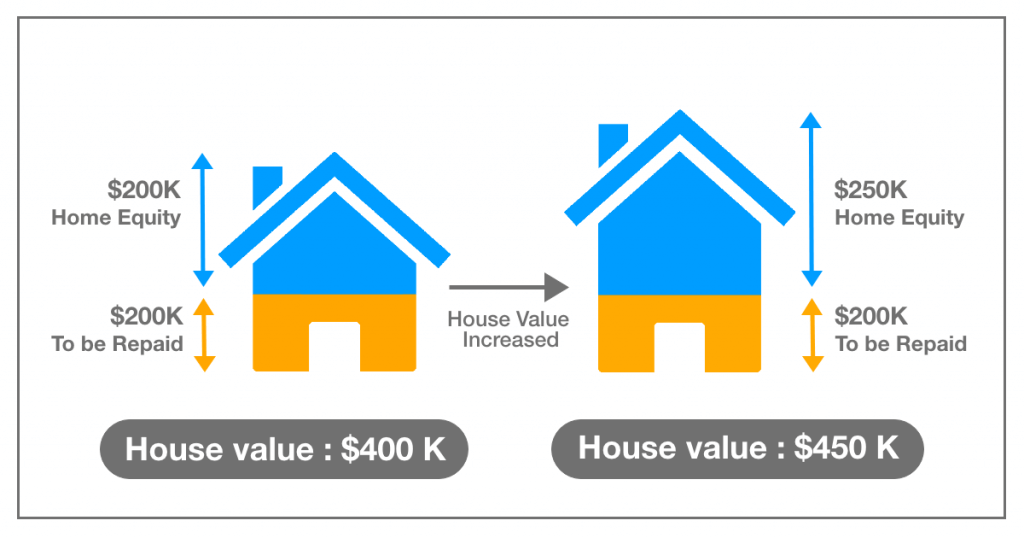
The inclusion of home equity in net worth hinges on two foundational principles: accounting conventions and purpose. In personal finance, net worth is typically defined as total assets minus liabilities. Under this framework, home equity—calculated as market value minus mortgage balance—qualifies as an asset. However, the treatment diverges when examining realizable value versus theoretical value. A 2022 study by the Urban Institute revealed that 45% of homeowners underestimate their equity by at least 20% due to outdated property valuations or overlooked refinancing opportunities. This discrepancy can skew net worth perceptions, especially in volatile markets where home values fluctuate. Yet the question "does net worth include equity in home" becomes more nuanced when considering liquidity constraints. While equity is an asset, converting it into spendable cash often requires selling the property or taking on additional debt—processes that incur transaction costs (6%+ in agent fees, closing costs, or refinancing penalties). For this reason, financial advisors often categorize home equity separately in investable net worth reports, reserving it for long-term planning rather than short-term liquidity needs. The distinction matters: A hedge fund manager might exclude primary residence equity from their "tradeable" net worth, while a real estate investor would treat it as a core component of their wealth portfolio.Historical Background and Evolution
The modern concept of net worth—rooted in balance sheet accounting—emerged in the 19th century as a tool for businesses to assess solvency. By the mid-20th century, personal net worth calculations adopted similar frameworks, with homeownership becoming a cornerstone of wealth accumulation in post-WWII America. The Homeowners’ Loan Act of 1933 and later FHA programs incentivized mortgage lending, embedding home equity as a default asset in financial planning. Yet the treatment of home equity in net worth evolved alongside economic shifts. During the 2008 financial crisis, the collapse of housing markets exposed a critical flaw: overvalued equity on paper didn’t translate to liquidity when foreclosures surged. The aftermath of the crisis led to a bifurcation in how equity is perceived. Institutions like the Federal Reserve now distinguish between housing wealth (theoretical equity) and financial wealth (cash, stocks, bonds), reflecting the illiquid nature of real estate. Meanwhile, the rise of wealth management tech (e.g., Mint, YNAB) automated net worth tracking, often including home equity by default—even when users couldn’t access it without selling. This disconnect highlights why the question "does net worth include equity in home" isn’t just technical but behavioral: How people think about their wealth shapes how they manage it.Core Mechanisms: How It Works
At its core, home equity’s role in net worth depends on three variables: 1. Property Valuation: Accurate market appraisals are critical. Zillow’s 2023 data suggests 30% of homeowners overestimate their property’s value by 10% or more, inflating perceived equity. 2. Debt Structure: A $500K mortgage on a $600K home yields $100K equity—but if the loan is adjustable-rate, refinancing risks could erode that value. 3. Intentional Use: Equity can be leveraged (via HELOCs or reverse mortgages), preserved (for inheritance), or realized (via sale). Each path alters its impact on net worth. For example, a physician with a $1.2M home and a $300K mortgage might report $900K in equity—but if they’re planning to downsize in retirement, that equity’s realizable value could drop to $750K after taxes and fees. The mechanism isn’t static; it’s a function of market conditions, personal goals, and financial strategy. Even the IRS treats home equity differently: while it’s an asset for net worth purposes, capital gains taxes apply only when the property is sold, adding another layer of complexity.Key Benefits and Crucial Impact
The inclusion—or exclusion—of home equity in net worth calculations carries tangible consequences. For homeowners, it’s often the largest single asset, yet its illiquidity can create a false sense of security. A 2021 survey by the Pew Research Center found that 60% of homeowners consider their property their most valuable asset—but only 22% could access that equity without selling or refinancing. This disconnect explains why financial planners often advise clients to diversify liquid assets (cash, investments) separately from illiquid ones (real estate). The risk? Over-reliance on home equity can leave individuals vulnerable to market downturns or personal crises. > "Home equity is like a locked vault in your financial statement—it’s there, but the key isn’t always in your pocket." > — David Bach, Financial Author and Wealth Strategist The psychological impact is equally significant. Studies show that homeowners with high equity report 35% higher life satisfaction than renters, even when adjusted for income. Yet this satisfaction can turn to stress if equity is tied to debt (e.g., a HELOC used for non-essential expenses). The question "does net worth include equity in home" thus isn’t just mathematical—it’s emotional and strategic.Major Advantages
- Wealth Accumulation Leverage: Home equity grows tax-deferred (no annual capital gains taxes), unlike investment portfolios.
- Collateral for Opportunities: Equity can fund education, business ventures, or emergencies via HELOCs or refinancing.
- Inflation Hedge: Real estate historically appreciates with inflation, preserving purchasing power over time.
- Estate Planning Tool: Passing home equity to heirs avoids probate fees (if structured via trusts or joint ownership).
Comparative Analysis
| Factor | Inclusion in Net Worth |
|---|---|
| Liquidity | Illiquid (requires sale/refinance); excluded from "spendable" net worth in some models. |
| Tax Treatment | No tax on unrealized equity; capital gains tax applies only upon sale. |
| Risk Profile | Lower volatility than stocks but exposed to local market crashes (e.g., 2008 subprime collapse). |
| Financial Planning Use | Included in gross net worth; often segregated in retirement/investment planning. |
Future Trends and Innovations
The treatment of home equity in net worth is evolving with proptech innovations. Blockchain-based property titles (e.g., Propy’s platform) could streamline equity verification, reducing the 20% valuation errors seen today. Meanwhile, fractional real estate investing (via platforms like Arrived Homes) allows owners to monetize equity without selling, blurring the line between illiquid and liquid assets. Regulatory shifts may also redefine equity’s role: the SEC’s 2024 proposed rules on home equity as collateral for retirement accounts could force advisors to reclassify it as a hybrid asset. Another trend is the rise of "equity-sharing" models, where homeowners lease their property to investors in exchange for cash upfront—effectively converting equity into liquidity without a traditional sale. As these models gain traction, the question "does net worth include equity in home" may become obsolete, replaced by dynamic equity valuation that reflects real-time liquidity potential. The challenge? Ensuring transparency in a market where 53% of homeowners don’t know their exact equity, per a 2023 Freddie Mac report.
Conclusion
The answer to "does net worth include equity in home" depends on the lens: accounting, liquidity, or intent. For most homeowners, the equity is a default asset in net worth calculations, but its true value lies in how it’s deployed. The illiquidity paradox—where equity exists on paper but isn’t spendable—demands a nuanced approach. Financial advisors increasingly recommend dual-tracking: one net worth statement for theoretical wealth (including home equity) and another for actionable liquidity (excluding illiquid assets). This distinction is critical for retirees, entrepreneurs, and anyone facing unexpected expenses. Ultimately, home equity’s role in net worth isn’t static. It’s a living variable shaped by market cycles, personal goals, and financial tools. The key takeaway? Don’t confuse equity on a balance sheet with equity in your pocket. A $500K home with $100K equity might look impressive—but if you can’t access that $100K without selling, it’s not working for you. The future of net worth tracking may lie in real-time liquidity scoring, where equity is valued not just by its size, but by its convertibility.Comprehensive FAQs
Q: Does net worth include equity in home for loan applications?
A: Yes, but lenders assess realizable equity—the amount you’d receive after selling or refinancing, minus costs. For example, if your home is worth $800K with a $300K mortgage, the lender may only count $450K ($800K – $300K – 10% transaction costs) as usable equity for borrowing.
Q: How does home equity affect retirement planning?
A: Equity can be a strategic asset in retirement via reverse mortgages or downsizing, but it’s often excluded from "investable" net worth due to illiquidity. Financial planners typically recommend keeping 2–3 years of expenses in liquid assets separate from home equity.
Q: Can negative equity (owing more than the home’s worth) appear in net worth?
A: Yes. If your mortgage exceeds your home’s value (e.g., $350K loan on a $300K home), your net worth calculation would reflect -$50K for that property. This is common in distressed markets and can limit refinancing options.
Q: Does selling a home with equity count as income for taxes?
A: Only the capital gain (sale price minus purchase price minus improvements) is taxable, up to $250K (single filer) or $500K (married) in profit. Primary residence equity is exempt from annual taxes until the sale occurs.
Q: How do financial advisors treat home equity in net worth reports?
A: Most advisors include gross equity (market value minus debt) in total net worth but exclude it from liquid net worth (cash + easily convertible assets). This distinction helps clients understand both theoretical wealth and spendable resources.
Q: What’s the difference between home equity and home value in net worth?
A: Home value is the current market price; equity is value minus debt. For example, a $1M home with a $400K mortgage has $600K equity. Net worth calculations use equity, not gross value, because debt offsets the asset’s contribution to wealth.
Q: Can home equity be used to offset other debts?
A: Yes, via cash-out refinancing or HELOCs, but this replaces one debt (mortgage) with another (new loan) and may trigger taxable income if the new loan exceeds the original mortgage balance. Always compare interest rates and fees.
