The Complete Overview of Does Certificate of Deposit Count as Net Worth
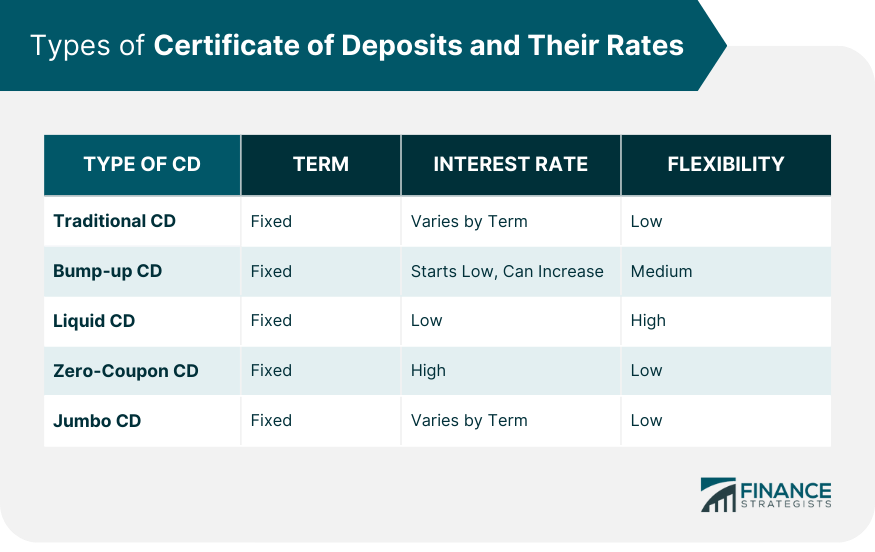
Certificates of deposit are time-bound, interest-bearing deposits held at banks or credit unions, where funds are locked in for a predetermined term in exchange for a fixed interest rate. At their core, they represent a contractual agreement between a depositor and a financial institution, with penalties for early withdrawal. This structure makes them distinct from other liquid assets like checking accounts or even short-term Treasury bills, which can be accessed more readily. When calculating net worth—the difference between total assets and liabilities—CDs are included as assets because they hold monetary value. However, their classification isn’t as straightforward as it seems, particularly when considering liquidity, risk tolerance, and strategic financial planning. The ambiguity stems from how net worth is used rather than just calculated. A CD’s value on a balance sheet is clear: it’s the principal plus accrued interest, minus any fees or penalties if cashed early. But its role in wealth management varies. For someone with no debt and minimal other assets, a CD might be the cornerstone of their net worth. For others, it could be a fraction of a diversified portfolio, where its contribution to overall wealth is secondary to stocks, real estate, or retirement accounts. The key insight? CDs count toward net worth mathematically, but their impact on wealth depends on context—whether they’re serving as a safety net, a short-term goal fund, or a stopgap while waiting for better investment opportunities.Historical Background and Evolution
The modern certificate of deposit traces its origins to early 20th-century banking practices, when institutions sought to stabilize deposits during economic uncertainty. The first standardized CDs emerged in the 1960s as a response to rising interest rates, offering depositors higher yields than passbook savings accounts while allowing banks to manage liquidity more effectively. Their design was simple: lock in funds for a set term (often 30 days to several years) in exchange for a guaranteed return, with early withdrawal subject to penalties. This structure made CDs particularly appealing during periods of inflation or market downturns, when fixed-income instruments provided a rare sense of security. Over time, CDs evolved alongside regulatory changes and technological advancements. The Depository Institutions Deregulation and Monetary Control Act of 1980 removed interest rate caps on deposits, allowing banks to offer more competitive CD rates. The rise of digital banking in the late 20th and early 21st centuries further transformed CDs, with online banks introducing no-fee CDs, higher yields, and flexible term options. Today, CDs coexist with alternatives like money market accounts and Treasury securities, yet they retain a niche appeal for risk-averse investors or those prioritizing capital preservation over growth. This historical context is critical because it explains why CDs are treated differently in net worth calculations than, say, equities or cryptocurrency—they were never designed to be speculative assets.Core Mechanisms: How It Works
A CD’s mechanics are deceptively simple: deposit funds for a fixed term, earn interest, and avoid penalties if withdrawn before maturity. The interest rate is negotiated at the time of purchase and remains constant until the CD matures. For example, a 12-month CD with a 4% APY will pay out interest monthly or annually, compounded based on the bank’s terms. The catch? Early withdrawal typically incurs a penalty equal to a portion of the interest earned, sometimes up to several months’ worth. This penalty structure is what differentiates CDs from other savings vehicles—they’re not just about earning interest; they’re about committing capital for a set period. The tax implications further complicate their role in net worth. Interest earned on CDs is taxable as ordinary income, regardless of whether it’s reinvested or withdrawn. This means that while CDs contribute to net worth, their after-tax yield may be lower than advertised. Additionally, CDs don’t benefit from capital gains treatment or tax-deferred growth like IRAs or 401(k)s. For high-net-worth individuals, this can make CDs less attractive compared to tax-advantaged alternatives, even if they’re included in net worth calculations. The interplay of these factors—fixed terms, penalties, and tax treatment—explains why CDs are often seen as a tactical rather than strategic asset in wealth management.Key Benefits and Crucial Impact
Certificates of deposit occupy a unique space in personal finance: they’re neither the highest-yielding investment nor the most liquid savings tool, yet they offer stability in an unpredictable economic landscape. Their primary appeal lies in their predictability—unlike stocks or even high-yield savings accounts, a CD’s return is locked in from day one. This certainty makes them a favorite among conservative investors, retirees living on fixed incomes, or anyone nearing a short-term financial goal (like a down payment). The trade-off? Liquidity. While CDs do count toward net worth, their illiquidity can be a double-edged sword: they protect against market downturns but may limit access to funds during emergencies. The psychological impact of CDs on net worth is often underestimated. For someone with modest assets, a CD can represent a tangible milestone—proof of disciplined saving. For others, it might feel like "dead money" compared to the growth potential of stocks or real estate. This perception gap highlights a fundamental truth: CDs count toward net worth on paper, but their perceived value depends on individual goals. A retiree might view a CD as a critical component of their liquidity strategy, while a young professional might see it as an inefficient use of capital. The tension between objective accounting and subjective financial psychology is what makes the question of whether CDs should count as net worth so contentious."CDs are the financial equivalent of a savings account with a time lock—useful for goals you know you won’t need to touch, but frustrating when life doesn’t cooperate." — Certified Financial Planner, speaking on the role of CDs in net worth strategies
Major Advantages
- Guaranteed returns: Unlike market-linked investments, CDs offer fixed interest rates, shielding holders from volatility.
- FDIC insurance (up to $250,000 per account): CDs at insured banks carry the same deposit insurance as savings accounts, protecting against institutional failure.
- Simple tax reporting: Interest is automatically reported to the IRS, reducing paperwork compared to self-directed investments.
- Strategic liquidity management: CDs can act as a bridge between short-term savings and long-term investments, ensuring funds are available when needed.
Comparative Analysis
| Metric | Certificate of Deposit | High-Yield Savings Account |
|---|---|---|
| Interest Rate | Fixed for term (e.g., 3–5%) | Variable (often 3.5–4.5% APY) |
| Liquidity | Penalties for early withdrawal | Instant access to funds |
| Net Worth Impact | Counts as asset; illiquid portion may reduce perceived flexibility | Counts as asset; fully liquid |
| Tax Treatment | Taxed as ordinary income | Taxed as ordinary income |
| Best For | Short-term goals, capital preservation | Emergency funds, frequent access |
Future Trends and Innovations
The role of CDs in net worth calculations may evolve as financial technology reshapes traditional banking. One trend is the rise of no-penalty CDs, which allow early withdrawal without fees, blurring the line between CDs and savings accounts. Another development is the growth of algorithmic CD ladders, where investors automate the process of rolling over maturing CDs into new ones to optimize yields. These innovations could make CDs more appealing to younger investors who prioritize flexibility, potentially increasing their inclusion in net worth portfolios. Regulatory shifts may also influence how CDs are perceived. For instance, if inflation persists, central banks might adjust reserve requirements, indirectly affecting CD yields. Meanwhile, the push for open banking could introduce new products that combine CD-like stability with greater liquidity. The overarching question remains: Will CDs continue to count as net worth in the same way, or will they become niche tools for specific financial scenarios? The answer likely depends on whether they adapt to meet the demands of a more dynamic economy—or if they’re relegated to the financial sidelines.
Conclusion
Certificates of deposit do count as net worth, but their significance extends beyond simple arithmetic. They represent a contractual promise—one that balances security with restricted access to capital. For many, CDs are the backbone of a conservative financial strategy, offering peace of mind in uncertain times. Yet their inclusion in net worth calculations must be weighed against alternatives that offer higher growth potential or greater liquidity. The truth is that CDs aren’t just about the numbers; they’re about aligning financial tools with personal priorities. The debate over whether CDs should count as net worth ultimately hinges on perspective. To a retiree, they’re a critical part of a stable asset base. To a tech entrepreneur, they might feel like an afterthought. What’s undeniable is that CDs fulfill a unique role in the spectrum of financial instruments—one that persists because it addresses a fundamental human need: the desire for predictability in an unpredictable world. As long as that need exists, CDs will remain a fixture in net worth calculations, even if their prominence waxes and wanes with economic cycles.Comprehensive FAQs
Q: Does certificate of deposit count as net worth?
Yes, CDs are included in net worth calculations as assets, valued at their principal plus accrued interest. However, their illiquidity may affect how they’re perceived in broader financial planning.
Q: How are CDs taxed in relation to net worth?
Interest earned on CDs is taxable as ordinary income, which reduces their after-tax yield. This doesn’t change their inclusion in net worth but impacts their real-world value.
Q: Can I withdraw from a CD without penalty and still have it count toward net worth?
Yes, but only if the bank offers no-penalty CDs. Early withdrawals from standard CDs incur fees, which would reduce the asset’s value in your net worth calculation.
Q: Are CDs better for net worth than high-yield savings accounts?
It depends on goals. CDs offer fixed rates, while HYSAs provide flexibility. For short-term goals, HYSAs may be preferable; for locked-in savings, CDs can be more advantageous.
Q: How do CDs affect my credit score when calculating net worth?
CDs themselves don’t impact credit scores, but they contribute to your overall asset base. A higher net worth (including CDs) may improve loan approval odds, indirectly benefiting creditworthiness.
Q: Should I prioritize CDs over other investments in my net worth strategy?
CDs are best for capital preservation, not growth. A diversified net worth strategy typically balances CDs with higher-risk, higher-reward assets like stocks or real estate.
Q: What happens to my CD’s value in net worth if interest rates rise after I purchase it?
Your CD’s rate is locked in, so rising rates won’t affect its yield. However, new CDs may offer higher returns, potentially making existing ones less competitive in your net worth portfolio.
Q: Can CDs be part of a tax-efficient net worth strategy?
Not directly, since CD interest is taxed as ordinary income. However, laddering CDs across terms can optimize liquidity while minimizing taxable events.
Q: Do CDs count toward net worth if held in a trust or estate plan?
Yes, CDs are assets and would be included in estate valuations. Their fixed terms may complicate inheritance timing, but they remain part of the net worth calculation.
Q: How do early withdrawal penalties impact net worth?
Penalties reduce the CD’s effective yield and lower its value in net worth calculations. For example, a 3-month penalty on a 5% CD could erase much of its interest advantage.
