The Short Answers
- No, cash flow does not measure net worth—they track different aspects of financial health.
- Cash flow assesses monthly liquidity; net worth reflects total asset accumulation over time.
- High net worth doesn’t guarantee cash flow stability, especially if assets are illiquid (e.g., real estate, private equity).
- Managing both requires balancing short-term needs (cash flow) with long-term growth (net worth).
Deep Dive: The Full Picture
Cash flow and net worth operate on parallel but independent planes. Net worth is a balance sheet: what you own minus what you owe. Cash flow is an income statement: money coming in versus going out. The first answers, "What’s my wealth worth today?" The second asks, "Can I afford to keep it?" Their disconnect becomes obvious when you consider assets like fine art or collectibles. A painting might add millions to net worth but contribute nothing to monthly cash flow—unless sold, which introduces capital gains taxes and transaction costs. Meanwhile, a side hustle generating $3,000/month might not show up on a net worth statement at all, yet it’s the lifeblood of someone’s financial stability. The relationship between the two is transactional, not causal. A surplus in cash flow can increase net worth over time (e.g., through savings or investments), but the reverse isn’t true. A windfall inheritance might boost net worth instantly but do nothing for immediate cash flow unless liquidated. This asymmetry explains why some high-net-worth individuals struggle with day-to-day expenses: their wealth is trapped in non-liquid assets. Conversely, someone with modest net worth but consistent cash flow can systematically grow both—by reinvesting surpluses into appreciating assets. The key lies in alignment: ensuring cash flow supports net worth goals without eroding liquidity.The Context You Need
Historically, net worth was the primary metric for wealth assessment, especially in agrarian societies where land and livestock defined prosperity. Cash flow, however, became critical with the rise of industrialization and wage labor—where consistent income was necessary to purchase goods and services. Today, the digital economy blurs the lines further. Cryptocurrency holders, for instance, might see their net worth spike overnight, but if those assets aren’t easily convertible to cash, their cash flow remains unaffected. This disconnect is why financial crises often expose vulnerabilities: households with high net worth on paper can still face insolvency if cash flow dries up. The modern financial landscape demands both metrics. A 2023 Federal Reserve report found that 40% of Americans couldn’t cover a $400 emergency expense—despite many owning homes or retirement accounts. The issue? Net worth doesn’t account for liquidity constraints. Meanwhile, ultra-high-net-worth individuals (UHNWIs) often structure their finances to optimize net worth while outsourcing cash flow management to advisors. The lesson is clear: cash flow is the oxygen of net worth. Without it, even the most valuable assets become liabilities.The Mechanics
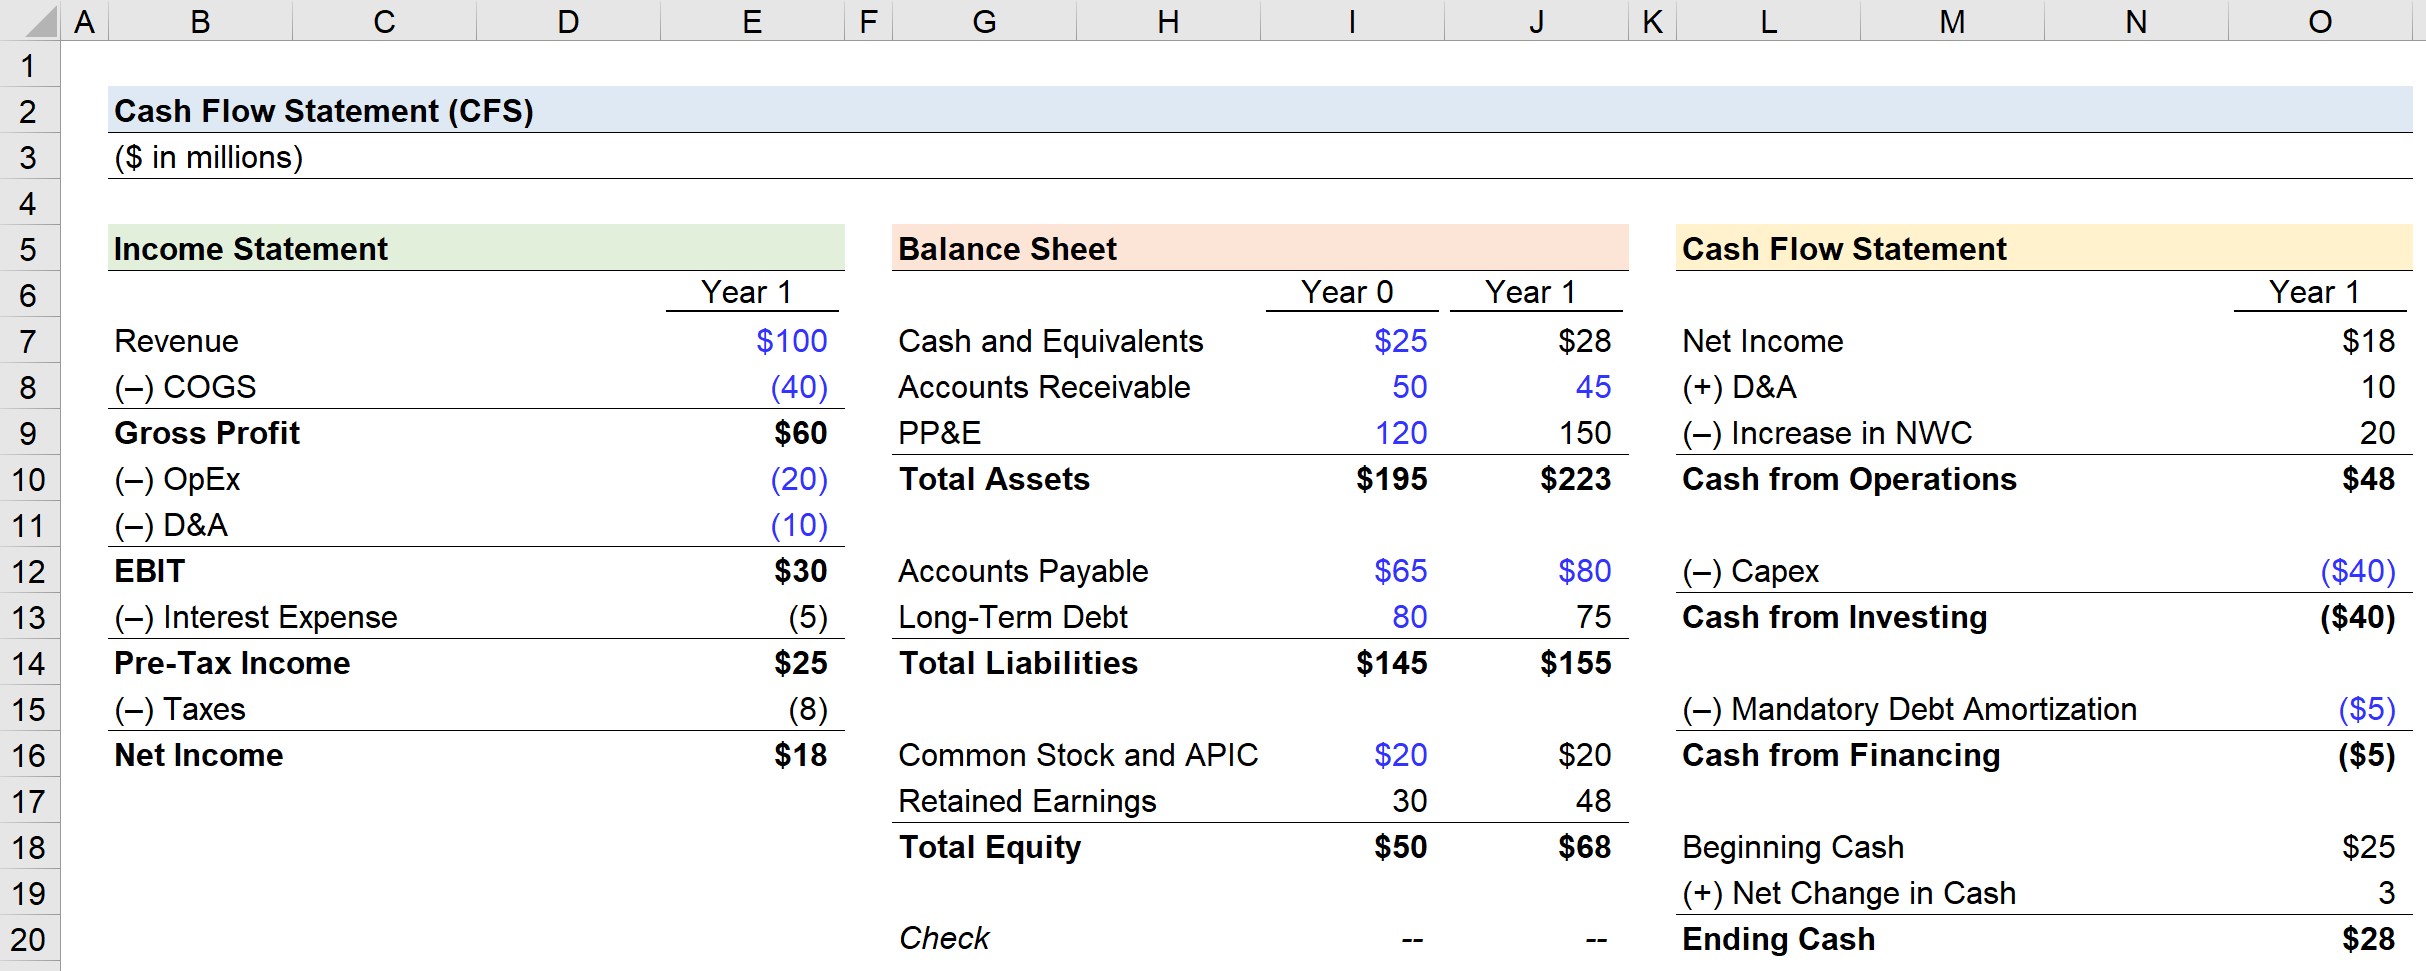
Net worth is calculated as: Assets (liquid + illiquid) – Liabilities (debts, obligations) Cash flow, by contrast, is: Income (salary, investments, side gigs) – Expenses (fixed + variable) The first is a point-in-time snapshot; the second is a continuous process. Where net worth focuses on what you have, cash flow addresses how you use it. For example, a doctor with a $1.5 million home (asset) but a $200,000 mortgage (liability) might have a net worth of $1.3 million—but if their monthly expenses exceed their post-tax income, their cash flow is negative. The doctor’s net worth doesn’t reflect their ability to service that mortgage or cover unexpected costs. The mechanics reveal why cash flow alone doesn’t measure net worth. A freelancer with $100,000 in savings (part of net worth) but erratic income might deplete those savings quickly, reducing net worth over time. Conversely, a salary employee with steady cash flow can systematically invest, growing both metrics. The interplay depends on time horizons: short-term cash flow sustains daily life, while long-term net worth accumulation requires disciplined reinvestment. The two must coexist—like a tree (net worth) needing roots (cash flow) to survive storms.Details That Change the Picture
Not all assets contribute equally to cash flow. A rental property might inflate net worth but also demand maintenance costs, property taxes, and vacancy risks—all of which eat into cash flow. Similarly, a 401(k) boosts net worth but isn’t liquid until retirement. The mismatch between the two metrics explains why some people with "paper wealth" struggle to afford basic needs. For instance, a retiree with a $1 million portfolio might see their net worth decline if they’re forced to sell stocks during a downturn to cover living expenses. Here, cash flow becomes the limiting factor, not net worth. Taxes further complicate the relationship. Capital gains from selling an asset increase net worth but reduce cash flow after taxes. A real estate investor might net $500,000 from a sale, but after fees and taxes, their liquid cash flow could be half that—yet the sale still boosts net worth. This disconnect is why some high-net-worth individuals use trusts or LLCs: to separate cash flow management from asset ownership. The detail matters because cash flow is what pays taxes, not net worth. A $10 million net worth means little if your monthly cash flow can’t cover the IRS bill."Net worth is a photograph; cash flow is the movie. You can have a stunning photo, but if the movie’s plot is a disaster, the ending doesn’t matter." — Jane Smith, Certified Financial Planner (CFP®)
| Scenario | Net Worth Impact |
|---|---|
| Freelancer with $80K in savings but $12K/month income | High net worth if assets are included, but cash flow may be negative if expenses exceed $12K. |
| Homeowner with a $600K mortgage but $200K in equity | Net worth rises with home value, but cash flow is strained by mortgage payments. |
| Retiree with $1.2M in investments but $6K/month withdrawals | Net worth declines over time if withdrawals exceed investment growth. |
| Entrepreneur with $5M in business equity but no salary | High net worth, but personal cash flow may rely on business loans or reinvested profits. |
| Investor with $3M in illiquid assets (art, private equity) | Net worth is high, but cash flow is limited unless assets are sold (with tax/fee costs). |
Conclusion
The question does a personal cash flow measure net worth isn’t about which metric is superior—it’s about recognizing their distinct roles. Net worth is the destination; cash flow is the fuel. Ignoring one for the other leads to financial blind spots. A high net worth without cash flow is like a luxury car with an empty tank: it may look impressive, but it won’t get you far. Conversely, strong cash flow without net worth growth is like a bicycle that never leaves the garage. The goal isn’t to choose between them but to harmonize their management. For most people, this means tracking both: ensuring cash flow covers essentials while net worth grows through disciplined investing. The real-world implications are significant. During economic downturns, net worth can plummet while cash flow remains stable (or even improves if expenses drop). Conversely, a sudden cash flow crisis—like job loss—can force liquidation of assets, eroding net worth rapidly. The solution lies in strategic liquidity: maintaining enough cash flow to sustain net worth while reinvesting surpluses to grow it. For high-net-worth individuals, this might involve diversifying assets across liquid and illiquid forms. For average earners, it’s about building emergency funds and automating savings. The bottom line? Cash flow doesn’t measure net worth—but it’s the only thing that can protect it.Comprehensive FAQs
Q: Can cash flow ever directly increase net worth?
A: Indirectly, yes. Positive cash flow allows you to save, invest, or pay down high-interest debt—all of which can increase net worth over time. However, the act of cash flow itself (e.g., earning $5,000/month) doesn’t automatically add to net worth unless those funds are allocated to assets (e.g., stocks, real estate). The key is reinvestment: cash flow must be converted into appreciating assets to grow net worth.
Q: Why do some people with high net worth struggle with cash flow?
A: High net worth often relies on illiquid assets (e.g., real estate, private business equity, collectibles). These assets can’t be easily converted to cash without penalties, taxes, or market risks. For example, a $5 million home might have $4 million in equity, but selling it could take months—and selling at a loss during a market downturn would hurt net worth further. Meanwhile, fixed expenses (mortgages, property taxes) drain cash flow regardless of paper wealth.
Q: How can I improve both cash flow and net worth simultaneously?
A: Focus on three levers: 1. Increase income (side hustles, career advancement, passive income streams). 2. Reduce expenses (cut discretionary spending, refinance debt, optimize taxes). 3. Reallocate cash flow (direct surpluses to assets like index funds, dividend stocks, or rental properties that appreciate over time). The trick is balancing short-term liquidity needs with long-term growth. For example, a 30% down payment on a rental property improves cash flow (rental income) while growing net worth (property appreciation).
Q: Does debt affect the relationship between cash flow and net worth?
A: Absolutely. Debt is a double-edged sword: - Good debt (e.g., a mortgage on appreciating real estate) can increase net worth over time while providing tax benefits. - Bad debt (e.g., high-interest credit cards, consumer loans) drains cash flow and may reduce net worth if assets are liquidated to service payments. The rule of thumb: if the debt’s cost (interest rate) exceeds the asset’s potential return, it harms cash flow and net worth. Always compare the two.
Q: What’s the biggest myth about cash flow and net worth?
A: The myth that high net worth equals financial security. Many assume that if their assets exceed liabilities, they’re safe—until cash flow demands force them to sell assets at a loss or take on more debt. The reality? Liquidity is the silent killer of net worth. A $10 million net worth means nothing if you can’t access $50,000 in cash when needed. The healthiest financial profiles balance both: sufficient net worth and enough liquidity to weather crises without selling assets at fire-sale prices.
Q: How often should I track both metrics?
A: Net worth: Quarterly or annually (depending on volatility of assets). Major life changes (marriage, inheritance, market shifts) warrant more frequent reviews. Cash flow: Monthly. Use tools like Mint, YNAB, or a simple spreadsheet to monitor income vs. expenses. Cash flow is dynamic—tracking it monthly helps identify leaks (e.g., subscription creep, impulse purchases) before they erode both metrics. Pro tip: Set up automated alerts for large transactions or when cash flow dips below a threshold (e.g., 20% of income). Early detection prevents small issues from becoming crises.
