The Short Answers
- Disney’s Forbes net worth (2023) is estimated near $110 billion, down from earlier peaks due to debt, streaming losses, and IP depreciation.
- Forbes’ valuation differs from market cap because it accounts for liabilities, cash reserves, and intangible assets—not just stock price.
- The company’s $28 billion debt load and $1.5B/year Disney+ losses drag down its net worth, even as theme parks and merchandising remain cash cows.
- Disney’s film/TV library (including Marvel, Star Wars, and Pixar) is its most valuable asset—but its depreciation on balance sheets distorts true worth.

Deep Dive: The Full Picture
Disney’s financial health isn’t monolithic. Its Forbes net worth is a composite of three pillars: content creation (studios, IP), experiences (parks, cruises), and distribution (streaming, linear TV). The first two generate steady cash flow; the third is a black hole. In 2023, Disney’s theme parks alone contributed $30 billion in revenue—a figure that would dwarf most Fortune 500 companies. Yet the streaming division, despite 150 million subscribers, operates at a loss, forcing Disney to either raise prices (risking churn) or sell assets (like its Hulu stake). The Forbes valuation penalizes this mismatch: while the market may forgive streaming losses as "growth investments," Forbes’ balance-sheet approach treats them as liabilities.
The company’s debt-to-equity ratio (around 1.5:1) is a red flag in corporate finance circles. Disney’s leverage isn’t unusual for a media giant, but the timing is problematic. With interest rates rising, refinancing $28 billion in debt becomes costlier. Meanwhile, its film library—once the crown jewel—is depreciated aggressively. A 2022 SEC filing revealed Disney wrote down the value of its classic animated films by billions, acknowledging that even The Lion King or Frozen have finite revenue lifespans. This depreciation isn’t a sign of failure; it’s a brutal acknowledgment that in the streaming era, content is a depreciating asset, not a perpetuity.
#### The Context You Need
Disney’s financial trajectory mirrors the broader media industry’s shift from asset ownership to service subscriptions. A decade ago, buying a studio like Lucasfilm or Marvel was a net worth booster—today, it’s a capital-intensive gamble. The Forbes net worth reflects this pivot: while Disney’s parks and merchandise (which generate $12 billion/year in profit) remain recession-resistant, its streaming and studio divisions are betting on long-term plays that haven’t yet paid off. The company’s 2023 earnings report showed $23 billion in revenue, but $1.6 billion in net income—a margin that would make tech giants blush, but feels anemic for a company with Disney’s scale. The Forbes valuation also factors in Disney’s real estate empire. Its $1.6 billion annual spend on content (excluding acquisitions) is dwarfed by its $20 billion+ in owned properties—from Burbank studios to the Florida resort. These physical assets don’t depreciate like IP, but they’re illiquid. Selling a theme park isn’t like selling a stock; it’s a strategic decision with cultural repercussions. This duality—tangible real estate vs. intangible IP—makes Disney’s net worth a moving target. While the market may reward growth potential, Forbes’ methodology demands hard assets. ####The Mechanics
Forbes’ net worth calculation for Disney differs from traditional GAAP accounting in three key ways: 1. Debt Treatment: Forbes includes off-balance-sheet obligations (like pension liabilities) and operating leases, which Disney’s public filings may understate. 2. Asset Depreciation: While Disney depreciates film libraries over 5–10 years, Forbes may apply stricter timelines, reflecting the faster obsolescence of streaming-era content. 3. Cash Reserves: Disney holds $10 billion+ in liquid assets, but Forbes adjusts for working capital needs, reducing the net worth figure. The result? A valuation that’s conservative but realistic. Disney’s stock price can spike on a strong quarter (as it did post-Avatar: The Way of Water), but Forbes’ net worth is a long-term snapshot—one that accounts for the $1.5 billion annual Disney+ loss and the $3 billion spent on The Mandalorian and Star Wars. This isn’t about short-term volatility; it’s about whether Disney can monetize its IP portfolio beyond the next blockbuster.Details That Change the Picture
Disney’s Forbes net worth is a Rorschach test for financial analysts. Optimists point to its $120 billion revenue run rate and argue that streaming losses will shrink as ad-supported tiers scale. Pessimists highlight the $28 billion debt and the fact that Disney’s ROIC (return on invested capital) has fallen below its cost of capital—a death knell in corporate finance. The truth lies in the asset mix: 40% of Disney’s valuation comes from parks and merchandise, while 30% is tied to film/TV libraries—assets that are both its greatest strength and its biggest risk.
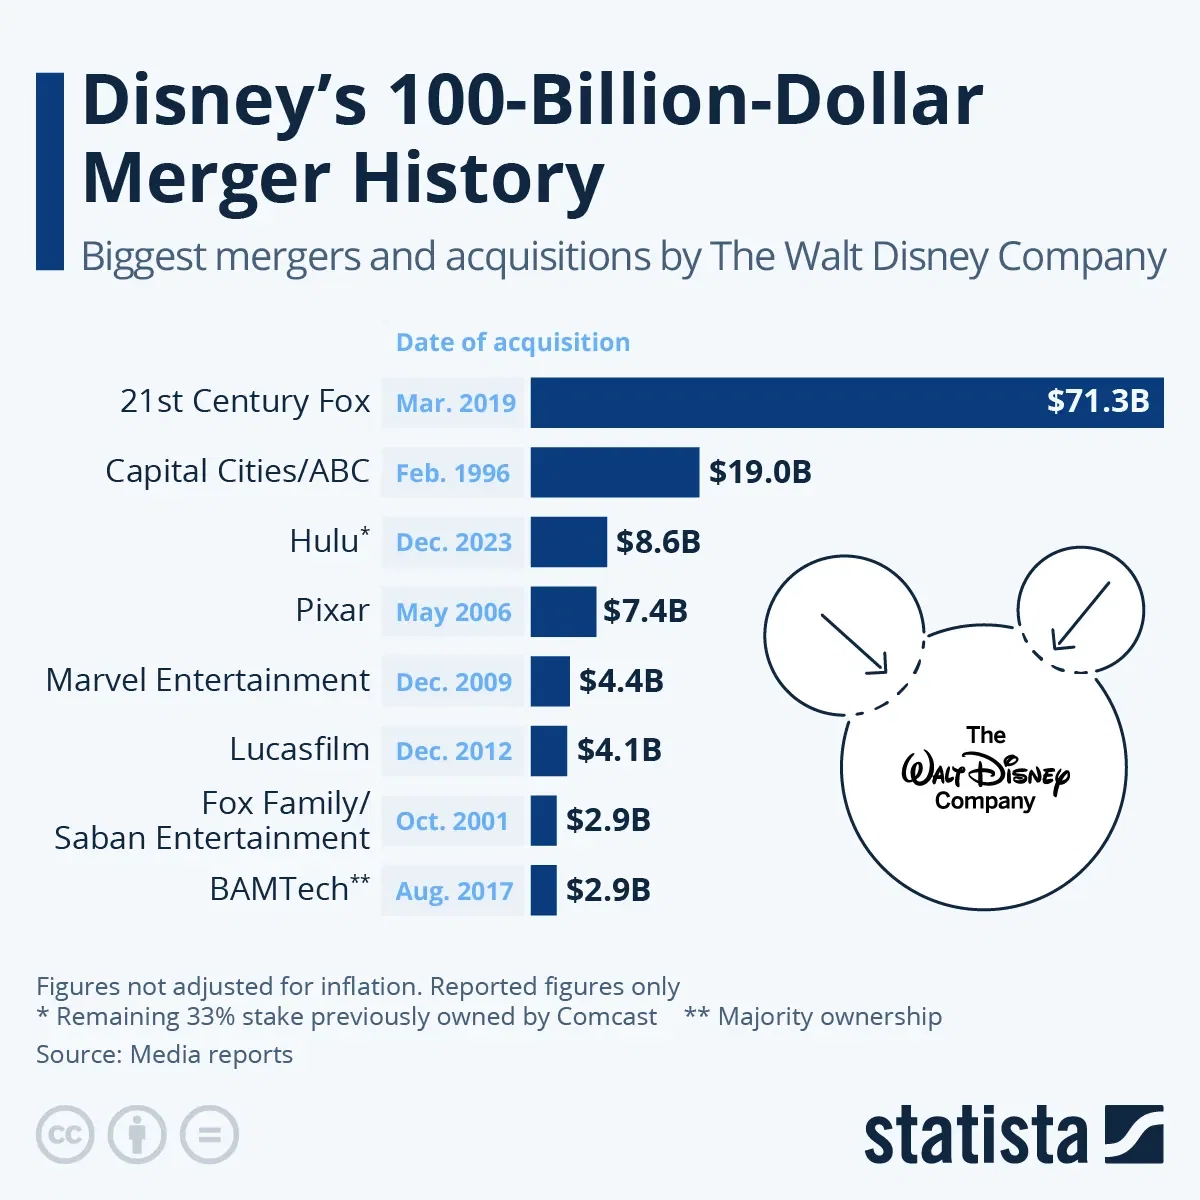
The company’s 2023 capital allocation—prioritizing debt reduction over acquisitions—signals a shift. After spending $71 billion on the Fox deal (2019), Disney is now selling underperforming assets (like its 50% stake in Hulu) to trim debt. This pragmatism aligns with Forbes’ valuation philosophy: liabilities matter more than hype. Even as Disney pitches Encanto 2 or Wish as franchises, the Forbes net worth asks: How much of this is sustainable?
"Disney’s problem isn’t that it’s losing money—it’s that its losses are structural, not cyclical. The market forgives growth; Forbes doesn’t."
—Analyst at Media Finance Group, 2023
| Metric | 2023 Figure |
|---|---|
| Forbes Net Worth (Est.) | $110 billion |
| Market Capitalization | $105 billion |
| Long-Term Debt | $28 billion |

Conclusion
Disney’s Forbes net worth isn’t just a number—it’s a financial stress test. The company’s ability to balance legacy cash cows (parks, merchandising) with high-risk bets (streaming, IP development) will determine whether its valuation recovers or continues to erode. The $110 billion estimate isn’t a death knell, but it’s a warning: Disney’s financial model is no longer self-sustaining. Without a turnaround in streaming profitability or a new Avengers-level franchise, the gap between market cap and net worth will widen.
The bigger story, however, is what this means for the industry. Disney’s struggles mirror those of Warner Bros., Paramount, and Netflix—all grappling with the cost of content in a subscriber-driven world. Forbes’ valuation isn’t just about Disney; it’s a report card for the entertainment economy. If the Mouse can’t crack the code, the entire media landscape may need to rethink how it values IP, debt, and the future of storytelling.
Comprehensive FAQs
#### Q: Why does Disney’s Forbes net worth differ from its market cap?
Forbes’ valuation accounts for liabilities, cash reserves, and intangible asset depreciation, while market cap reflects shareholder sentiment and growth expectations. Disney’s $28 billion debt and streaming losses drag down its net worth, even if investors bet on future recovery.
####Q: Is Disney’s net worth declining because of streaming losses?
Partially. While Disney+ has 150 million subscribers, it burns $1.5 billion/year. Forbes penalizes this as a liability, whereas the market may see it as a growth investment. The decline also reflects aggressive IP depreciation and rising debt costs post-2022 rate hikes.
####Q: How does Disney’s debt affect its net worth?
High debt ($28 billion) increases financial risk, reducing net worth. Forbes adjusts for interest expenses and refinancing costs, which Disney’s public filings may understate. This is why its debt-to-equity ratio (1.5:1) is a key drag on valuation.
####Q: What’s Disney’s most valuable asset in Forbes’ eyes?
Theme parks and merchandise—generating $12 billion/year in profit—are the most stable. Film/TV libraries (Marvel, Star Wars) are valuable but depreciate faster in Forbes’ methodology. Physical assets like Burbank studios also hold steady value.
####Q: Could Disney’s net worth rebound soon?
Possible, but unlikely without streaming profitability or a new franchise. Disney’s 2024 strategy focuses on debt reduction and ad-supported tiers, but analysts warn these moves may compress margins before boosting net worth.
####Q: How does Disney’s net worth compare to peers like Warner Bros. or Netflix?
Disney’s $110B net worth dwarfs Warner Bros. ($50B) but lags Netflix ($130B), which has no debt and higher streaming margins. Disney’s diversified revenue streams (parks, TV) make it less volatile than pure-play streamers.
####Q: Does Disney’s net worth include its film libraries?
Yes, but depreciated. Disney’s $100B+ catalog is valued at $30–40B in Forbes’ model, reflecting faster obsolescence in the streaming era. This is a key difference from traditional accounting, which may overstate IP value.
