
5 Things Worth Knowing About Net Worth You Include Your House
The debate over whether to include your home in net worth calculations hinges on five key factors, each with its own financial and psychological implications. These aren’t just technicalities; they determine how you’re perceived by institutions, how you perceive yourself, and how you plan for the future.1. Net worth calculations for personal tracking often exclude the home—here’s why
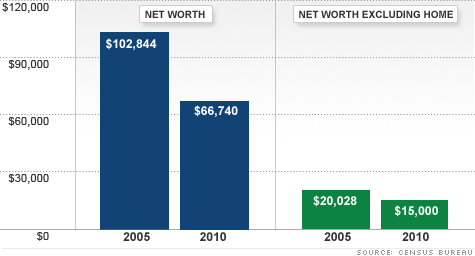
Most financial advisors recommend excluding your primary residence when calculating net worth for personal use. The reasoning is straightforward: a home’s value is volatile, tied to local market conditions that can swing wildly without reflecting your actual financial health. For example, a homeowner in a booming city might see their property’s value double over a decade, only for it to stagnate or drop during a recession. This volatility makes it a poor benchmark for liquidity or emergency preparedness. Moreover, personal net worth is typically meant to measure what you could realistically access in a crisis. A home isn’t liquid—selling it takes time, incurs transaction costs, and may not yield the full appraised value. Excluding it forces a harder look at cash reserves, investments, and other assets that can be converted to cash quickly. This approach aligns with the core principle of financial planning: focus on what you can control, not what the market says you’re worth.2. Lenders and financial institutions almost always require home value in net worth statements
When you apply for a mortgage, refinance, or seek a personal loan, lenders demand a full picture of your assets—including your home. Here, the question isn’t whether to include it, but how. Banks use your home’s appraised value (minus any remaining mortgage balance) to assess your loan-to-value ratio, which directly impacts interest rates and approval odds. A higher net worth—even if inflated by an overvalued property—can improve your borrowing power, but it also increases risk if the market shifts. This discrepancy highlights a critical divide: personal net worth for self-assessment often excludes the home, while institutional net worth calculations almost always include it. The lesson? Your net worth on paper can vary wildly depending on the audience. A homeowner with a $1M house and $500K mortgage might report $500K in net worth to themselves but $1.5M to a lender. This duality isn’t just semantics—it affects everything from credit limits to insurance premiums.3. Tax implications: The IRS treats home equity differently than other assets
For tax purposes, the inclusion of your home in net worth calculations is less about the number itself and more about how gains are realized. The IRS doesn’t tax unrealized home equity—meaning you won’t pay capital gains until you sell. However, if you do sell, the rules change dramatically. Under current U.S. tax law, homeowners can exclude up to $250K (single filers) or $500K (married couples) in profit from capital gains taxes, provided they’ve lived in the home for two of the past five years. This exemption turns your home into a unique asset: one that can appreciate indefinitely without triggering taxes—until you act on it. This tax-advantaged status is why many financial planners advise clients to treat their homes as long-term wealth stores rather than liquid assets. The catch? If you downsize or face financial hardship, the tax bill on realized gains could be substantial. For example, a couple who bought their home for $300K in 1995 and sold it for $1.2M in 2023 would owe taxes on $700K—unless they’ve used the exemption. The takeaway: including your home in net worth calculations for tax planning requires a forward-looking approach, not just a snapshot of current value.4. Divorce and estate planning force a reckoning with home equity
In legal contexts like divorce settlements or estate distribution, your home’s value is almost always included in net worth calculations—and often treated as a primary asset to divide or inherit. Courts typically appraise the home at its current market value, then subtract any mortgage or liens to determine its equity. This equity is then split according to state laws or prenuptial agreements, which can lead to unexpected outcomes. For instance, a spouse who contributed little to the home’s purchase or maintenance might still receive a substantial portion of its equity in a divorce, depending on jurisdiction. Estate planning adds another layer. When you pass away, your home’s value is included in your gross estate for inheritance tax purposes, even if it’s not sold. Heirs may inherit the property subject to a stepped-up basis (eliminating capital gains taxes for them), but they’ll also inherit the mortgage and maintenance burdens. This is why many estate planners recommend structuring home ownership to minimize tax liabilities—for example, by transferring the property to a trust or joint tenancy before death.5. The psychological trap: Overvaluing your home distorts financial reality
Here’s the paradox: the more your home’s value inflates your net worth, the more you might rely on it as a financial crutch. Studies show homeowners with significant equity are more likely to take on riskier investments, assuming their property will always bail them out. This "house as safety net" mentality can lead to poor decisions—like skipping emergency funds or overleveraging against home equity. The flip side is equally dangerous: underestimating your home’s value can lead to missed opportunities. For example, a homeowner might decline a lucrative investment because they don’t recognize their true net worth, or they might hesitate to downsize in retirement, fearing a loss of status tied to their property. The emotional weight of a home often outweighs its financial reality. That’s why advisors recommend regular "net worth audits" that separate your home’s market value from your liquid assets, ensuring you’re making decisions based on facts, not sentiment.
How These Facts Connect
The tension between including and excluding your home in net worth calculations reveals a deeper truth: wealth isn’t a monolith. It’s a mosaic of liquidity, risk tolerance, and institutional expectations. Your personal net worth—stripped of home equity—might show you as more vulnerable than you feel, while a lender’s calculation could paint you as a high-net-worth client. This disconnect isn’t a bug; it’s a feature of how different systems value you. The patterns emerge when you compare these factors side by side. Personal tracking focuses on control and liquidity; institutions prioritize collateral and risk assessment; taxes reward long-term holding; and legal systems enforce equity distribution. The home sits at the intersection of all these worlds, making it the ultimate litmus test for how you define wealth. Do you see it as an investment, a liability, a legacy, or all three?| Context | Inclusion Rule | Key Consideration | Risk Factor |
|---|---|---|---|
| Personal net worth | Often excluded | Liquidity and volatility | Underestimating true financial flexibility |
| Lender/financial apps | Always included | Collateral and loan-to-value | Overleveraging if market dips |
| Tax planning | Included for gains, but tax-deferred | Capital gains exemption thresholds | Unexpected tax bills on sales |
| Divorce/estate | Always included | Equity division and inheritance tax | Disputes over appraised value |
| Psychological | Subjective (often overvalued) | Emotional attachment vs. financial reality | Poor decision-making based on perceived wealth |
Conclusion
The debate over whether to include your house in net worth calculations isn’t about right or wrong—it’s about context. For personal financial health, excluding it forces discipline; for lenders and courts, including it is non-negotiable. The challenge lies in navigating these competing demands without letting your home’s value blind you to other risks. The home is more than an asset; it’s a mirror reflecting your financial priorities, biases, and blind spots. The solution isn’t to pick one approach and stick with it rigidly. Instead, it’s to recognize that your net worth—whether it includes your house or not—should serve a purpose. Is it for tracking progress? For securing a loan? For planning an inheritance? Each goal demands a different lens. The home’s value will always be part of the equation, but how you weigh it determines whether it’s an anchor or a compass.Comprehensive FAQs
Q: Does including my home in net worth help or hurt my credit score?
Including your home’s value in net worth calculations doesn’t directly affect your credit score, which is based on payment history, debt levels, and credit utilization. However, if you use home equity to take on new debt (e.g., a home equity loan or line of credit), that debt will appear on your credit report and could lower your score if it increases your debt-to-income ratio. Lenders may also view higher net worth as a sign of lower risk, potentially qualifying you for better loan terms—but this is indirect.
Q: Can I exclude my home from net worth if I’m self-employed or freelancing?
Yes, but with caveats. Self-employed individuals often exclude their primary residence from personal net worth tracking to focus on liquid assets like business equity, retirement accounts, and cash reserves. However, if you’re applying for a business loan or seeking investors, lenders may still require a full asset disclosure, including your home. The key is consistency: if you’re using net worth for personal financial planning, exclude it; if it’s for external purposes, include it as required.
Q: How often should I update my home’s value in net worth calculations?
For personal tracking, update your home’s appraised value annually or whenever major market shifts occur (e.g., local economic changes, interest rate hikes, or neighborhood developments). For tax or legal purposes, you’ll need a professional appraisal only when selling, refinancing, or settling an estate. Tools like Zillow or Redfin can provide rough estimates, but for high-stakes decisions, a formal appraisal is essential. The goal is to balance accuracy with practicality—don’t let the pursuit of precision paralyze your financial planning.
Q: What’s the difference between net worth that includes my house and "liquid net worth"?
Net worth that includes your home reflects your total asset value minus liabilities, giving a broad picture of wealth. Liquid net worth, however, strips out illiquid assets (like your home, retirement accounts, or collectibles) to show only what you could access quickly—cash, investments, and easily sellable assets. The gap between the two highlights your exposure to market risk and illiquidity. For example, a homeowner with $2M in total net worth (including a $1.5M home) might have only $500K in liquid assets, meaning they’d struggle to cover a $300K emergency without selling their home.
Q: Should I refinance my mortgage to improve my net worth calculation?
Refinancing to lower your interest rate or shorten your loan term can improve your long-term net worth by reducing interest payments, but it doesn’t directly boost your net worth calculation unless you’re reducing your mortgage balance faster. If you’re refinancing to tap into home equity (e.g., for renovations or investments), weigh the opportunity cost: using home equity as collateral increases risk if the market declines. Always compare the potential return on the funds against the cost of the new loan. A better strategy for many is to pay down the mortgage aggressively, which directly increases your equity and net worth over time.
