The Short Answers
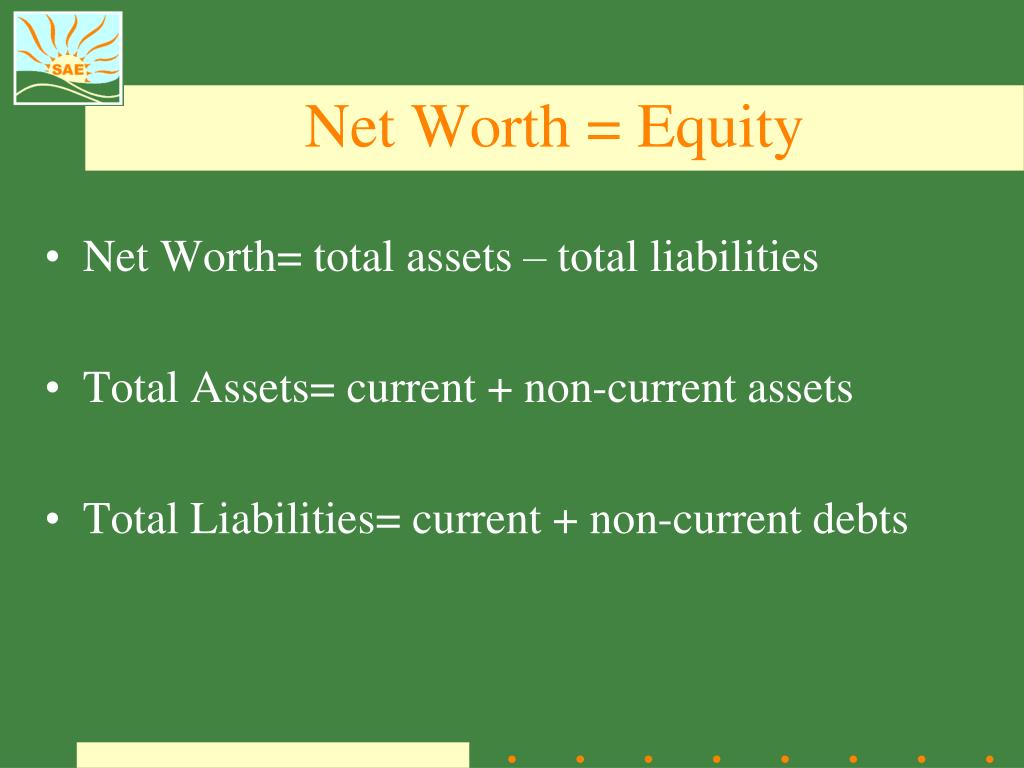
- Net worth total liabilities is calculated by subtracting all debts (liabilities) from total assets—no frills, no exceptions.
- High liabilities relative to assets can signal financial strain, even if net worth appears healthy on paper.
- Not all liabilities are equal: secured debt (like a home loan) behaves differently from unsecured debt (like credit cards).
- Inflation, market volatility, and personal spending habits distort the accuracy of a static net worth total liabilities figure.
- Lenders and investors often look at the ratio of liabilities to assets—not just the net worth number itself.
- Reducing liabilities isn’t always the priority; sometimes, strategic debt (e.g., for income-generating assets) can boost long-term wealth.

Deep Dive: The Full Picture
The net worth total liabilities framework is rooted in double-entry accounting, a system that’s been tracking financial health for centuries. At its core, it’s a binary assessment: what you control (assets) versus what controls you (liabilities). But the modern application of this principle has splintered into specialized fields—tax planning, credit scoring, investment analysis—each with its own interpretation of what constitutes a "healthy" ratio. A hedge fund manager might target a 3:1 assets-to-liabilities ratio to maximize leverage, while a conservative retiree might aim for 5:1 or higher to mitigate risk. The disconnect arises when individuals apply corporate or institutional strategies to personal finance without accounting for liquidity needs, emergency buffers, or lifestyle goals. What’s often overlooked is that net worth total liabilities isn’t just a backward-looking metric. It’s a predictive tool. A sudden spike in liabilities—say, from a business loan or medical debt—can foreshadow cash flow crises months before net worth dips. Conversely, a deliberate increase in liabilities (e.g., refinancing a mortgage to free up cash) might improve short-term flexibility at the cost of long-term interest payments. The challenge lies in distinguishing between operational debt (used to generate income) and consumption debt (used to maintain lifestyle). The latter erodes net worth over time; the former, if managed well, can enhance it.The Context You Need
The net worth total liabilities dynamic shifts depending on life stage. A 30-year-old with student loans and a starter home might have a negative net worth but be on a trajectory toward asset appreciation. A 60-year-old with a paid-off home and retirement accounts might have a high net worth but face liabilities like long-term care insurance premiums. The context matters because debt isn’t a monolith. A mortgage, for example, is a non-recourse liability in many jurisdictions—meaning the lender can’t pursue personal assets beyond the property if you default. Credit card debt, by contrast, is recourse, putting all assets at risk. Cultural attitudes toward debt further complicate the picture. In some societies, taking on debt for education or homeownership is normalized; in others, it’s stigmatized as reckless. These biases seep into financial decisions. Someone raised to view debt as taboo might avoid leveraging assets for growth opportunities, while another might over-leverage, assuming risk will always pay off. The net worth total liabilities equation doesn’t account for these behavioral factors—yet they often dictate whether a "good" ratio becomes a liability in practice.The Mechanics
The calculation itself is straightforward, but execution varies by jurisdiction and accounting standards. In the U.S., for instance, the IRS distinguishes between liquid assets (cash, stocks) and illiquid assets (real estate, collectibles), which can affect how liabilities are offset. If you sell an illiquid asset to pay down debt, the timing of capital gains taxes might alter your effective net worth. Meanwhile, in some European countries, inheritance taxes can create phantom liabilities that don’t appear on a traditional balance sheet but still erode wealth. The mechanics also depend on whether you’re assessing net worth total liabilities for personal use or external evaluation. A bank reviewing a loan application will focus on current liabilities and collateralizable assets, while you might care more about future liabilities (e.g., college tuition) and non-liquid assets (e.g., a family business). This mismatch explains why financial advisors often recommend maintaining an "emergency" net worth buffer—typically 3–6 months of living expenses—separate from your long-term asset allocation.Details That Change the Picture
The biggest misconception about net worth total liabilities is that it’s a one-time calculation. In reality, it’s a range that fluctuates with economic conditions. During a recession, asset values (like stocks or real estate) can plummet while liabilities (like variable-rate loans) become more expensive to service. The result? A net worth that appears robust in a bull market can turn precarious overnight. Conversely, in a low-interest-rate environment, debt servicing becomes cheaper, temporarily inflating the effective net worth by reducing the burden of liabilities. Another critical detail is the type of asset. A portfolio heavy in private equity or venture capital might show high net worth on paper, but those assets aren’t easily liquidated to cover liabilities. Meanwhile, a diversified portfolio with a mix of cash, bonds, and real estate offers more flexibility. The net worth total liabilities ratio becomes meaningless if you can’t convert assets to cash when needed. This is why financial planners often use a "liquidity ratio"—a subset of the broader calculation—to assess short-term resilience."Debt is like a drug—it can stimulate growth, but the withdrawal symptoms are brutal. The key isn’t avoiding debt entirely; it’s ensuring every liability serves a purpose aligned with your long-term goals."
— Sarah Johnson, Certified Financial Planner and former CFO of a Fortune 500 firm
| Scenario | Net Worth Total Liabilities Impact |
|---|---|
| Refinancing a mortgage to a lower rate | Liabilities decrease (lower monthly payment), but total debt remains the same; net worth appears higher due to reduced future obligation. |
| Investing in a rental property with 20% down | Assets increase (property value), but liabilities rise (mortgage); net worth grows if rental income covers debt service. |
| Taking on credit card debt for travel | Liabilities spike with no corresponding asset gain; net worth drops unless the experience generates future income (e.g., networking opportunities). |
| Selling a depreciating asset (e.g., a car) to pay off debt | Assets and liabilities both decrease, but net worth may shrink if the sale price was below market value. |
Conclusion
The net worth total liabilities equation is more than a number—it’s a lens through which to view financial trade-offs. The real skill lies in recognizing when to prioritize reducing liabilities (e.g., during retirement) versus when to strategically increase them (e.g., to acquire income-generating assets). The difference between a healthy and an unhealthy ratio often boils down to intent: Is the debt serving a purpose, or is it a drag on future flexibility? Ignore this distinction, and you risk treating symptoms instead of addressing the root causes of financial stress. For most people, the journey isn’t about achieving a perfect net worth total liabilities ratio but about maintaining one that aligns with their risk tolerance, goals, and external constraints. The markets will fluctuate, personal circumstances will change, and new liabilities will emerge—but the framework remains the same. The goal isn’t to chase a specific number; it’s to use the calculation as a compass, not a destination.Comprehensive FAQs
Q: Can my net worth be negative even if I own assets?
A: Yes. If your liabilities exceed your assets—common among young professionals with student loans or entrepreneurs with high business debt—your net worth will be negative. This isn’t inherently bad if the assets are appreciating (e.g., a startup) or if liabilities are structured to generate income (e.g., a leveraged investment property). However, it signals higher financial risk in the short term.
Q: Do all liabilities affect my net worth equally?
A: No. Secured liabilities (backed by collateral, like a mortgage) are less risky than unsecured liabilities (like credit cards) because the lender’s recourse is limited to the asset. Additionally, tax-deductible liabilities (e.g., mortgage interest in some countries) reduce your effective financial burden, indirectly improving your net worth position. Always prioritize paying down high-interest, non-deductible debt first.
Q: How often should I recalculate my net worth total liabilities?
A: At a minimum, annually—especially if your financial situation is stable. However, if you’ve taken on new debt, sold assets, or experienced significant market changes (e.g., a stock market crash or real estate boom), recalculate quarterly. Automated tools can simplify this, but manual reviews help identify discrepancies (e.g., an asset being undervalued or a liability overlooked).
Q: Can increasing liabilities ever be a good strategy?
A: Absolutely. Leveraging debt to acquire assets that generate passive income (e.g., rental properties, dividend stocks) or accelerate wealth-building (e.g., a business loan for a scalable venture) can be prudent—if the expected return on investment (ROI) exceeds the cost of the debt. The rule of thumb: The higher the ROI, the more aggressive you can be with leverage. Always stress-test the scenario under worst-case conditions (e.g., higher interest rates or lower asset values).
Q: Why do some financial advisors ignore liabilities when discussing net worth?
A: Some advisors focus on gross assets (ignoring liabilities) to simplify messaging, particularly for clients with low debt levels. However, this approach can be misleading. A high gross asset figure masked by significant liabilities might not translate to liquidity or financial security. Reputable advisors will always clarify whether they’re discussing net worth (assets minus liabilities) or gross assets—and adjust strategies accordingly.
Q: What’s the difference between a balance sheet and a net worth statement?
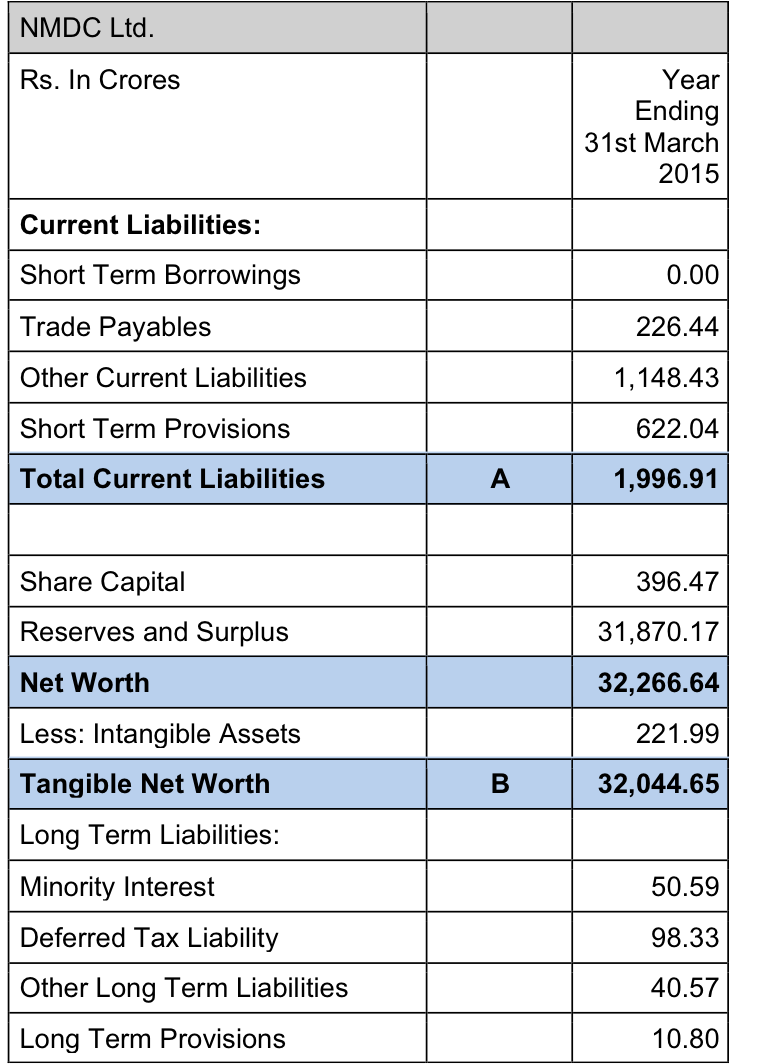
A: A balance sheet (used in accounting) lists assets, liabilities, and equity in a standardized format, often including intangible items like goodwill or patents. A net worth statement (used in personal finance) is simpler: it subtracts total liabilities from total assets to arrive at a single net worth figure. While both serve similar purposes, balance sheets are more detailed and used for complex financial analysis, whereas net worth statements are typically for personal tracking or basic lending assessments.
Q: How do inflation and taxes distort the accuracy of net worth total liabilities?
A: Inflation erodes the real value of assets over time, particularly cash or bonds, while liabilities with fixed payments (e.g., a 30-year mortgage) become cheaper to service in inflationary periods. Taxes further complicate the picture: capital gains taxes on asset sales, property taxes on real estate, or estate taxes on inherited wealth can create hidden liabilities that don’t appear on a standard net worth statement. Always adjust for inflation when comparing net worth over long periods, and account for tax obligations when projecting future liabilities.
