The Complete Overview of what is upper class net worth
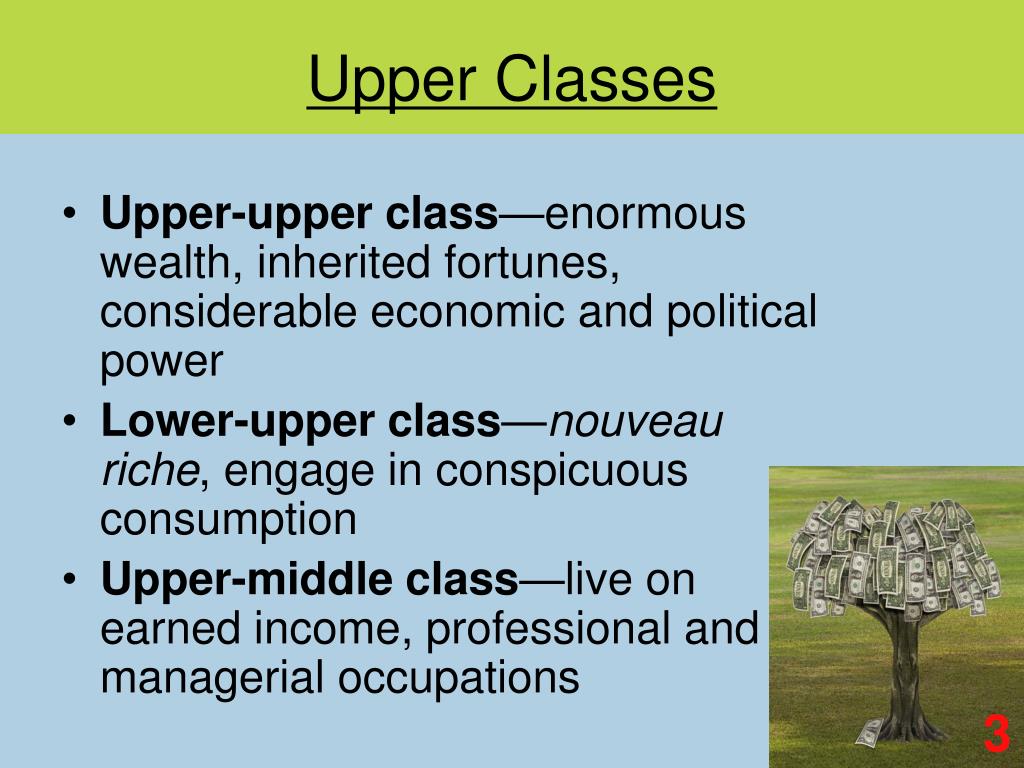
The concept of what is upper class net worth is deeply tied to geography, culture, and the ever-shifting tides of economic power. In the U.S., the Pew Research Center defines the upper class as households earning more than twice the national median income—a figure that, adjusted for inflation, has ballooned from $100,000 in the 1970s to over $250,000 today. Yet net worth tells a different story. A family with $1 million in assets might qualify in a high-cost city like San Francisco, while in Detroit, the same figure could place them firmly in the middle class. The discrepancy stems from the asset concentration of the upper class: their wealth isn’t just in cash but in appreciating assets like stocks, real estate, and business ownership. Globally, the thresholds diverge even more sharply. In Western Europe, the upper class often begins at €5 million in net worth, a figure that buys entry into exclusive networks like the 30% Club or the European Round Table. In Asia, where land ownership and family conglomerates dominate, the bar is set by generational wealth pools—a single property in Hong Kong or a stake in a Korean chaebol can redefine class boundaries overnight. The key insight? What is upper class net worth isn’t a fixed number—it’s a moving target, calibrated by local economics, social capital, and the unspoken rules of elite circles.Historical Background and Evolution
The modern understanding of what is upper class net worth traces back to the Gilded Age, when industrial tycoons like Rockefeller and Carnegie flaunted their fortunes through philanthropy and ostentatious displays of wealth. Yet the financial thresholds of the upper class have always been fluid. During the Great Depression, a net worth of $100,000 (equivalent to ~$1.7 million today) could still secure a place in high society—until the crash redefined the rules. Post-WWII, the rise of the corporate elite and the expansion of Wall Street pushed the bar higher, while the tax reforms of the 1980s (under Reagan) allowed the ultra-wealthy to optimize their net worth through offshore structures and carried interest loopholes. Today, the evolution of what is upper class net worth is shaped by digital assets and private markets. Cryptocurrency fortunes, once the domain of tech bro millionaires, now intersect with traditional wealth—think of a Bitcoin early adopter with a $50 million portfolio suddenly qualifying for the same elite circles as old-money trust-fund families. Meanwhile, the rise of passive income (dividends, rental yields, private equity) has made net worth more opaque than ever. The upper class no longer needs to work for their status; they invest in systems that generate wealth automatically. This shift has blurred the lines between old money and new money, forcing a redefinition of who truly belongs in the upper echelons.Core Mechanisms: How It Works
The mechanics of what is upper class net worth revolve around three pillars: asset accumulation, wealth preservation, and social capital leverage. The upper class doesn’t just earn money—they engineer its growth. Take real estate: a family with $10 million in net worth might own a primary residence in Manhattan, a vacation home in the Hamptons, and a rental portfolio in Miami. Each property appreciates at different rates, diversifying risk while inflating the base net worth over time. Meanwhile, private equity and venture capital allow them to access deals closed to retail investors—think of a $50 million fund that yields 20% annual returns, silently compounding wealth. Wealth preservation is where the upper class truly separates itself. Trusts, dynastic gifting, and offshore entities ensure that fortunes aren’t just maintained but multiplied across generations. A single grantor retained annuity trust (GRAT) can transfer millions tax-free to heirs, while family limited partnerships (FLPs) allow for concentrated stock holdings to be passed down without triggering capital gains taxes. The result? A net worth that grows exponentially while appearing, on paper, to stagnate—because the real value lies in control, not just cash.Key Benefits and Crucial Impact
The advantages of what is upper class net worth extend far beyond personal luxury. They include political influence, educational privilege, and healthcare access—all of which reinforce the class structure. A family with $20 million in net worth can afford to bypass public systems entirely: their children attend elite boarding schools where the endowment fund is larger than the GDP of some nations, and their healthcare is managed by private concierge doctors who operate outside the constraints of insurance networks. The upper class doesn’t just have options—they create them, often through philanthropy that indirectly benefits their own networks. The impact of these thresholds is systemic. Studies show that children of the upper class are 10 times more likely to attend Ivy League universities than their middle-class peers, not just because of test scores but because of legacy admissions, donor connections, and early access to admissions officers. Meanwhile, the tax advantages of high net worth—lower effective tax rates, depreciation write-offs, and capital gains exemptions—ensure that wealth begets more wealth. The upper class doesn’t just ride the tide of economic growth; they shape the tide itself."Wealth isn’t just about money. It’s about the freedom to say no—no to jobs you don’t want, no to lifestyles you don’t need, no to the whims of a market that can’t touch you." — A former Goldman Sachs partner, speaking off the record in 2023
Major Advantages
- Tax Optimization: Access to private wealth managers who structure holdings to minimize liabilities—offshore accounts, charitable trusts, and carried interest strategies that reduce taxable income.
- Exclusive Networks: Membership in clubs (e.g., PGA Tour, Soho House) and organizations (e.g., Young Presidents’ Organization) that provide business and social capital unavailable to lower tiers.
- Educational Privilege: Guaranteed admissions to top universities, early acceptance programs, and legacy advantages that ensure dynastic continuity.
- Healthcare and Longevity: Personalized medical care through concierge medicine, access to experimental treatments, and the ability to self-insure against catastrophic risks.

Comparative Analysis
| Metric | Upper Class (Global Benchmark) | Middle Class (Global Benchmark) |
|---|---|---|
| Net Worth Threshold | $2M–$10M+ (varies by region) | $100K–$1M (liquid + assets) |
| Primary Wealth Sources | Real estate, private equity, inherited assets, business ownership | Salaries, 401(k)s, home equity, small business ownership |
| Tax Optimization Tools | Offshore trusts, GRATs, FLPs, carried interest | Roth IRAs, HSA accounts, standard deductions |
| Social Mobility Barriers | Legacy networks, elite education, political connections | Student debt, housing costs, wage stagnation |
Future Trends and Innovations
The next decade will see what is upper class net worth redefined by digital assets and AI-driven wealth management. Cryptocurrency fortunes—once seen as volatile—are now being institutionalized through Bitcoin ETFs and private blockchain ventures. The upper class is already positioning itself to monetize decentralized finance (DeFi), where smart contracts and yield farming can generate passive income streams that traditional markets can’t match. Meanwhile, AI-powered portfolio management will allow ultra-high-net-worth individuals to automate tax arbitrage at scales previously unimaginable. Another shift is the globalization of elite networks. The old guard—European aristocracy, American dynasties—is being challenged by new money from Asia and the Middle East, where sovereign wealth funds and family offices are buying into Western real estate and art markets. The result? A hybrid upper class where old-world pedigree meets new-world wealth, and the thresholds for entry become even more fluid and competitive. The question isn’t just how much you need to qualify—it’s how you prove your place in an era where wealth is no longer just about dollars but about digital identity, influence, and access.
Conclusion
Understanding what is upper class net worth isn’t just about memorizing numbers—it’s about grasping the invisible systems that sustain privilege. The figures may change, but the mechanics remain: accumulate, preserve, leverage. The upper class doesn’t just have wealth; they engineer its perpetuation, using legal, social, and financial tools to ensure that their children—and their children’s children—never face the same constraints as the rest of society. For outsiders, these thresholds can feel like an impenetrable fortress. But for those already inside, the real game isn’t just about money—it’s about control. The most critical takeaway? What is upper class net worth is less about the size of the bank account and more about the doors it unlocks. And those doors aren’t just opened—they’re reinforced with every generation.Comprehensive FAQs
Q: How does inflation affect what is considered upper class net worth?
Inflation erodes purchasing power, forcing upper-class thresholds to adjust upward over time. For example, a net worth of $1 million in 1990 might have placed a family in the top 1%—today, that same figure would likely rank them in the top 10% in most major cities. The upper class mitigates this by shifting assets into appreciating classes (real estate, private equity, collectibles) that outpace inflation.
Q: Can someone with a high income but low net worth be considered upper class?
Not typically. While income matters, net worth reflects accumulated assets—cash, real estate, investments, and business ownership. A doctor earning $500,000 annually might live like the upper class but could have negative net worth if student loans and mortgages outweigh savings. True upper-class status requires asset concentration that transcends annual paychecks.
Q: How do offshore accounts play into defining upper class net worth?
Offshore accounts are a cornerstone of upper-class wealth preservation. They allow for tax optimization, asset protection, and dynastic gifting—all while keeping wealth hidden from public scrutiny. Countries like Switzerland, the Cayman Islands, and Singapore offer banking secrecy laws that let the ultra-wealthy diversify risk across jurisdictions, ensuring their net worth remains liquid and untraceable where it counts.
Q: Does upper class net worth vary significantly by country?
Absolutely. In Sweden or Denmark, a net worth of €3 million might secure upper-class status, while in Brazil or India, the same figure could place a family in the global top 0.1%. The variance stems from cost of living, tax structures, and cultural definitions of wealth. For instance, in Hong Kong, property ownership alone can redefine class boundaries, whereas in Germany, industrial or family business stakes carry more weight.
Q: How does the upper class maintain wealth across generations?
Through three primary strategies: 1. Trusts and dynastic gifting (e.g., GRATs, FLPs) to transfer wealth tax-efficiently. 2. Education and networking—sending heirs to elite institutions to lock in social capital. 3. Business ownership—passing down stakes in private companies or family offices that generate passive income indefinitely.
Q: Are there any emerging trends that could redefine what is upper class net worth?
Yes. The rise of cryptocurrency and AI-driven wealth management may create new benchmarks. A Bitcoin whale with a $1 billion portfolio could soon qualify for the same elite circles as old-money trust-fund families, while AI-powered portfolio optimization could allow smaller fortunes to grow at exponential rates. The upper class of the future may no longer be defined by traditional assets but by digital influence and algorithmic control over capital.
