The Complete Overview of what is total net worth accounting
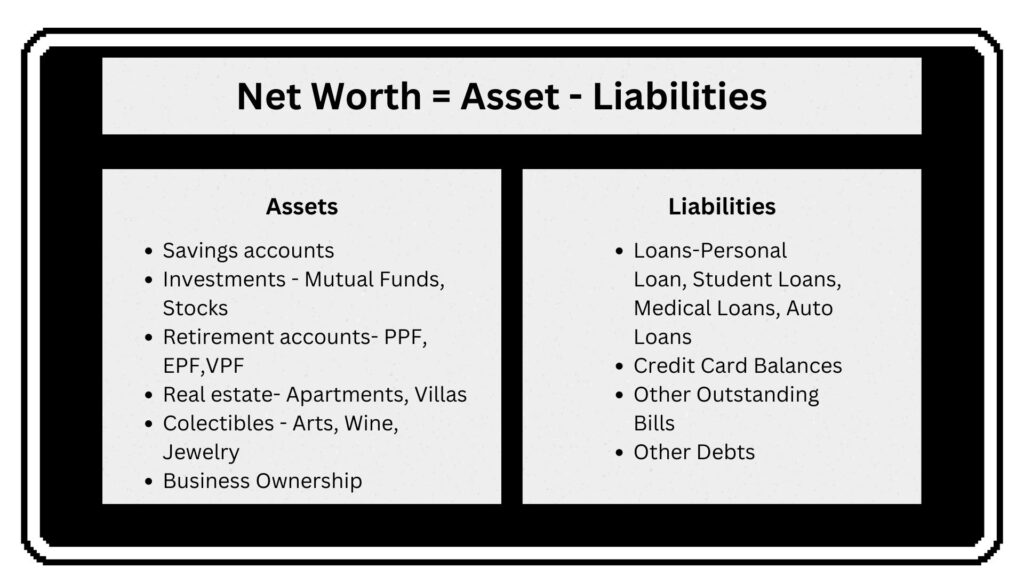
At its core, what is total net worth accounting refers to the systematic process of quantifying an individual’s or entity’s true financial standing—not just the surface-level figures bandied about in press releases or social media. It’s the difference between a publicly traded stock valuation (which reflects market sentiment) and a private equity stake valuation (which requires discounted cash flow models and illiquidity premiums). The discipline emerged from the intersection of forensic accounting, tax law, and corporate restructuring, where the margin for error isn’t percentage points—it’s millions or billions. The confusion arises because total net worth accounting isn’t a single formula. It’s a multi-layered framework that adapts to the subject’s financial ecosystem. For a high-net-worth individual (HNWI), it might involve: - Hard assets: Real estate (with location-specific depreciation rates), art collections (appraised by Sotheby’s or Christie’s), and luxury vehicles (insured at replacement cost). - Soft assets: Intellectual property (patents, trademarks), pending legal settlements, and deferred compensation. - Liabilities: Not just mortgages or credit card debt, but contingent liabilities (lawsuits, guarantees on loans), tax obligations (capital gains, estate taxes), and off-balance-sheet items (unfunded pension liabilities in private companies). For a corporate entity, the scope expands to include goodwill impairments, related-party transactions, and currency translation adjustments—all of which can distort reported earnings but remain critical in total net worth accounting. The key insight? Net worth isn’t a moment-in-time snapshot. It’s a dynamic calculation that must account for time decay (e.g., a vineyard’s harvest cycles), regulatory changes (e.g., new tax treaties), and behavioral factors (e.g., a founder’s tendency to over-leverage private jets).Historical Background and Evolution
The origins of what is total net worth accounting trace back to 19th-century mercantile ledgers, where traders in London and Amsterdam needed to reconcile gold reserves, shipment risks, and credit defaults across continents. By the early 1900s, American railroad tycoons like J.P. Morgan were using consolidated balance sheets to justify mergers—long before GAAP (Generally Accepted Accounting Principles) standardized financial reporting. The real inflection point came in the 1970s, when offshore financial centers (the Cayman Islands, Luxembourg) began offering tax-neutral structures for wealth preservation. Suddenly, total net worth accounting wasn’t just about adding columns—it was about jurisdictional arbitrage. The 1986 Tax Reform Act in the U.S. forced a reckoning. Wealthy families could no longer hide assets in Panama-based shell companies without triggering passive foreign investment company (PFIC) rules. This era birthed the modern family office, where total net worth accounting became a 24/7 discipline. Today, the discipline is split between two schools of thought: 1. The Conservative Approach: Used by ultra-high-net-worth individuals (UHNWIs) and sovereign wealth funds, where assets are valued at liquidation prices (even if illiquid) and liabilities include worst-case scenarios (e.g., a 50% haircut on private equity stakes). 2. The Optimized Approach: Employed by private equity firms and strategic acquirers, where assets are marked at strategic value (what a buyer would pay) and liabilities are net-present-valued (discounted for time and risk). The evolution hasn’t been linear. The 2008 financial crisis exposed gaps in total net worth accounting for leveraged institutions, leading to stress-testing protocols that now require three-year rolling projections. Meanwhile, cryptocurrency introduced a new variable: volatility-adjusted net worth, where a $100 million Bitcoin holding might swing by 20% in a week—yet still be classified as an asset in total net worth accounting.Core Mechanisms: How It Works
The mechanics of total net worth accounting hinge on three pillars: valuation methodology, liability recognition, and jurisdictional alignment. Let’s break it down. First, asset valuation isn’t a one-size-fits-all process. A publicly traded stock might use trailing twelve-month earnings, but a private company stake requires discounted cash flow (DCF) analysis—factoring in growth rates, exit multiples, and illiquidity discounts (typically 20–40%). Real estate is further segmented: - Residential properties: Valued via comparable sales (comps) or appraisal reports (for mortgages). - Commercial real estate: Assessed using capitalization rates (cap rates) and rental yield projections. - Land: Often held at historical cost unless zoning changes trigger a revaluation. The second layer is liability recognition. Most people stop at mortgage debt or credit cards, but total net worth accounting demands a comprehensive audit: - Contingent liabilities: Unfunded pension obligations, guarantees on loans, or pending lawsuits. - Tax liabilities: Deferred tax assets, estate taxes, and unpaid capital gains (even if deferred). - Off-balance-sheet items: Unrecorded liabilities (e.g., a private jet leased but not owned) or related-party transactions (e.g., a founder loaning money to their company at below-market rates). The third mechanism is jurisdictional alignment. A U.S. citizen with assets in Monaco must account for: - Monaco’s wealth tax (1% on assets over €6 million). - U.S. FBAR reporting (Foreign Bank Account Report for balances over $10,000). - Double taxation treaties (e.g., the U.S.-Switzerland tax treaty on dividends). A misstep here can trigger penalties of 30–50% of the unpaid tax—far exceeding the value of the asset itself.Key Benefits and Crucial Impact
The primary value of what is total net worth accounting lies in its precision under uncertainty. In an era where market cap can shift overnight (see: GameStop’s 2021 volatility), a static net worth figure is meaningless. Total net worth accounting provides three critical advantages: 1. Risk mitigation: By stress-testing assets against black swan events (e.g., a 30% drop in art market values), families can diversify holdings before a crash. 2. Tax optimization: Identifying undeclared liabilities (e.g., unreported rental income) can save millions in back taxes—or expose fraud risks. 3. Succession planning: A total net worth accounting exercise often reveals hidden illiquidity (e.g., a family-owned vineyard with no buyer) that derails estate plans. The discipline also serves as a negotiation tool. When a private equity firm bids for a company, they don’t just look at EBITDA. They demand a total net worth accounting breakdown to assess: - Hidden debt (e.g., off-balance-sheet leases). - Regulatory risks (e.g., pending environmental fines). - Key person dependency (e.g., a CEO whose departure would collapse revenue)."Total net worth accounting isn’t about hiding numbers—it’s about telling the truth in a language that courts, regulators, and markets understand. The families who master this don’t just preserve wealth; they engineer its growth by removing the variables that destroy it." — James McCormack, Partner at Forbes Advisory Group
Major Advantages
- Accurate wealth transfer: Without total net worth accounting, heirs often inherit liabilities they didn’t know existed (e.g., unfunded trusts, pending lawsuits). A proper audit ensures clean title in estates.
- Leverage optimization: Banks and private lenders only extend credit based on verified net worth. A total net worth accounting report can unlock $100M+ in financing for a business expansion.
- Philanthropic efficiency: Donors can maximize tax deductions by structuring gifts through donor-advised funds (DAFs) or charitable remainder trusts—but only if their total net worth accounting correctly values the asset being donated.
- Conflict resolution: Divorces, shareholder disputes, and family office splits often hinge on disputed asset valuations. A total net worth accounting report becomes the binding arbitration document.
- Exit strategy clarity: Founders of private companies often misjudge their true liquidity. A total net worth accounting exercise reveals whether an IPO, sale to a competitor, or ESOP is viable.

Comparative Analysis
| Aspect | Traditional Net Worth Calculation | Total Net Worth Accounting |
|---|---|---|
| Asset Valuation | Market value (e.g., stock price, Zillow estimate) | Strategic value (DCF for private equity, illiquidity discounts, appraised fair market value) |
| Liability Treatment | Only recorded debts (mortgages, loans) | Contingent liabilities, tax obligations, off-balance-sheet items, worst-case scenarios |
| Jurisdictional Compliance | Domestic tax filings only | Cross-border tax treaties, FBAR, CRS (Common Reporting Standard), local wealth taxes |
Future Trends and Innovations
The next decade will see total net worth accounting evolve in two radical directions: 1. AI-driven valuation models: Machine learning is already used to predict art market trends and adjust commercial real estate cap rates in real time. Expect dynamic net worth dashboards that update hourly based on macroeconomic shifts (e.g., interest rate hikes). 2. Tokenized asset integration: As central bank digital currencies (CBDCs) and blockchain-based securities gain traction, total net worth accounting will need to incorporate smart contract liabilities (e.g., automated margin calls) and DeFi exposure (e.g., unsecured lending platforms). The biggest challenge? Regulatory fragmentation. While the U.S. SEC pushes for XBRL tagging of private company filings, the EU’s MiCA framework treats crypto assets differently, and Singapore’s MAS has its own wealth management disclosure rules. The result? Total net worth accounting will increasingly rely on jurisdiction-specific algorithms—not just spreadsheets.
Conclusion
What is total net worth accounting isn’t a niche concern for accountants. It’s the operating system of wealth preservation in the 21st century. Whether you’re a family office managing $5 billion, a tech founder eyeing an exit, or a tax strategist optimizing a trust, the discipline separates the amateurs from the architects. The mistake isn’t in underestimating liabilities—it’s in ignoring the system entirely. The irony? Most people who could benefit from total net worth accounting never encounter it because they assume their wealth is simple. But wealth, by definition, is complex. And complexity demands rigor. The families who thrive in the next economic cycle won’t be the ones with the highest publicly stated net worth. They’ll be the ones who mastered the accounting behind it.Comprehensive FAQs
Q: How often should I update my total net worth accounting?
For high-net-worth individuals, a quarterly review is standard—especially if you hold illiquid assets (private equity, real estate, art). Ultra-high-net-worth families often conduct annual deep dives with forensic accountants, while public figures (celebrities, politicians) may update monthly due to media scrutiny and volatility. The key is aligning the frequency with asset liquidity and risk exposure.
Q: Can total net worth accounting reduce my tax bill?
Absolutely—but only if done correctly. A total net worth accounting exercise can identify undeclared income (e.g., royalties from foreign entities), overstated deductions (e.g., charitable donations without receipts), and jurisdictional arbitrage opportunities (e.g., moving assets to a tax-favorable trust). However, aggressive tax avoidance (e.g., sham trusts) can trigger penalties up to 75% of the underpaid tax. Always work with tax strategists who specialize in wealth structuring.
Q: What’s the biggest mistake people make in total net worth accounting?
Underestimating illiquidity. Many assume a private company stake is worth its last funding round valuation, but total net worth accounting requires discounting for illiquidity (20–40%) and market risk. Another common error? Ignoring contingent liabilities—like unfunded pension obligations or pending lawsuits. A $500 million net worth can evaporate overnight if a $100 million judgment isn’t accounted for.
Q: Is total net worth accounting only for the ultra-rich?
No—but it becomes critical at higher thresholds. If your liquid assets exceed $5 million, you’re likely dealing with complex jurisdictions, trusts, and private holdings that demand total net worth accounting. Even at $1 million, if you own real estate abroad or have offshore entities, a basic audit can prevent tax audits or asset seizures. The discipline scales with complexity, not just dollar amount.
Q: How do I get started with total net worth accounting?
1. Gather documents: Bank statements, property deeds, investment account summaries, tax returns (last 5 years), insurance policies, and any legal agreements (trusts, partnerships). 2. Classify assets: Separate liquid (cash, stocks) from illiquid (real estate, private equity) and intangible (IP, pending lawsuits). 3. Engage specialists: A CPA for tax implications, a forensic accountant for asset valuation, and a wealth structuring attorney for jurisdiction-specific rules. 4. Use software: Tools like WealthForge, Black Diamond, or eMoney Advisor can help aggregate data, but manual review is essential for accuracy.
