Common Myths About What Is Considered Upper Middle Class in America
The upper middle class is often reduced to a single metric: income. But that oversimplification ignores the role of education, occupation, and regional economics. The myth that you can neatly box this demographic into a salary range ignores the fact that a professor in Boston and a mid-level corporate lawyer in Dallas may both earn $150,000—but their financial realities couldn’t be more different. One might be drowning in student debt; the other could be saving aggressively for retirement. The upper middle class isn’t a monolith; it’s a constellation of lifestyles held together by a shared sense of economic security, not by a shared paycheck. Another persistent myth is that the upper middle class is homogeneous in terms of race and ethnicity. The reality is far more complex. While white-collar professions dominate the stereotype, the upper middle class includes doctors of color, Black entrepreneurs, and Latino professionals who’ve climbed the ladder through education and grit. The assumption that this tier is predominantly white erases the contributions of communities that have historically faced systemic barriers. Even within the same income bracket, experiences vary wildly. A Black family earning $180,000 in Chicago might face different financial pressures than a white family with the same income in Seattle—housing discrimination, wealth gaps, and access to opportunity all play a role.Myth 1: The Upper Middle Class Is Defined Solely by Income
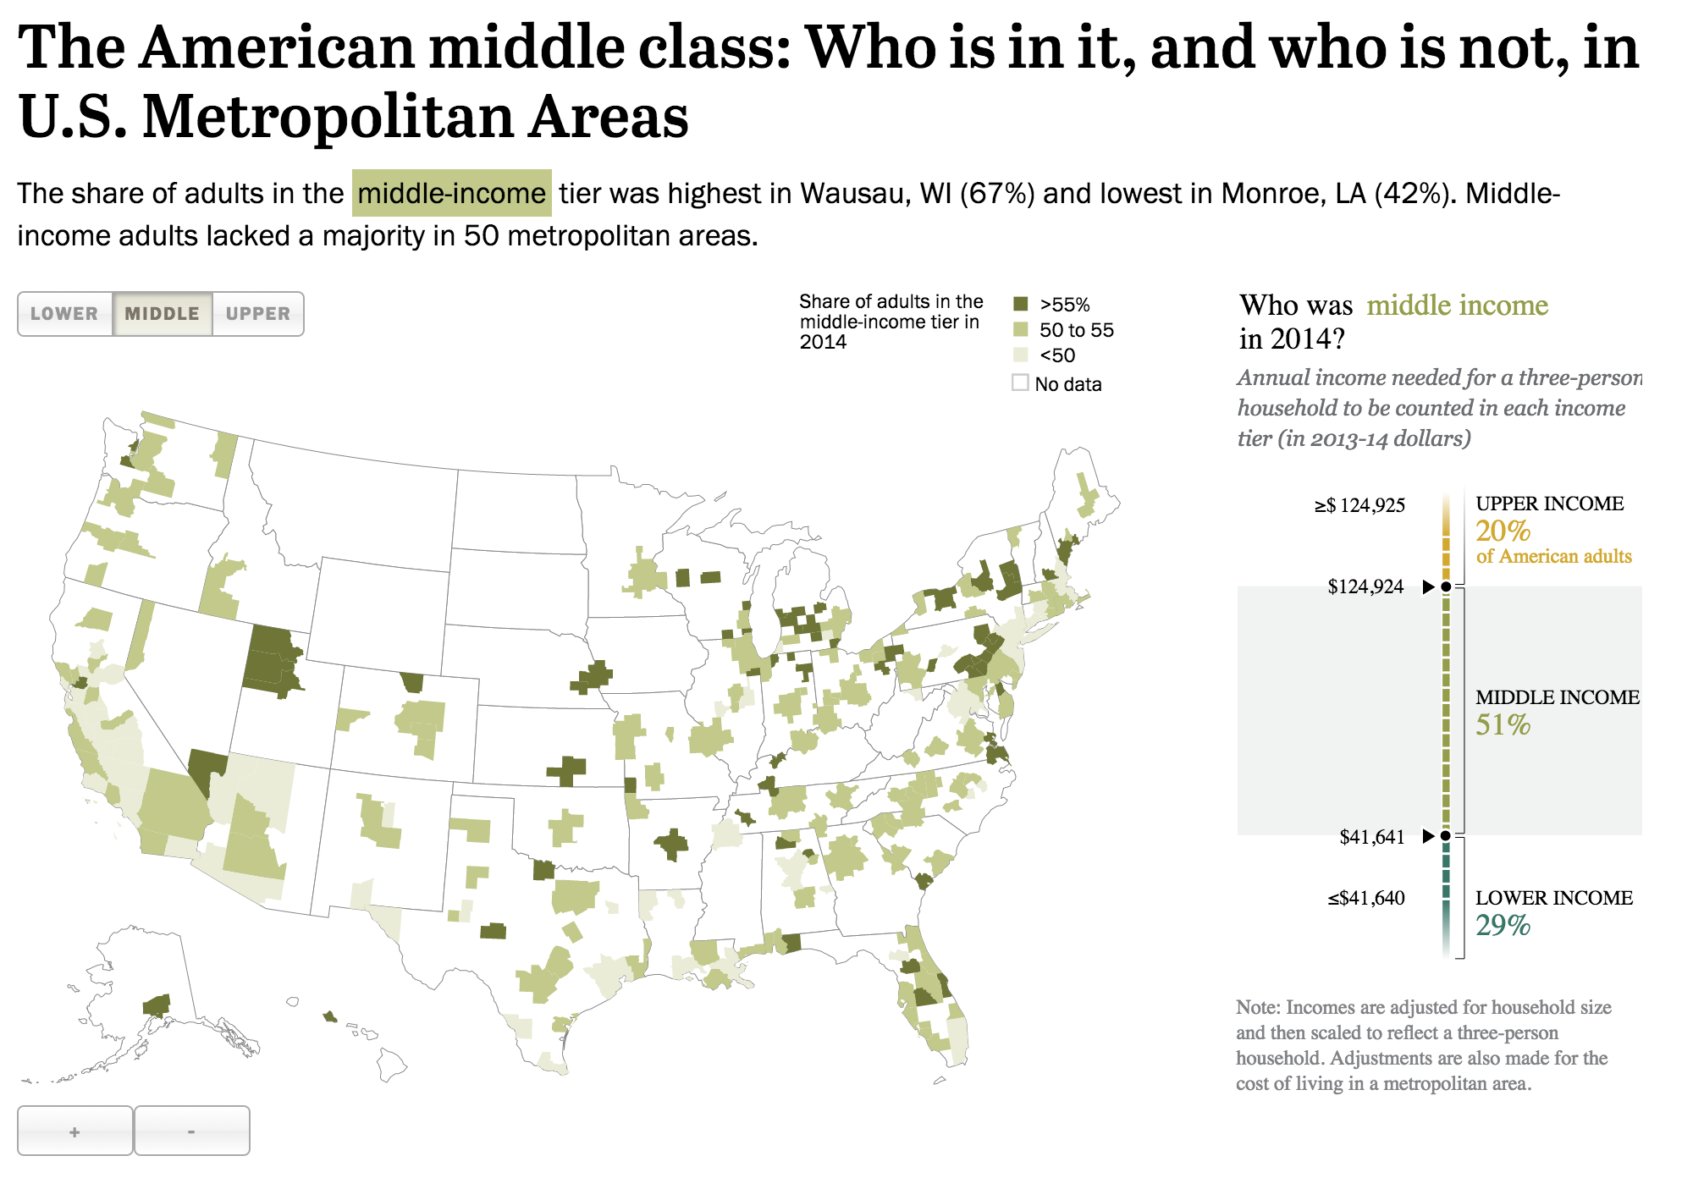
The idea that what is considered upper middle class in America boils down to a salary range is a convenient fiction. Economists like Richard V. Reeves of the Brookings Institution argue that income alone fails to capture the full picture. A family earning $120,000 in rural Nebraska might live comfortably, while the same income in Manhattan could leave them stretched thin. The upper middle class isn’t just about how much you make; it’s about how much you keep after taxes, healthcare costs, and childcare. A software engineer in Austin with no dependents might save aggressively, while a dual-income couple in Los Angeles with two kids could be house poor. The Pew Research Center’s classification—where the upper middle class falls between the 60th and 90th percentiles of household income—is a starting point, but it’s far from the whole story. What matters just as much is asset accumulation. A family with $500,000 in savings and a paid-off home might feel secure at a lower income than someone with no liquid assets. The upper middle class is less about a fixed number and more about a psychological threshold: the point at which financial stress becomes optional.Myth 2: You Need a Six-Figure Salary to Be Upper Middle Class
The six-figure salary is often treated as the golden ticket, but the truth is more nuanced. In high-cost areas like San Francisco or New York, a single earner making $150,000 might still feel the pinch, while in smaller cities, a household income of $100,000 could grant access to the same lifestyle perks. The upper middle class isn’t about hitting a specific number; it’s about relative comfort. A couple in Phoenix earning $130,000 might live like upper middle class—owning a home, sending kids to good schools, and taking vacations—while their counterparts in Boston might be struggling to afford the same quality of life. Education plays a critical role here. A nurse with an advanced degree might earn $120,000 and live comfortably, while a recent college graduate in the same city could be drowning in debt. The upper middle class isn’t just about salary; it’s about educational capital. Those with advanced degrees often have better job security, higher earning potential, and access to networks that open doors. Without accounting for education, the income threshold becomes meaningless.Myth 3: The Upper Middle Class Is the Same Everywhere
The assumption that what is considered upper middle class in America applies uniformly across the country is a geographical fallacy. Cost of living, local taxes, and housing markets create vast disparities. A family earning $160,000 in Houston might own a spacious home, send their kids to top-rated public schools, and still have disposable income. The same family in San Francisco would likely be renting a cramped apartment, sending their children to private school, and watching their savings dwindle under the weight of high taxes and exorbitant childcare costs. Even within states, the definition varies. In Texas, where there’s no state income tax, a household earning $140,000 might feel secure, while in California, the same income could leave them financially vulnerable. The upper middle class in America isn’t a national standard; it’s a local currency. What qualifies in one region might not in another, making broad generalizations not just unhelpful but misleading.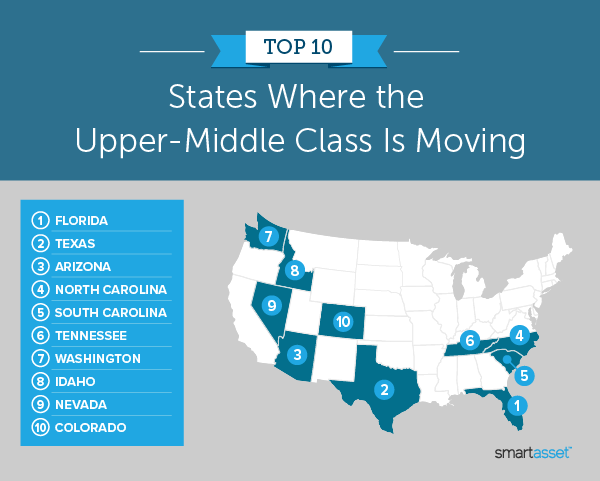
What Holds Up to Scrutiny
At its core, what is considered upper middle class in America hinges on three pillars: income, education, and asset accumulation. Income provides the foundation, but education determines how far that income stretches. A family with advanced degrees can navigate financial challenges more effectively than one without, even if their salaries are similar. Asset accumulation—homeownership, retirement savings, investments—is where the upper middle class separates itself from the middle class. It’s not just about how much you make; it’s about how much you control. The upper middle class is also defined by cultural capital. This isn’t just about attending Ivy League events; it’s about the unspoken rules of access. It’s knowing which neighborhoods are safe, which schools are prestigious, and which social circles offer opportunities. It’s the ability to navigate systems—healthcare, education, real estate—that are often designed for those who already have a foothold. Without this cultural capital, even high earners can feel excluded from the upper middle class."Class isn’t just about money. It’s about who gets to play by the rules—and who has to fight just to get a seat at the table." — Kathryn Edin, sociologist and author of $2.00 a Day
| Common Belief | What the Evidence Says |
|---|---|
| The upper middle class earns between $150,000 and $250,000 annually. | Income thresholds vary by region; Pew Research places it between the 60th and 90th percentiles, which translates to roughly $100,000–$200,000 in most areas, but higher in coastal cities. |
| You need a college degree to be upper middle class. | While education helps, some upper middle-class families achieve stability through skilled trades, entrepreneurship, or inherited wealth without formal degrees. |
| The upper middle class is mostly white and suburban. | Demographics vary; urban professionals, professionals of color, and rural entrepreneurs all occupy this tier, though racial wealth gaps persist. |
Why the Confusion Persists
The upper middle class is a moving target because America’s economic landscape is constantly shifting. Inflation, housing bubbles, and changes in tax policy all reshape what it means to live comfortably. What was once considered upper middle class in the 1990s—say, a household income of $100,000—now feels like a stretch in many parts of the country. The rise of the gig economy and remote work has further blurred the lines, making traditional markers of class—like a steady paycheck and a corporate job—less reliable indicators. Cultural narratives also play a role. Movies, TV shows, and social media paint a glamorous picture of the upper middle class—think of the wealthy lawyers in Suits or the affluent parents in The Real Housewives—when in reality, many upper middle-class families are just trying to keep their heads above water. The gap between perception and reality fuels the confusion. People aspire to the lifestyle they see portrayed, but the financial reality is far more modest. This disconnect makes it harder to define the group with precision.
Conclusion
The question of what is considered upper middle class in America isn’t just about numbers—it’s about power, privilege, and possibility. It’s the class where people can afford to take risks, where education opens doors, and where geography becomes a defining factor. The upper middle class isn’t a fixed category; it’s a living, breathing entity that adapts to economic shifts, cultural changes, and regional differences. What unites its members isn’t a single income threshold, but a shared sense of security—even if that security is fragile. Understanding this class requires looking beyond the paycheck. It’s about recognizing the role of education, assets, and cultural capital in shaping financial stability. It’s about acknowledging that the upper middle class isn’t a homogeneous group but a diverse collection of individuals who share one thing: the ability to navigate a system that rewards them for their efforts. The challenge isn’t just defining the upper middle class—it’s understanding how that definition changes with time and place.Comprehensive FAQs
Q: Is the upper middle class the same as the professional class?
A: Not necessarily. While many upper middle-class individuals hold professional jobs—lawyers, doctors, engineers—the category also includes skilled tradespeople, entrepreneurs, and even some high-earning artists or writers. The key difference is economic stability rather than occupation. A successful freelancer or a master plumber with significant savings and assets could qualify, even if they don’t have a traditional white-collar job.
Q: How does regional cost of living affect what’s considered upper middle class?
A: Dramatically. In low-cost areas like Mississippi or West Virginia, a household income of $80,000 might grant access to upper middle-class comforts—homeownership, private school tuition, vacations—while in high-cost cities like San Francisco or New York, the same income could leave a family struggling. The upper middle class in America is localized; what qualifies in one region may not in another.
Q: Can you be upper middle class without a college degree?
A: Yes, but it’s more challenging. Many upper middle-class families achieve stability through inherited wealth, entrepreneurship, or high-earning skilled trades (e.g., electricians, IT specialists, or real estate investors). However, education—particularly advanced degrees—often provides a safety net, better job security, and higher earning potential, making it easier to accumulate assets.
Q: How does the upper middle class differ from the lower middle class?
A: The primary distinction lies in asset accumulation and financial flexibility. The lower middle class often lives paycheck to paycheck, with little savings or investment. The upper middle class, by contrast, typically has emergency savings, retirement funds, and home equity, allowing them to weather economic downturns without drastic lifestyle changes. They also have greater access to cultural and social capital, such as private schools or exclusive networks.
Q: Is the upper middle class growing or shrinking?
A: Data suggests it’s shrinking in relative terms. While the number of upper middle-class households has grown in absolute numbers, the gap between the wealthy and the middle class has widened. Economic inequality, stagnant wages, and rising costs of living—especially housing—have made it harder for families to cross into this tier. Some economists argue that the upper middle class is becoming more precarious, with fewer families able to pass wealth to the next generation.
Q: What’s the biggest misconception about the upper middle class?
A: That it’s a homogeneous, privileged group with little financial stress. In reality, many upper middle-class families work hard to maintain their status, facing pressures like student debt, healthcare costs, and the expectation to send kids to elite schools. The upper middle class isn’t about effortless wealth—it’s about managed scarcity, where financial stress is contained but never entirely absent.
Q: How does the upper middle class compare to the top 1%?
A: The upper middle class is far more diverse in terms of occupation, race, and geography, while the top 1% is dominated by inherited wealth, corporate executives, and financial elites. The upper middle class may earn six figures, but they’re not building generational wealth. The top 1% often owns assets that appreciate—stocks, real estate, businesses—while the upper middle class relies more on steady income and savings to maintain their lifestyle.
Q: Can you lose upper middle-class status?
A: Absolutely. Job loss, divorce, medical emergencies, or economic downturns can push upper middle-class families into financial instability. Unlike the wealthy, who can often weather setbacks, the upper middle class has less of a cushion. A single major expense—like a $50,000 medical bill or a job transition—can derail years of careful financial planning. This fragility is why many in this class work tirelessly to preserve their status.
