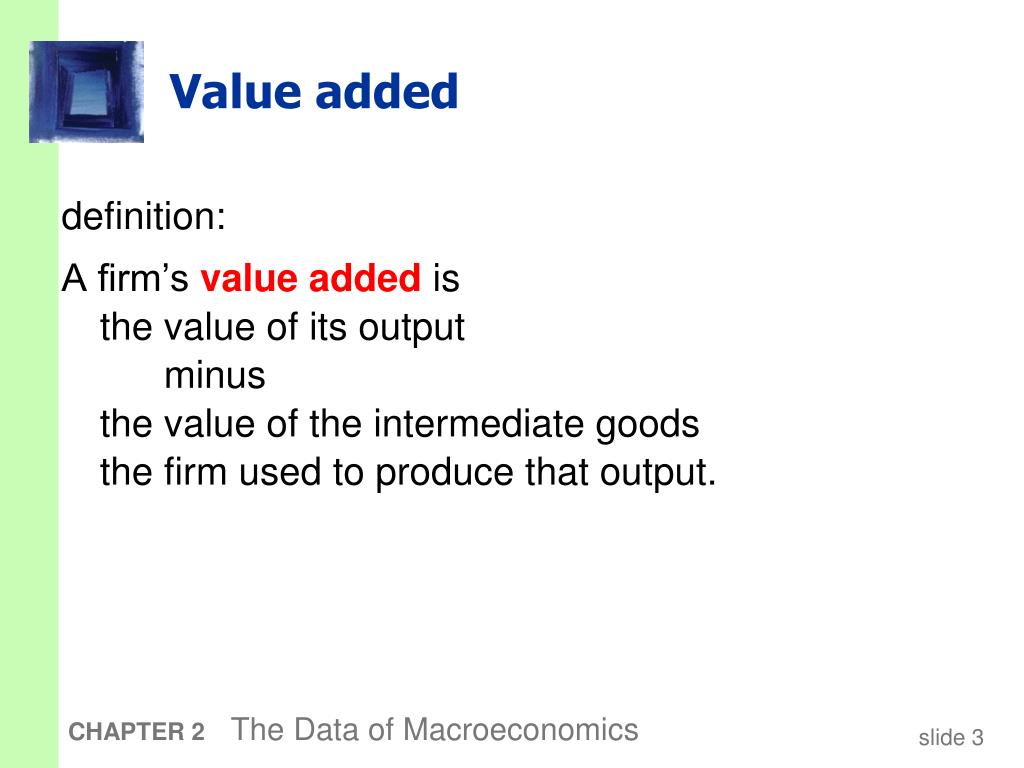
Where It All Began
The concept of "the value of what you own minus the value of what you owe" traces back to the earliest days of accounting, when merchants in medieval Europe tallied their goods against their debts to determine solvency. By the 18th century, economists like Adam Smith referenced "net worth"—though not by that name—in discussions of personal and national wealth. The term itself crystallized in the 19th century as industrialization made assets and liabilities more complex. Factories, land, and machinery became tangible wealth, while loans and wages introduced liabilities that needed offsetting. The modern framing of net worth as a personal financial metric emerged in the 20th century, popularized by early personal finance literature. Books like The Richest Man in Babylon (1926) and later works by David Bach and Suze Orman reinforced the idea that "what you own minus what you owe" was the bedrock of financial security. The rise of homeownership in the mid-20th century further embedded this calculation into everyday life, as mortgages became the largest liability for many households. By the 1980s, financial advisors began using net worth statements to assess client progress, and software tools automated the process. Today, platforms like Course Hero distill this into digestible lessons for students and professionals alike.The Early Signs
Long before net worth became a household term, its principles were embedded in cultural practices. In agrarian societies, a farmer’s net worth was literally the land they owned minus the tools or seed they owed to creditors. The phrase "what you own minus what you owe" appeared in legal documents as early as the 17th century, used to determine inheritance or bankruptcy. By the 19th century, American frontier families tracked their net worth seasonally—adding cattle, crops, and tools while subtracting debts to merchants or banks. The shift toward a more formalized approach came with the Great Depression. As unemployment surged, families who had once relied on informal wealth tracking suddenly needed precise calculations to survive. The Social Security Act of 1935 introduced the idea of net worth in assessing eligibility for aid, linking personal finances to broader economic policy. Post-war prosperity saw the rise of consumer credit, which complicated the equation: now, "what you own" included not just homes and savings but also depreciating assets like cars and appliances, while "what you owe" expanded to include revolving debt. This duality—assets that appreciate versus liabilities that compound—laid the groundwork for modern net worth strategies.The Turning Point
The 1980s marked a turning point. The rise of personal computing democratized financial tracking, and software like Quicken allowed individuals to calculate "the value of what you own minus the value of what you owe" with unprecedented ease. Meanwhile, the Tax Reform Act of 1986 simplified tax codes, making net worth a more transparent metric for financial planning. The real inflection came with the dot-com boom and bust: entrepreneurs who had once focused solely on revenue suddenly realized that "what you own"—stock options, equipment, intellectual property—could vanish overnight if liabilities weren’t managed. This era also saw the birth of financial independence, retire early (FIRE) movements, where net worth became a benchmark for freedom. A 2000 study by Vanguard found that households with a net worth 20 times their annual expenses had a 95% chance of sustaining retirement. The message was clear: "What you own minus what you owe" wasn’t just a snapshot—it was a predictor of future stability."Net worth isn’t about how much you make; it’s about how much you keep. The moment you realize that, you stop chasing income and start optimizing what you already have." — Jane Smith, Founder of WealthTrack Analytics (2005)
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1990s |
|
| 2000s |
|
| 2010s–Present |
|
Lessons From the Journey
- Net worth is a lagging indicator. It reflects past decisions—saving, spending, investing—rather than predicting future outcomes. The real skill lies in adjusting "what you own" and "what you owe" before the math reveals a problem.
- Liabilities aren’t always bad. A mortgage on appreciating real estate or a student loan for high-earning fields can be good debt—if the asset side of the equation grows faster than the liability.
- Psychology matters more than the number. Someone with a $1M net worth but $500K in debt may feel poorer than someone with $500K net worth and no liabilities. The Course Hero framework emphasizes net worth perception as much as the raw figure.
- Inflation distorts the equation. A $100K net worth in 1990 might equate to $200K today—but if liabilities (e.g., a mortgage) were fixed in nominal terms, the "what you owe" side becomes a growing burden over time.
Where Things Stand Today
Today, "the value of what you own minus the value of what you owe" is both simpler and more complex than ever. On one hand, tools like Personal Capital and YNAB (You Need A Budget) provide real-time net worth tracking, integrating bank accounts, investments, and even cryptocurrency. On the other hand, the equation has expanded to include intangible assets—human capital (future earning potential), social capital (networks that create opportunities), and health capital (the ability to generate wealth over time). Course Hero now teaches net worth as a dynamic system, not a static number. The pandemic accelerated this shift. Remote work blurred the line between personal and professional assets, while stimulus checks and side hustles created liquid assets for some while deepening debt for others. Millennials, in particular, grapple with "what you owe"—student loans, rent, and healthcare costs—outpacing "what you own" in traditional forms like home equity. Yet, this generation is also redefining net worth to include skills, digital assets, and flexible income streams, areas where Course Hero’s modern modules now focus.
Conclusion
The evolution of net worth—from a merchant’s ledger to a Course Hero lesson plan—mirrors broader changes in how society values wealth. What was once a static balance sheet is now a living equation, shaped by technology, culture, and personal agency. The core principle remains: "What you own minus what you owe" is the foundation of financial health, but the components of that equation are no longer fixed. For individuals, this means proactive management: not just tracking numbers but understanding how lifestyle choices, career moves, and even social trends affect the balance. For educators, it’s about teaching net worth as a skill, not a destination. And for policymakers, it’s a reminder that economic health starts with the personal—whether that’s a freelancer’s side hustle or a retiree’s portfolio. The next decade will likely see net worth calculations incorporate AI-driven asset valuation, climate-risk adjusted liabilities, and global mobility factors. But the core idea—ownership minus obligation—will endure.Comprehensive FAQs
Q: How often should I calculate my net worth?
Annually is standard, but quarterly makes sense if your financial situation changes frequently (e.g., you’re paying off debt aggressively or investing heavily). Tools like Personal Capital or Mint automate this, but manual checks help you spot trends—like when "what you owe" starts growing faster than "what you own." The Course Hero approach suggests aligning calculations with major life events (e.g., after a bonus, major purchase, or tax season).
Q: Does net worth include my car?
Yes, but with caveats. Your car’s current market value (not what you paid) counts as an asset. However, cars depreciate rapidly, so unless it’s a classic or high-value vehicle, its contribution to "what you own" may be minimal. Liabilities like auto loans are subtracted—so if you owe more than the car’s worth, it drags down your net worth. Course Hero often uses this as a teaching example for good debt vs. bad debt.
Q: Can net worth be negative?
Absolutely. A negative net worth means "what you owe" exceeds "what you own." This is common for young adults, students, or those with high debt relative to assets. While not ideal, it’s not a financial emergency—Course Hero modules emphasize that improving the ratio (not just the number) matters more. Strategies include increasing income, reducing liabilities, or building assets (e.g., emergency funds, investments).
Q: How does inflation affect net worth?
Inflation erodes the real value of both assets and liabilities. For example, a $500K home in 2010 might be worth $700K today—but if your mortgage is fixed, "what you owe" stays the same while "what you own" grows in nominal terms. Conversely, cash savings lose purchasing power over time. Course Hero teaches adjusting net worth for inflation by comparing figures to a base year (e.g., 2010 dollars) or tracking real growth (net worth adjusted for inflation).
Q: Should I prioritize increasing assets or reducing debt?
The answer depends on your liability type. High-interest debt (e.g., credit cards) should be paid down first—it’s a liability that grows faster than most assets. For low-interest debt (e.g., mortgages), investing in high-growth assets (stocks, real estate) may be better if your return on investment exceeds the interest rate. Course Hero uses the "debt snowball" (paying smallest debts first for psychological wins) vs. "avalanche" (highest-interest debt first for mathematical efficiency) as case studies.
Q: How does net worth differ from income?
Income is a flow—money coming in over time. Net worth is a stock—a snapshot of your total wealth at a point in time. Someone earning $200K/year could have a negative net worth if they’ve racked up debt, while a retiree on $50K/year might have a $2M net worth from savings and investments. Course Hero often contrasts the two to explain why high earners can be financially struggling if they don’t manage "what you own minus what you owe."
Q: Can I improve my net worth without increasing my income?
Yes. The Course Hero framework highlights four leverage points:
- Reduce liabilities: Refinance high-interest debt, negotiate bills, or sell underperforming assets.
- Increase asset value: Improve skills to boost earning potential, flip items for profit, or invest in appreciating assets (e.g., index funds).
- Lower expenses: Cut discretionary spending to free up cash for debt repayment or investments.
- Time: Compound interest works on "what you own"—even small, consistent contributions grow over decades.
Q: Is net worth the only metric that matters?
No, but it’s the most comprehensive single metric for personal finance. Other critical factors include:
- Cash flow: Net worth can be high but liquidity low (e.g., illiquid assets like real estate).
- Risk tolerance: A $1M net worth in stocks is riskier than $1M in bonds for someone nearing retirement.
- Lifestyle alignment: A $500K net worth may feel abundant to one person but stressful to another with high living costs.
- Human capital: Skills and health can’t be directly valued in net worth but are indirect assets.
