Where It All Began
The origins of net worth based on current asset costs trace back to the 19th century, when railroads and industrial conglomerates first required liquidity assessments. Early corporate charters demanded audits that reflected "fair market value," not just depreciated book value. But the practice remained niche until the 1970s, when inflation eroded the purchasing power of fixed asset valuations. Accountants and regulators began pushing for market-adjusted net worth in financial disclosures, though resistance was fierce. Banks, wary of loan risk, preferred conservative estimates. The SEC’s 1980s reforms forced public companies to disclose "intrinsic value" alongside book value—a half-measure that satisfied regulators but confused retail investors. The real inflection point came with the rise of index funds. Vanguard’s John Bogle argued that passive investing demanded real-time net worth tracking to benchmark performance. His funds became the first to publish daily NAVs (net asset values) based on closing prices, not historical costs. The move was revolutionary: for the first time, an investor could know their portfolio’s worth at any moment, not just at year-end. Institutional investors took notice. By the 1990s, private equity firms like Blackstone began valuing portfolio companies quarterly using current asset cost multiples, a practice that later bled into family offices and ultra-high-net-worth (UHNW) portfolios.The Early Signs
The late 1990s saw the first cracks in the system. Dot-com valuations soared beyond any rational multiple of revenue, while traditional asset classes like real estate stagnated. For the first time, net worth based on current asset costs became a tool of speculation as much as strategy. Founders of companies like Webvan or Pets.com saw their personal wealth balloon overnight—only to evaporate when the bubble burst. The lesson? Asset valuations weren’t neutral; they were a reflection of market sentiment, liquidity, and even political risk. Meanwhile, the rise of hedge funds introduced another variable: leverage. A fund’s net worth could swing wildly based on margin calls, forcing managers to revalue positions intraday. The 2008 financial crisis exposed the fragility of this model. Banks holding toxic assets had to mark them down to current distressed costs, triggering a feedback loop of fire sales and insolvencies. The Basel III reforms that followed mandated stress-testing for large institutions—essentially, a requirement to model net worth under multiple asset cost scenarios.The Turning Point
The shift from static to dynamic net worth calculations gained momentum after 2010, when two forces collided: the explosion of alternative assets (private equity, crypto, art) and the democratization of financial data. Wealth managers could no longer ignore the fact that a client’s net worth based on current asset costs might differ by millions from their book value—especially if they held illiquid stakes in startups or collectibles. The problem? No standardized way to value these assets existed. Enter the "fair value" debate: Should a painting’s worth be its last sale price, an appraiser’s estimate, or a multiple of comparable transactions? The turning point came when the IRS and tax authorities began scrutinizing current asset cost discrepancies in divorce cases and estate planning. A 2017 court ruling in California forced a tech executive to split assets based on their real-time traded value, not the purchase price. The message was clear: if the market said an asset was worth X, the law would treat it as such—regardless of emotional attachment or historical cost basis. Institutional investors, sensing opportunity, began acquiring tech that could automate these valuations. Today, firms like Wealthsimple and Betterment use AI to revalue portfolios hourly, while private banks offer clients "dynamic net worth dashboards.""Net worth isn’t a snapshot; it’s a stream. The second you stop updating it for current costs, you’re lying to yourself—and to the people who depend on that number." — Larry Robbins, former Glamis Gold CEO (2012)
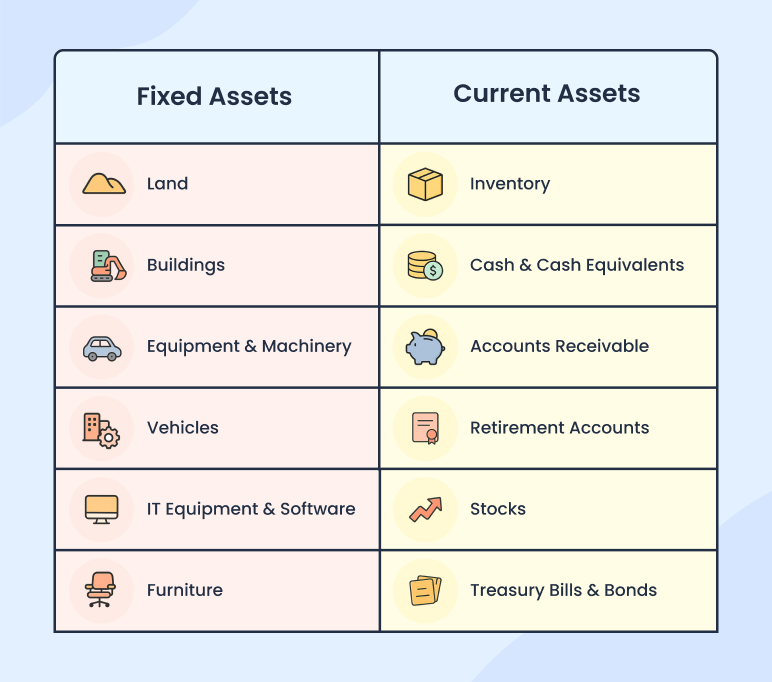
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1970s–1980s | Inflation forces SEC to mandate "fair market value" disclosures for public companies. Vanguard pioneers daily NAV calculations for index funds. |
| 1990s | Private equity firms adopt quarterly revaluations using current asset cost multiples. Dot-com boom exposes volatility risks in speculative valuations. |
| 2008–2010 | Basel III reforms require stress-testing under multiple asset cost scenarios. Hedge funds adopt intraday revaluation for leverage management. |
| 2015–2018 | IRS and courts enforce current asset cost splits in divorce/estate cases. Tech startups resist marking down valuations post-IPO crashes. |
| 2020–Present | Crypto and NFT markets force real-time net worth tracking. AI-driven wealth platforms offer dynamic revaluations; private banks launch "liquidity-adjusted" net worth metrics. |
Lessons From the Journey
- Liquidity is the silent killer. An asset’s current cost matters less than how quickly it can be sold. A blue-chip stock might be worth $100, but if the market is frozen, its effective net worth contribution drops to zero.
- Taxes and legal systems now treat net worth as a fluid metric. Ignoring current asset costs in divorce or inheritance disputes can lead to costly surprises.
- Algorithmic valuations introduce bias. A model trained on 2019–2021 data may overvalue illiquid assets in a 2023 recession—yet many UHNW clients rely on these tools.
- Psychology trumps math. People cling to purchase prices ("I bought Bitcoin at $10K!") even as markets redefine value. Behavioral finance shows that net worth based on current costs is only useful if the holder accepts volatility.
- The line between personal and institutional finance is blurring. Retail investors now have access to the same real-time tools as hedge funds—but lack the risk management frameworks to handle the data.
Where Things Stand Today
The modern net worth calculation is a hybrid of art and science. For public equities and commodities, current asset costs are straightforward: pull the latest closing price. But for private assets—the bulk of many UHNW portfolios—the process is messy. Venture capital firms still rely on "pre-money" valuations that can diverge wildly from liquidation value. Art collectors use auction house estimates, though the market for high-end pieces is thin. Even real estate, once a stable anchor, now sees Zillow’s Zestimates challenged by local market conditions. The biggest shift? Net worth is no longer a private number. Wealth managers now offer clients "net worth APIs" that sync with legal, tax, and lending systems. A divorce lawyer in London might pull a client’s current asset cost data directly from their bank’s platform. The downside? This transparency creates new risks. A single mispriced asset—like a crypto holding during an exchange hack—can trigger margin calls or insurance disputes. The system is faster than ever, but less forgiving.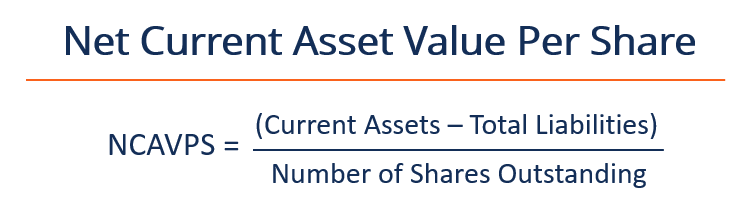
Conclusion
The move toward net worth based on current asset costs wasn’t inevitable—it was a response to three forces: technology (real-time data), regulation (tax and legal enforcement), and market structure (the rise of illiquid assets). The result is a financial ecosystem where wealth is no longer a static ledger entry but a dynamic variable, subject to the whims of algorithms, sentiment, and geopolitics. The challenge now is adaptation. For individuals, this means accepting that net worth is a range, not a point. For institutions, it demands better tools to handle the noise. And for governments, it raises questions: Should net worth volatility trigger automatic policy responses, like capital controls or tax adjustments? The answer will shape the next era of finance—one where the only constant is change.Comprehensive FAQs
Q: How often should I update my net worth based on current asset costs?
For liquid assets (public stocks, ETFs, crypto), daily updates are standard. Illiquid assets (private equity, real estate, art) should be revalued quarterly or when major market events occur. The key is balancing frequency with sanity—obsessing over intraday fluctuations can harm decision-making.
Q: Can I legally avoid using current asset costs in divorce or estate planning?
In most jurisdictions, courts will consider current market value over historical cost basis, especially for high-value assets. Some jurisdictions allow "elective share" clauses to override market valuations, but these require legal expertise. Always consult a specialist familiar with your region’s asset valuation laws.
Q: Are there tools that automatically track net worth based on current asset costs?
Yes. Platforms like Wealthfront, Personal Capital, and YNAB offer automated revaluations for liquid assets. For private assets, firms like Wealthsimple Trade (for crypto) or ArtTactic (for collectibles) provide estimates. However, no tool is perfect—always cross-check with independent appraisals for high-value items.
Q: How do taxes treat gains/losses when net worth is based on current costs?
Tax authorities typically use current fair market value for capital gains calculations, not purchase price. For example, if you sell a stock worth $50K (purchased at $30K), the gain is taxed on the $20K difference. Some countries (like the U.S.) allow "step-up in basis" for inherited assets, but this is an exception. Always consult a tax advisor before assuming a valuation.
Q: What’s the biggest mistake people make with current asset cost valuations?
Assuming current cost equals realizable value. A stock might be worth $100, but if you can’t sell it without triggering a market crash, its effective net worth contribution is lower. Similarly, overvaluing illiquid assets (e.g., a startup’s "unicorn" label) can lead to poor financial decisions when markets correct.
Q: How do hedge funds and private equity firms handle net worth volatility?
They use multi-scenario modeling. A fund might calculate net worth under three asset cost assumptions: bull market, neutral, and bear market. This helps with risk management and investor reporting. Some firms also segment assets into "core" (stable) and "volatile" (speculative) buckets to smooth out fluctuations.
Q: Will central bank digital currencies (CBDCs) change how we track net worth?
Potentially. If CBDCs include programmable features (e.g., automatic revaluation triggers), net worth tracking could become even more granular—and potentially invasive. Privacy concerns will likely lead to opt-in systems, but expect regulators to push for transparency in high-value transactions.
