Where It All Began
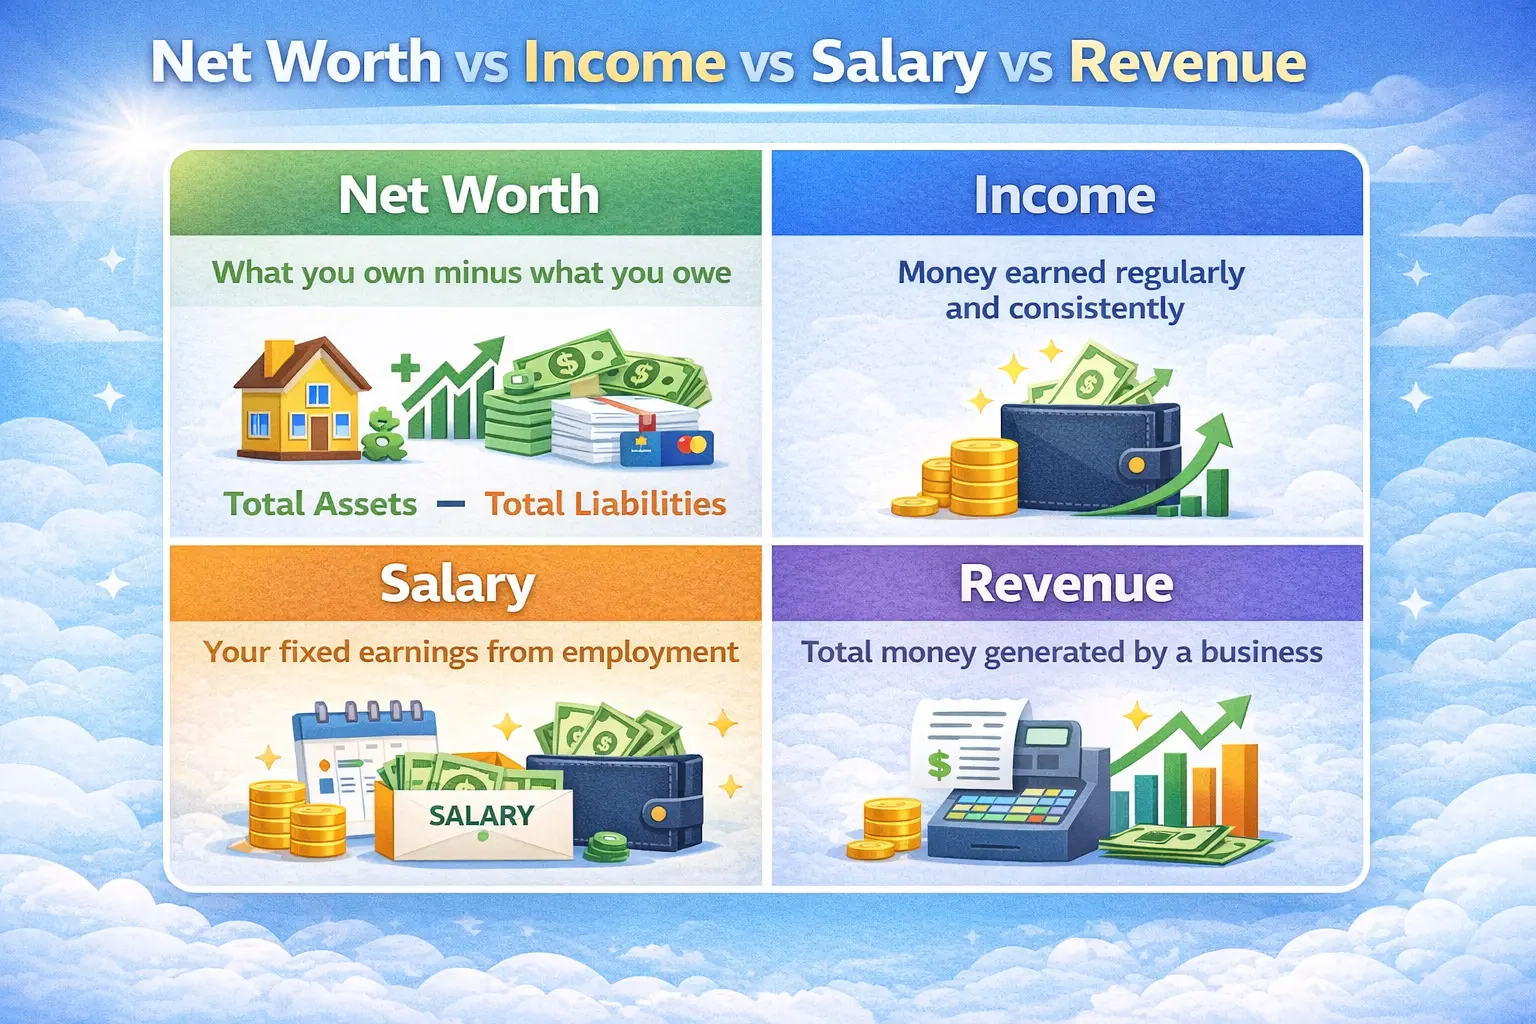
The concept of net worth predates modern capitalism by centuries. In medieval Europe, a merchant’s wealth wasn’t just gold coins—it was the value of their ships, warehouses, and trade routes, minus debts owed to guilds or creditors. The term itself emerged in 18th-century England, where accountants for the East India Company began calculating the net (or remaining) value of colonial assets after expenses. Meanwhile, net income—the cash left after deductions—was a byproduct of the Industrial Revolution. Factories needed to track profits beyond raw revenue, and so the distinction between gross and net entered the lexicon. The real inflection point came in the 1930s, when the New Deal forced Americans to confront their finances in black-and-white ledgers. The Social Security Act of 1935 tied benefits to recorded earnings, making net income a government-mandated metric. Simultaneously, the rise of consumer credit—car loans, mortgages—meant that for the first time, net worth wasn’t just about land or livestock. It was about the house you could buy, the car you could afford, and the credit score that unlocked both. The terms became intertwined with the American Dream, even as the dream itself grew more fragile.The Early Signs
By the 1970s, the signs were everywhere. The first personal finance magazines hit newsstands, teaching readers how to calculate net worth using a simple spreadsheet. Meanwhile, the rise of index funds democratized net income—suddenly, even a teacher’s modest salary could grow through passive investments. The problem? Most people treated the two metrics as separate puzzles rather than a system. A plumber might boast about his net income while ignoring how his tools and van depreciated, dragging down his net worth. The disconnect would only widen. The 1980s made it worse. Deregulation turned Wall Street into a casino, where net worth could skyrocket overnight—or collapse. For the first time, ordinary investors faced margin calls, options trading, and leveraged bets that blurred the line between income and speculative wealth. The terms became weapons. A CEO’s net income from stock options might not show up on their paycheck, while their net worth ballooned on paper. Meanwhile, a factory worker’s net income stayed flat, but their net worth plunged as home values crashed. The language of finance had become a tool for obscuring inequality.The Turning Point
The 2008 financial crisis didn’t just crash markets—it exposed the fragility of the net worth and net income relationship. Millions of homeowners saw their net worth evaporate as mortgages underwater became a national crisis. Their net income didn’t vanish, but the assets they’d relied on for security did. The aftermath forced a reckoning: net worth wasn’t just about assets; it was about resilience. A family’s net income could sustain them for years, but if their home—often their largest asset—was worth less than the mortgage, they were trapped. The shift from homeownership as a net worth builder to a liability redefined personal finance. Suddenly, net income mattered more than ever, because without assets to fall back on, cash flow became the only safety net. Side hustles, gig work, and the rise of the "hustle economy" were direct responses to this new reality. The terms net worth and net income stopped being academic—they became survival tools."In 2008, we learned that net worth isn’t just numbers on a page. It’s the difference between a family’s ability to weather a storm and their complete collapse. Net income is what keeps the lights on, but net worth is what lets you rebuild when the lights go out." — Annamaria Lusardi, academic director of the Global Financial Literacy Excellence Center

The Build-Up, Year by Year
| Period | What Happened |
|---|---|
| 1990s | The dot-com boom turned net income from jobs into speculative bets (IPOs, options). Net worth for tech workers soared, but many had no real assets—just paper gains. The crash in 2000 taught a brutal lesson: net income without asset diversification is volatile. |
| 2000–2007 | Subprime mortgages inflated net worth for millions via home equity loans. Net income stayed stagnant for most, but easy credit masked the gap. When foreclosures hit, net worth collapsed faster than net income could recover. |
| 2010–2015 | The rise of fintech (robo-advisors, peer-to-peer lending) made tracking net worth and net income easier. Side gigs (Uber, Airbnb) turned irregular net income into a net worth strategy for the gig economy. |
| 2016–2020 | Stock market rallies and remote work boosted net worth for asset owners, while net income for service workers stagnated. The pandemic exposed the gap: those with net worth in stocks or real estate weathered lockdowns; those reliant on net income from hourly work faced eviction. |
| 2021–Present | Inflation erodes net income for fixed-income earners while net worth for crypto and tech investors fluctuates wildly. The terms now describe two economies: one for the asset-rich, one for the cash-dependent. |
Lessons From the Journey
- Assets aren’t static. A net worth built on a single asset (e.g., a home) is riskier than diversified holdings. The 2008 crash proved that net income alone can’t offset a net worth wipeout.
- Net income is the fuel, but net worth is the engine. Without savings or investments, even high net income won’t generate long-term wealth.
- Leverage is a double-edged sword. A mortgage can amplify net worth, but it also turns net income into a fixed obligation. The margin between the two determines financial freedom.
- Taxes and fees eat into both. A freelancer’s net income after deductions may look modest, but their net worth growth depends on how they reinvest those earnings.
- The gig economy flips the script. For many, net income is irregular, but net worth can grow faster through asset appreciation (e.g., flipping items, rental properties). The old rules no longer apply.
Where Things Stand Today
Today, net worth and net income are more polarized than ever. On one side, institutional investors and high-net-worth individuals treat net worth as a liquidity play—shifting assets between stocks, real estate, and private equity to optimize net income streams. On the other, the gig workforce treats net income as their primary metric, using apps to track every dollar while their net worth grows incrementally through micro-investments. The pandemic accelerated this divide. Those with net worth in diversified portfolios saw their holdings rebound quickly; those reliant on net income from hourly work faced layoffs and eviction risks. The terms have become shorthand for two Americas: one where assets dictate opportunity, and another where cash flow is the only safety net. The challenge now is bridging the gap—not by simplifying the metrics, but by understanding how they interact in an economy that rewards speed over stability.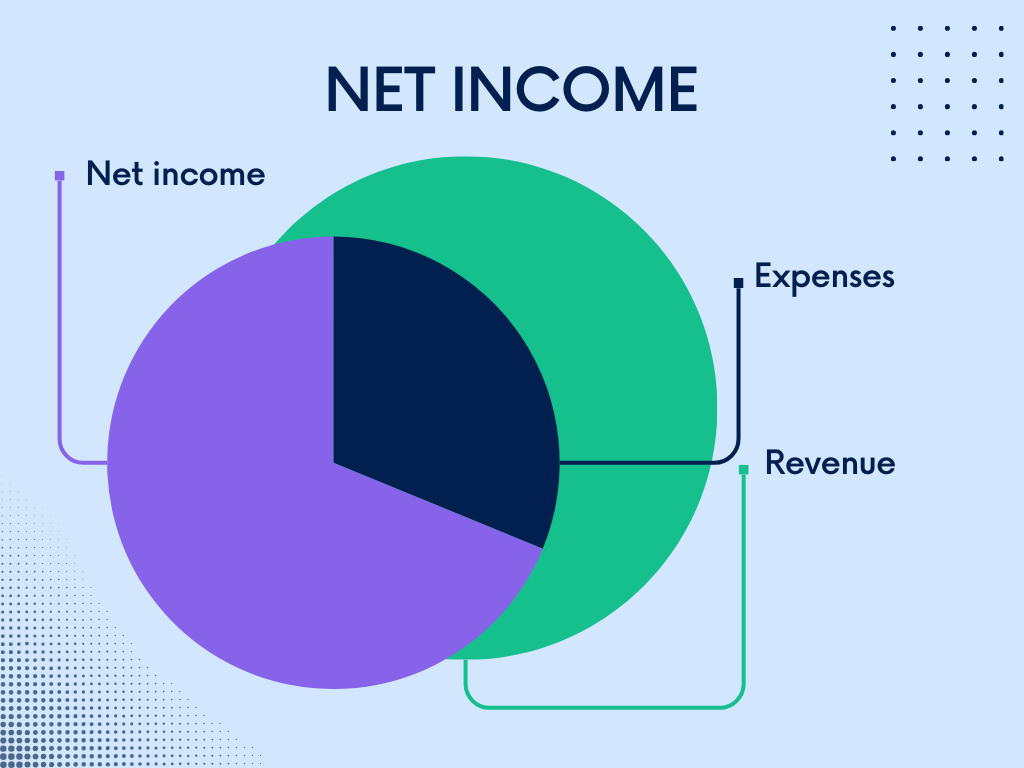
Conclusion
The story of net worth and net income is the story of modern finance itself: a tug-of-war between stability and speculation, between what you own and what you earn. The terms weren’t designed to be weapons, but they’ve become exactly that—in boardrooms, in policy debates, and in the daily lives of people trying to make ends meet. The key isn’t to master the numbers, but to recognize that they’re not just metrics. They’re reflections of power, access, and resilience. As the economy continues to evolve—with crypto, AI, and automation reshaping both net worth and net income—the fundamental question remains: how do you build a future where the two work in harmony, not against each other? The answer lies in treating them not as separate ledgers, but as two sides of the same financial coin.Comprehensive FAQs
Q: How do I calculate my net worth and net income?
Net worth is simple: subtract your liabilities (debts, mortgages, loans) from your assets (cash, investments, property, retirement accounts). Net income is your take-home pay after taxes, deductions, and self-employment expenses. For freelancers, track every dollar—apps like Mint or YNAB automate the process.
Q: Can my net income be negative?
Yes. If your expenses (rent, loans, living costs) exceed your gross income after taxes, your net income is negative. This is common for entrepreneurs in early stages or gig workers with irregular earnings. The fix? Cut costs, increase revenue streams, or tap into savings (if available).
Q: Does a high net income guarantee a high net worth?
No. Many high earners spend their net income as fast as they earn it, leaving little to build assets. Net worth depends on saving, investing, and asset appreciation—not just salary. For example, a doctor with $200K/year net income but no savings may have a lower net worth than a teacher who invests wisely.
Q: How often should I review my net worth and net income?
At least quarterly. Life changes—career shifts, market fluctuations, unexpected expenses—can drastically alter both metrics. Use tools like Personal Capital or a simple spreadsheet to monitor trends. Annual reviews won’t catch short-term risks (e.g., a stock dip or medical bill).
Q: What’s the biggest myth about net worth and net income?
The myth that net worth is only about money. Many overlook non-financial assets like skills, networks, or time flexibility. A stay-at-home parent’s net worth might not show up on a balance sheet, but their contribution to family stability is priceless. Similarly, net income isn’t just a paycheck—it’s the sum of all revenue streams, from side hustles to passive income.
Q: How do taxes affect my net worth and net income?
Taxes are the silent killer of both. Net income is after-tax earnings, but deductions (401(k) contributions, HSA, etc.) can lower taxable income, boosting long-term net worth. Meanwhile, capital gains taxes erode net worth when you sell assets. Strategies like tax-loss harvesting or Roth IRAs can mitigate the damage—consult a financial advisor to optimize.
Q: Can I improve my net worth without increasing my net income?
Absolutely. Reduce debt (refinance loans, pay down credit cards), increase asset value (home renovations, skill-building), or invest existing savings in low-cost index funds. For example, a $500/month net income increase might feel impossible, but cutting subscriptions and investing the savings could grow net worth faster than a raise.
Q: What’s the difference between gross income and net income?
Gross income is all revenue before deductions (taxes, FICA, 401(k) contributions, health insurance). Net income is what’s left after those deductions—your take-home pay. For freelancers, it’s gross revenue minus business expenses (software, travel, home office). The gap between the two determines your tax burden and disposable cash.
Q: How do student loans impact net worth and net income?
Student loans are a double whammy. They’re a liability dragging down net worth, while monthly payments reduce net income available for savings or investments. The damage depends on the loan type: federal loans offer protections (income-driven repayment), but private loans can trap borrowers in high-interest cycles. Strategies like refinancing or public service forgiveness can help, but the key is to balance loan repayment with asset-building.
Q: Is it better to focus on net worth or net income?
Both. Net income keeps you afloat; net worth secures your future. Prioritize net income in early career stages to build savings, then shift focus to net worth through investments. Ignore one at the expense of the other and you risk instability (high net income, no savings) or stagnation (low net income, but no debt).
