
Where It All Began
The origins of high net worth versus ultra high net worth can be traced to post-World War II Europe, where private banks in Geneva and Zurich began categorizing clients by asset size to streamline service tiers. A $1 million threshold (adjusted for inflation) became the unofficial benchmark for what was then called "private banking" clientele. These weren’t the industrialists of the Gilded Age—they were the new money: entrepreneurs, heirs to mid-sized fortunes, and professionals who’d cashed in on the postwar boom. Their wealth was still visible—country clubs, classic cars, butlered households—but their financial strategies were rudimentary by today’s standards. Most held portfolios concentrated in domestic markets, with little exposure to global diversification. The real inflection point came in the 1970s, when oil sheikhs, tech pioneers, and European aristocrats began consolidating wealth in ways that outpaced traditional banking systems. The term ultra-high-net-worth didn’t exist yet, but the behavior did: families like the Rothschilds and Rockefellers had long operated in the shadows, but now their descendants were joining forces with corporate raiders and sovereign wealth fund managers. The distinction wasn’t just about the size of the balance sheet but the complexity of the wealth structure. High-net-worth individuals might use Swiss accounts to avoid taxes; the ultra-rich were setting up entire legal entities in Luxembourg or the Cayman Islands to optimize across jurisdictions.The Early Signs
By the 1980s, the cracks in the old system were visible. High-net-worth clients were still content with annual reviews and basic estate planning, while the ultra-wealthy demanded bespoke solutions—private equity placements, tailored insurance products, and even bespoke currency hedging. The rise of hedge funds in the U.S. and the deregulation of global capital markets created a feedback loop: the more the ultra-rich could move money freely, the more they could exploit inefficiencies in traditional markets. Meanwhile, high-net-worth individuals were left playing catch-up, often relying on the same advisors who couldn’t serve the new breed of clients. The turning point wasn’t a single event but a series of quiet revolutions. The collapse of the Bretton Woods system in 1971 removed the gold standard’s constraints, allowing currencies to float—and with them, the ability to park wealth anywhere. Then came the 1986 Tax Reform Act in the U.S., which accelerated capital flight as high-net-worth families sought offshore havens. The ultra-rich, however, were already a step ahead, having diversified into real estate, private equity, and even sovereign bonds. The gap wasn’t just widening; it was becoming institutional.The Turning Point
The 1990s solidified the divide. While high-net-worth individuals were still measuring success in terms of liquid assets, the ultra-wealthy were redefining wealth as illiquid power. The dot-com boom and bust exposed the fragility of paper wealth, but the ultra-rich—those with stakes in infrastructure, commodities, or private companies—weathered the storm. Their portfolios weren’t just diversified; they were strategic. Meanwhile, high-net-worth families who had overconcentrated in tech stocks saw their fortunes evaporate overnight, forcing a reckoning: wealth management had become a game of access, not just numbers. The final nail in the old model’s coffin came with the 2008 financial crisis. High-net-worth individuals who had relied on leverage and liquid markets saw portfolios shrink by 30–50%. The ultra-rich, however, had already shifted into hard assets—gold, farmland, timber, and even distressed debt purchases. Their wealth didn’t just survive; it expanded as others’ losses created arbitrage opportunities. The crisis didn’t just separate the two tiers; it revealed that the ultra-high-net-worth class had evolved into a different economic species entirely."Wealth isn’t about how much you have; it’s about how you move it. The high-net-worth play by the rules. The ultra-rich rewrite them." — A former Goldman Sachs private wealth strategist, 2012
The Build-Up, Year by Year
| Period | What Changed |
|---|---|
| 1980s | Offshore banking explodes; Swiss private banks introduce tiered service levels. High-net-worth clients get basic wealth management; ultra-rich demand structured products and discretionary accounts. |
| 1990s | Hedge funds and private equity emerge as ultra-high-net-worth playthings. High-net-worth individuals still rely on mutual funds and brokerage accounts. |
| 2000s | Tax optimization becomes a science. Ultra-rich use trusts, foundations, and family offices to shield wealth; high-net-worth clients chase tax-efficient investments like REITs. |
| 2010s | Cryptocurrency and blockchain attract ultra-high-net-worth investors; high-net-worth individuals remain skeptical. Private credit and distressed assets become ultra-rich staples. |
| 2020s | ESG and impact investing split the two tiers. High-net-worth individuals adopt sustainable funds; ultra-rich create their own impact vehicles or bypass them entirely. |
Lessons From the Journey
- Liquidity ≠ Wealth. High-net-worth individuals often confuse cash with power, while the ultra-rich understand that true wealth is tied to illiquid, high-control assets.
- Taxes are a game, not a constraint. The ultra-rich don’t pay less—they structure wealth to make taxes irrelevant through trusts, residency planning, and asset location.
- Access trumps strategy. High-net-worth clients can replicate investment strategies, but the ultra-rich have first-mover advantage in private markets, sovereign deals, and emerging asset classes.
- The ultra-rich don’t just own wealth—they engineer it. From founding private equity firms to buying minority stakes in nations via sovereign wealth funds, their playbook is about influence, not just returns.
Where Things Stand Today
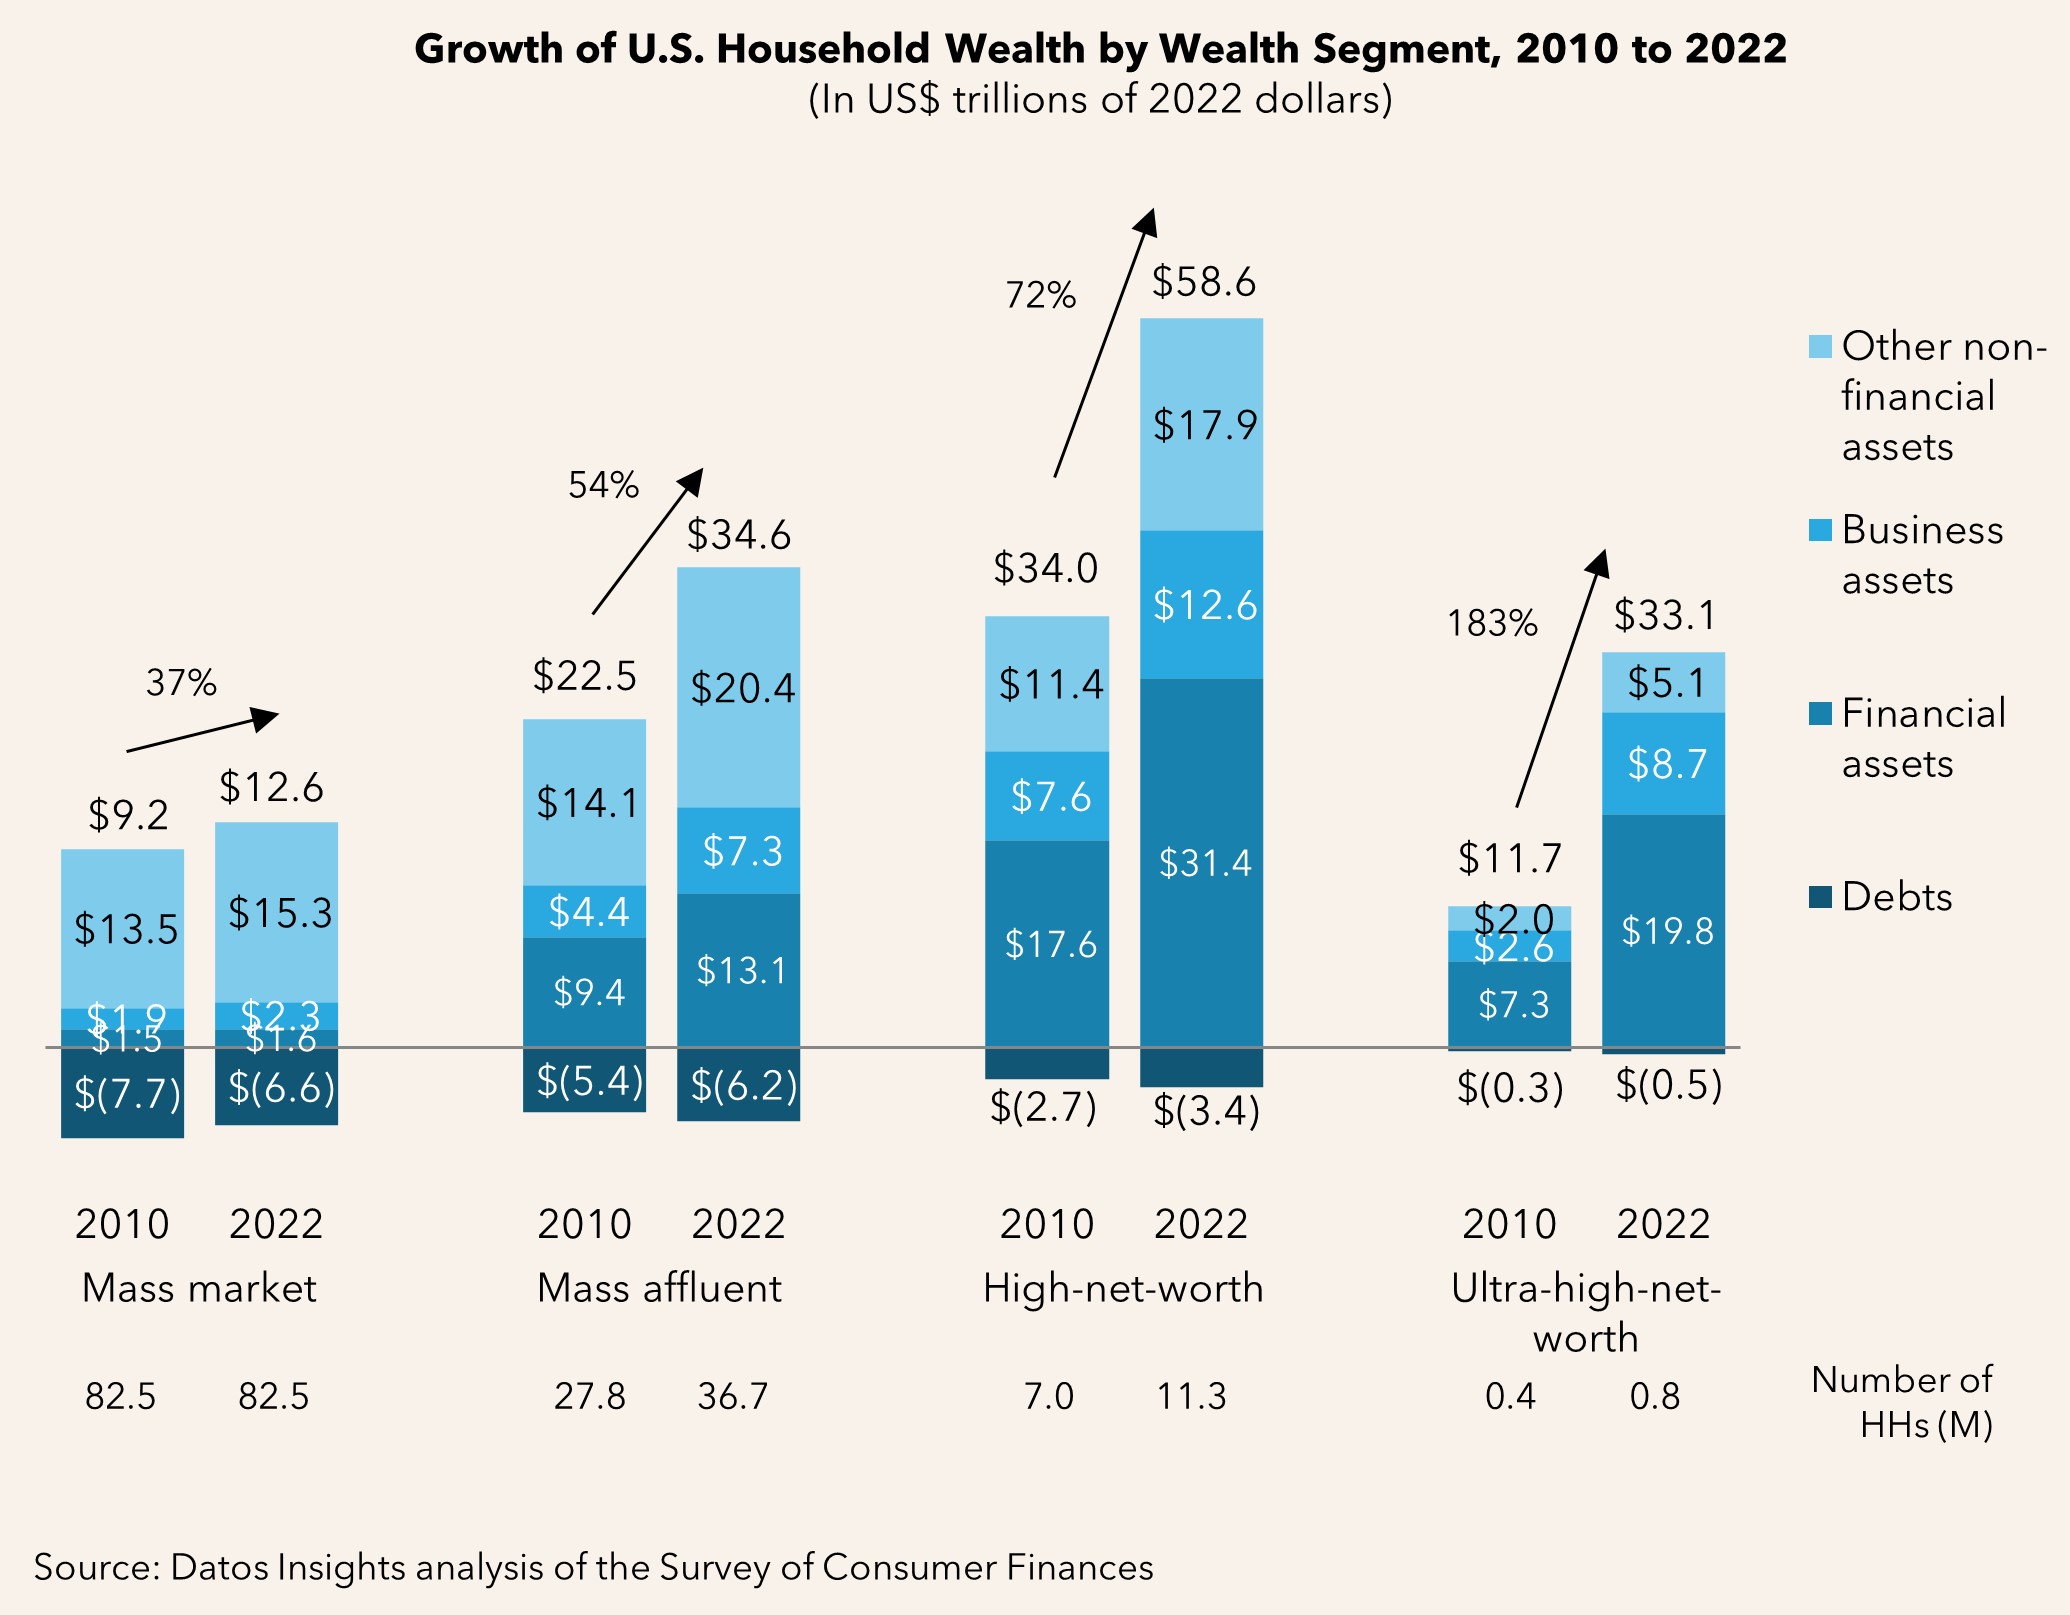
The current landscape is defined by two parallel universes. High-net-worth individuals—those with portfolios ranging from $1 million to $30 million—still operate within the rules of traditional finance. They use robo-advisors, ETFs, and family offices that mimic institutional strategies. Their challenges are familiar: succession planning, market volatility, and the pressure to keep up with peers in consumption (yachts, private schools, art auctions). The ultra-high-net-worth, however, exist in a different dimension. With net worth starting at $30 million and stretching into the billions, their focus is on legacy engineering—how to pass wealth across generations while maintaining control. What separates them today isn’t just the balance sheet but the mindset. High-net-worth individuals still aspire to join the ultra-rich club; the ultra-rich, meanwhile, are more concerned with redefining the club itself. Whether it’s through space tourism, private island purchases, or even lobbying for financial deregulation, their moves are less about personal enrichment and more about reshaping the systems that govern wealth. The result? A wealth divide that’s no longer just economic but philosophical.
Conclusion
The evolution of high net worth versus ultra high net worth isn’t just a story of money—it’s a story of power. The high-net-worth individual is a participant in the financial system; the ultra-rich are its architects. One plays by the rules; the other rewrites them. The distinction matters because it explains why some fortunes grow while others stagnate, why certain families dominate industries for centuries, and why others fade despite starting with the same capital. The next decade will likely see the ultra-high-net-worth class double down on alternative assets—from biotech to AI startups—while high-net-worth individuals grapple with the fallout of inflation and market corrections. The gap won’t close; it will only widen, as the ultra-rich continue to invent new ways to deploy capital beyond the reach of traditional metrics. For everyone else, the lesson is clear: wealth isn’t just about how much you have. It’s about how you move it.Comprehensive FAQs
Q: What’s the exact net worth threshold that separates high-net-worth from ultra-high-net-worth?
There’s no universal standard, but industry benchmarks typically place high-net-worth individuals at $1 million+ in liquid assets (adjusted for region), while ultra-high-net-worth begins around $30 million+. Private banks like UBS and Credit Suisse use $50 million as a common cutoff for their most exclusive services.
Q: Can a high-net-worth individual become ultra-high-net-worth in a short time?
Rarely. The ultra-high-net-worth class is built on generational wealth compounding, private equity stakes, or high-risk, high-reward ventures (e.g., founding a unicorn). Most high-net-worth individuals who "cross over" do so through inheritance, strategic marriages, or lucky bets in illiquid assets like real estate or venture capital.
Q: Do ultra-high-net-worth individuals pay less in taxes?
Not necessarily less, but more strategically. They use trusts, residency planning, and offshore structures to defer, avoid, or shift tax burdens across jurisdictions. A 2022 study by the Tax Justice Network found that the ultra-rich pay an effective tax rate as low as 2–5% on global income, compared to 15–30% for high-net-worth individuals in developed markets.
Q: What’s the biggest mistake high-net-worth individuals make when trying to join the ultra-rich?
Chasing liquidity. The ultra-rich focus on control—owning stakes in private companies, land, or infrastructure—while high-net-worth individuals often overconcentrate in public markets, real estate, or collectibles. The former builds power; the latter builds volatility.
Q: Are there any ultra-high-net-worth individuals who started with nothing?
Yes, but they’re exceptions. Examples include Jeff Bezos (Amazon), Mark Zuckerberg (Meta), and Elon Musk (Tesla/SpaceX), who leveraged tech monopolies to accumulate wealth beyond traditional metrics. Most ultra-rich, however, inherit or repurpose family capital into new asset classes (e.g., the Walton family’s transition from retail to real estate and private equity).
Q: How does the ultra-high-net-worth class interact with governments?
They don’t just interact—they influence. Ultra-high-net-worth individuals and families often fund think tanks, lobby for deregulation, and even purchase political access through PACs or direct investments in policy-adjacent ventures. High-net-worth individuals may donate to charities or political campaigns, but their impact is limited by scale.
Q: What’s the most valuable asset class for ultra-high-net-worth individuals today?
It varies by cycle, but private equity, sovereign deals, and alternative assets (timber, farmland, rare metals) consistently outperform. High-net-worth individuals still favor stocks, bonds, and real estate, while the ultra-rich increasingly allocate to illiquid, high-growth ventures—like space tourism companies or AI infrastructure—that offer both financial and strategic upside.
Q: Can a family office help bridge the gap between high-net-worth and ultra-high-net-worth?
Only if it’s strategic. A family office for a high-net-worth individual might manage endowments and tax planning; an ultra-high-net-worth family office operates like a private investment bank, deploying capital into bespoke opportunities. The difference isn’t just scale—it’s scope. One optimizes; the other creates.
