5 Things Worth Knowing About Upper Middle Class Net Worth
The upper middle class net worth is rarely discussed with the same granularity as other wealth brackets. Partly, this is because the group itself resists labeling—many would bristle at being pigeonholed by a number. Yet the patterns are undeniable. Below are five critical insights that explain why this demographic matters more than ever in an era of rising inequality.1. The Number Isn’t the Point—It’s the Flexibility
Figures around the $1.5 million to $5 million range are often cited as the upper middle class net worth threshold in the U.S., but the real story lies in what that sum enables. A family with a net worth of $3 million in San Francisco can live very differently than one with the same figure in Wichita. The former might own multiple properties, a yacht, and a private school tuition fund; the latter might prioritize a second home in Arizona and a hedge against inflation via farmland. The flexibility to choose—whether to take a lower-paying job for lifestyle benefits or to double down on income-generating assets—defines this bracket more than the raw total. This adaptability extends to risk tolerance. Upper middle class households can afford to take calculated gambles: angel investing in startups, buying undervalued commercial real estate, or even relocating for a career pivot. Their wealth acts as a buffer, allowing them to ride out market volatility without panic-selling. The psychological advantage is just as critical as the financial one—confidence in one’s ability to recover from setbacks is a hallmark of this group.2. Inheritance and Generational Wealth Are the Wildcards
Contrary to the myth that the upper middle class builds wealth solely through hard work, inheritance plays a disproportionate role. A 2023 Federal Reserve study found that 40% of upper middle class net worth comes from inherited assets, compared to just 20% for the broader middle class. This isn’t about trust-fund excess; it’s about compounding advantages. A parent who saves aggressively for their child’s education or invests in a rental property creates a head start that future generations can leverage. Even modest inheritances—say, $200,000—can be the difference between a lifetime of financial stress and the ability to invest in appreciating assets. The generational transfer isn’t always direct. Some families use wealth to fund their children’s entrepreneurial ventures, while others deploy it to secure low-stress careers (e.g., family law firms, medical practices). The result? A cycle where each generation enters adulthood with a stronger financial foundation than the last. This dynamic explains why the upper middle class net worth tends to grow faster than that of their peers who start from scratch.3. Real Estate and Illiquid Assets Drive the Majority of Wealth
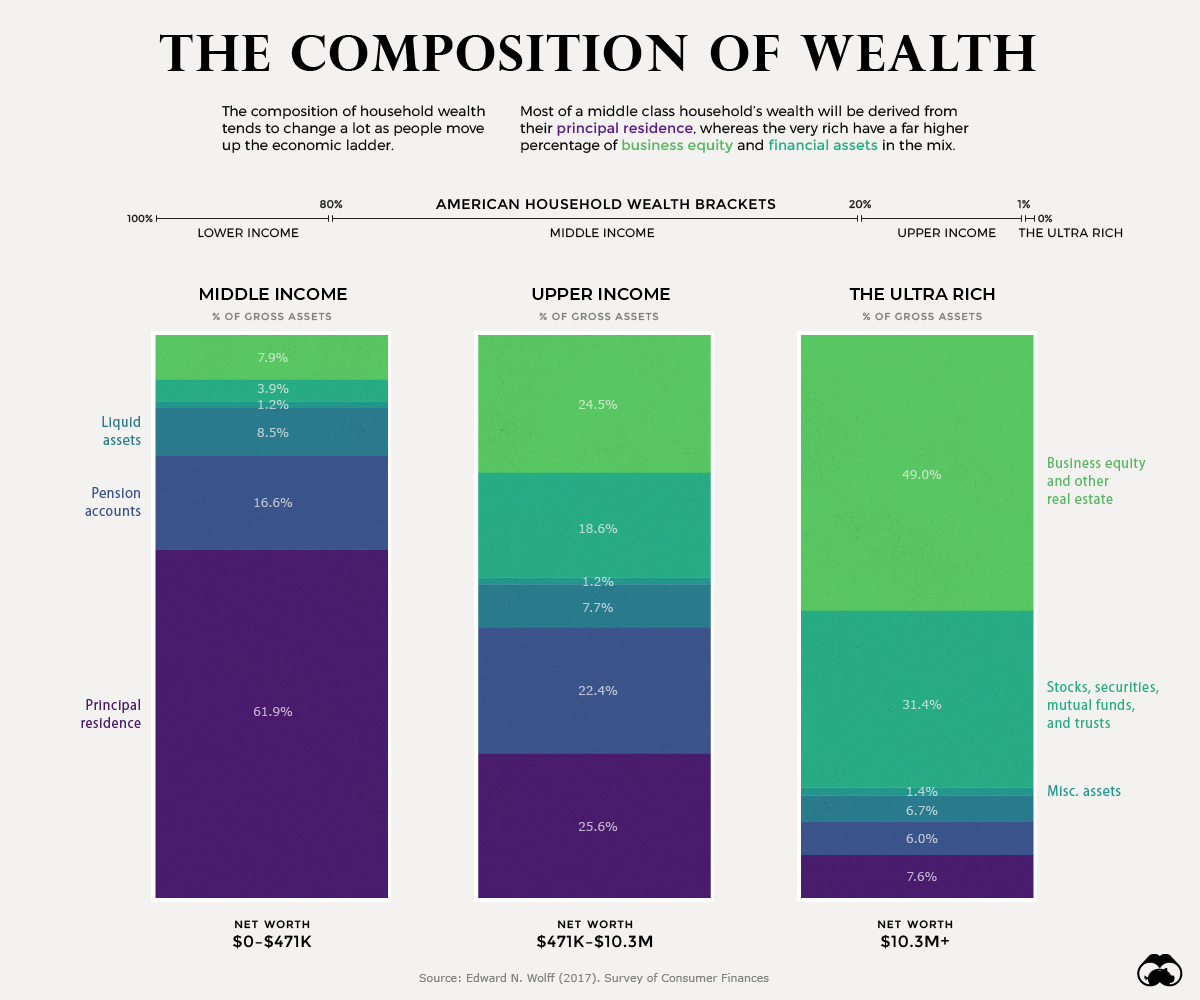
Public equity markets get the headlines, but the upper middle class net worth is far more grounded in tangible assets. A 2022 Spectrem Group report revealed that 68% of upper middle class households derive their wealth from real estate, private businesses, or collectibles—assets that don’t trade on exchanges and thus escape the volatility of the S&P 500. Primary residences, vacation homes, and rental properties are the bedrock, but niche investments like vineyards, art, or even rare wines also play a role. These assets appreciate slowly but steadily, offering tax advantages and hedges against inflation. The illiquid nature of these holdings has a downside: liquidity crises. Selling a home or business to cover unexpected expenses isn’t as simple as unloading stocks. This forces upper middle class families to plan meticulously—holding emergency funds, diversifying income streams, and often relying on lines of credit secured by property. The trade-off? Less day-to-day liquidity in exchange for long-term stability.4. Tax Optimization Is a Full-Time Strategy
Wealth at this level isn’t just about accumulation; it’s about preservation. The upper middle class net worth is eroded not by market crashes but by tax inefficiencies. Families in this bracket spend thousands annually on accountants, financial planners, and legal teams to structure trusts, maximize deductions, and exploit loopholes like the step-up in basis for inherited assets. A common strategy involves holding appreciated assets (like stocks or real estate) until death to pass them to heirs at a lower tax burden—avoiding capital gains taxes entirely. This isn’t about tax evasion; it’s about playing by the rules to retain wealth. For example, a couple in the 37% federal tax bracket might structure their portfolio to defer income, invest in municipal bonds, or use charitable remainder trusts to reduce estate taxes. The cost of these strategies—often 1–3% of net worth annually—is a small price for maintaining generational control over assets.5. Lifestyle Inflation Has a Tipping Point
There’s a delicate balance in the upper middle class net worth: the point at which lifestyle spending starts to outpace asset growth. Many families cross this threshold unknowingly, upgrading to a $2 million home only to realize they’ve tied up liquidity in a depreciating asset. Others fall into the "consultant trap"—earning high incomes but spending them on experiences (private jets, luxury travel) that don’t build wealth. The key differentiator? Discretionary spending that aligns with long-term goals. Some families cap discretionary expenses at 10–15% of net worth annually, reinvesting the rest. Others use the "10X rule": if an item costs $100,000, they ask whether they’d be willing to spend $1 million on it. The upper middle class net worth thrives when spending remains a tool—not an end.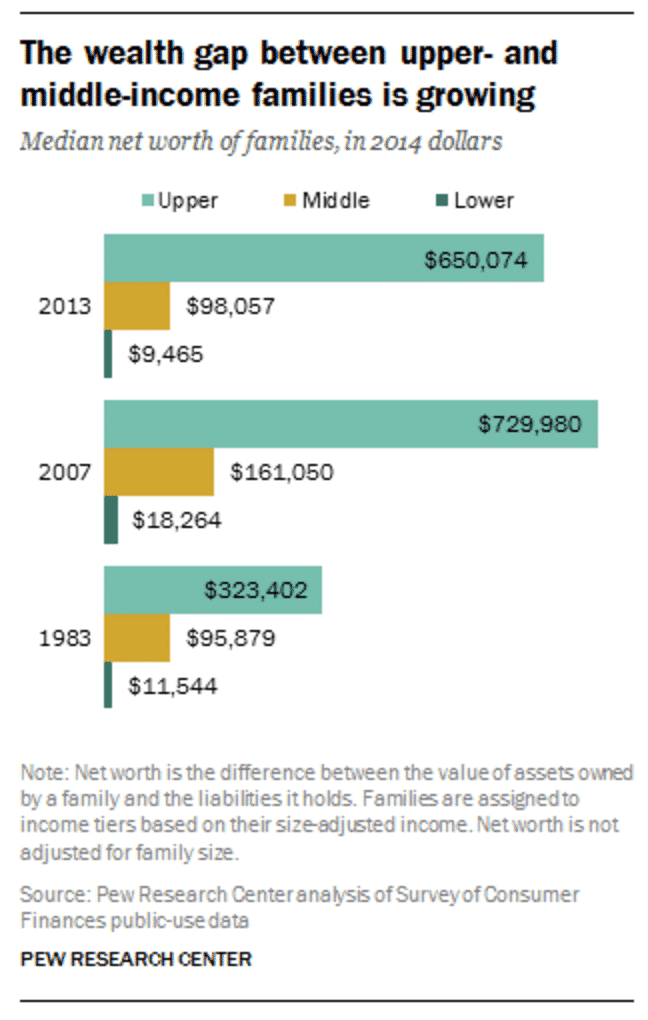
How These Facts Connect
The upper middle class net worth isn’t just a number; it’s a system. Inheritance provides the initial capital, real estate and illiquid assets ensure steady growth, and tax strategies protect it from erosion. Meanwhile, lifestyle choices—both frugal and extravagant—determine whether wealth compounds or stagnates. The most successful families in this bracket treat their net worth like a living organism: pruning underperforming assets, fertilizing high-growth opportunities, and shielding it from external shocks. What’s often overlooked is the social capital embedded in this wealth. Connections to private schools, elite networks, or niche industries create opportunities that money alone can’t buy. A child of upper middle class parents isn’t just more likely to attend an Ivy League university; they’re more likely to secure internships, mentorships, and job offers before graduation. This intangible advantage compounds over generations, reinforcing the group’s financial dominance.| Factor | Impact on Net Worth | Key Challenge | Opportunity |
|---|---|---|---|
| Inheritance | Accelerates asset accumulation by 30–50% | Family disputes over asset distribution | Structured trusts to preserve wealth |
| Real Estate | Accounts for 60–70% of total net worth | Illiquidity during market downturns | Diversification into REITs or short-term rentals |
| Tax Optimization | Reduces effective tax burden by 20–40% | Complexity of strategies | Automated compliance tools |
| Lifestyle Spending | Can erode 10–30% of annual growth if unchecked | Emotional attachment to high-cost habits | Rule-based budgeting (e.g., 10X rule) |
| Social Capital | Opens doors to high-ROI opportunities | Network decay across generations | Alumni associations, mentorship programs |

Conclusion
The upper middle class net worth is the silent engine of economic stability. It doesn’t generate headlines like the Forbes 400, but it funds the majority of America’s (and Europe’s) most influential institutions—from hospitals to universities to political campaigns. The group’s ability to navigate inheritance, real estate, and tax laws with precision ensures that wealth persists across generations, even as broader economic tides shift. Yet this stability is fragile; a single poor decision—whether a failed business venture, a divorce, or a market crash—can unravel decades of planning. The most striking takeaway? This isn’t a fixed class. The upper middle class net worth is a moving target, shaped by geography, timing, and individual choices. A software engineer in Austin might reach this threshold in their 40s, while a doctor in Boston could take twice as long. The common thread isn’t the number itself, but the mindset: a willingness to defer gratification, diversify aggressively, and view wealth as a tool for opportunity—not just security.Comprehensive FAQs
Q: How does the upper middle class net worth differ by country?
The thresholds vary significantly. In the U.S., figures around $1.5–$5 million are typical, while in the UK, £1.2–£3 million is more common. Germany and Japan see lower averages due to cultural preferences for frugality and collective savings (e.g., pension funds). Scandinavia’s upper middle class often relies more on state benefits and less on private wealth accumulation, compressing the net worth range.
Q: Can someone in the upper middle class lose their status?
Absolutely. A single event—a divorce splitting assets, a bad investment, or a career reversal—can drop a household below the threshold. The buffer isn’t infinite. Many families protect against this by maintaining "dry powder" (cash or liquid assets) equivalent to 12–24 months of expenses, even if it means forgoing luxury spending.
Q: Is the upper middle class net worth growing or shrinking?
Data suggests stagnation in real terms. While nominal net worth has risen with inflation, the gap between the upper middle class and the top 1% has widened. The 2008 financial crisis and the COVID-19 pandemic exposed vulnerabilities, particularly for those reliant on real estate or private business income. Post-pandemic, asset inflation (e.g., soaring home prices) has helped some, but wage stagnation for professional workers has offset gains.
Q: What’s the biggest misconception about this wealth bracket?
The assumption that it’s uniformly "safe." Many upper middle class families face hidden risks: overconcentration in a single asset (e.g., a family business), underinsured liabilities (e.g., malpractice lawsuits for doctors), or the "empty nest syndrome," where couples spend down savings after children leave home. The appearance of stability can mask significant blind spots.
Q: How do upper middle class families typically structure their estates?
Most use a combination of revocable living trusts (to avoid probate), irrevocable trusts (for asset protection), and charitable remainder trusts (to reduce estate taxes). Some leverage grantor retained annuity trusts (GRATs) to transfer appreciating assets to heirs tax-free. The goal isn’t just to minimize taxes but to maintain control over how wealth is distributed—often keeping assets in the family for multiple generations.
Q: Can you build an upper middle class net worth starting from scratch?
Yes, but it requires extreme discipline. The fastest paths involve high-income professions (e.g., medicine, law, tech), aggressive real estate investing, or entrepreneurship. A common strategy: save 50%+ of income in the early career years, invest heavily in index funds or rental properties, and avoid lifestyle inflation. However, the time horizon is long—most who achieve this without inheritance take 20–30 years.
Q: How does healthcare factor into upper middle class financial planning?
Healthcare is the wildcard variable. A single serious illness can decimate a portfolio. Upper middle class families often insure against this with:
- High-deductible health plans paired with HSAs (tax-advantaged savings)
- Long-term care insurance (though this is declining in popularity due to cost)
- Cash reserves of $500,000–$1 million for unexpected medical expenses
Q: Are there regional hotspots where the upper middle class net worth is higher?
Yes. In the U.S., coastal cities (San Francisco, New York, Boston) and tech hubs (Austin, Seattle) see higher concentrations due to high-paying jobs and asset appreciation. In Europe, Zurich, London’s City of London, and Munich top the lists. However, these regions also come with higher costs of living—meaning the real upper middle class net worth (after taxes and expenses) may be lower than raw figures suggest.
Q: How does divorce affect upper middle class net worth?
Divorce is one of the most destructive forces for this demographic. Assets are split, tax brackets widen (filing separately), and alimony/spousal support can decimate cash flow. A common strategy to mitigate this: prenuptial agreements that clarify ownership of assets acquired before marriage, and postnuptial agreements for second marriages. Some families also hold assets in trusts or LLCs to limit division in a split.
Q: What’s the role of philanthropy in upper middle class wealth management?
Philanthropy serves multiple purposes:
- Tax efficiency: Donor-advised funds (DAFs) and charitable trusts reduce taxable income.
- Legacy building: Many families name charities as beneficiaries in wills to ensure wealth persists.
- Networking: High-net-worth philanthropists often gain access to elite circles (e.g., university boards, policy think tanks).
