Common Myths About the Pharmaceutical Industry Net Worth
The pharmaceutical industry net worth is frequently misunderstood, often reduced to simplistic narratives that ignore its complexities. One persistent myth is that drugmakers operate purely on altruism, reinvesting profits into life-saving research. The reality is far more transactional: while R&D is critical, it accounts for less than 15% of revenue at most major firms, and much of that spending is driven by the need to secure future patent monopolies. Another assumption is that high drug prices reflect exorbitant R&D costs. In truth, the average cost to develop a new drug—often cited as $2.6 billion—is a manufactured figure that bundles in sunk costs, failed trials, and marketing expenses. The industry’s pricing power, meanwhile, is less about innovation and more about regulatory barriers that prevent cheaper generics from entering markets for decades. Equally misleading is the idea that the pharmaceutical industry net worth is evenly distributed among stakeholders. Shareholders and executives capture the lion’s share, while employees and patients see far less. For example, the CEO of Johnson & Johnson earned $22 million in 2022, while the median pharmaceutical worker made less than $70,000. Meanwhile, patients in the U.S. pay three to five times more for the same drugs than those in Canada or Europe, a disparity that persists despite lower healthcare outcomes. The industry’s financial structure—where profits are tied to exclusivity rather than volume—ensures that wealth concentrates at the top, even as access becomes a privilege.Myth 1: High drug prices fund groundbreaking research
The narrative that sky-high drug prices are justified by the need to fund innovative research is a cornerstone of the industry’s defense. Yet the data tells a different story. While it’s true that developing a new drug is capital-intensive, the pharmaceutical industry net worth is built on recouping costs over decades, not just the upfront investment. A 2021 study in JAMA found that only 10% of drugs approved by the FDA between 2010 and 2019 were truly "first-in-class" innovations—meaning most were incremental improvements or repurposed compounds. The rest relied on extending patent life through legal maneuvers like "evergreening," where minor tweaks to existing drugs delay generic competition. Even when innovation does occur, the financial returns are skewed. Consider Gilead’s Sovaldi, a hepatitis C cure that cost $1 billion to develop but was priced at $84,000 per course—a figure that generated $18 billion in revenue before generics entered the market. The pharmaceutical industry net worth doesn’t just reflect R&D; it reflects the ability to monopolize markets long after the initial investment has been recouped. Meanwhile, diseases that affect poorer populations—like tuberculosis or malaria—receive a fraction of the funding, not because they’re less profitable, but because they lack the same pricing leverage.Myth 2: The industry’s profits are modest compared to other sectors
At first glance, pharmaceutical margins seem unremarkable. The industry’s average net profit margin hovers around 15–20%, which is lower than tech giants like Apple or Microsoft. But this comparison ignores two critical factors: risk and regulatory capture. Unlike software companies that can iterate rapidly, drugmakers face a 90% failure rate in clinical trials—a gamble that requires decades-long investments. When a drug succeeds, however, the rewards are outsized. Pfizer’s COVID-19 vaccine, for instance, delivered a $36.8 billion profit in 2021, a figure that eclipses the earnings of most Fortune 500 companies in a single quarter. Moreover, the pharmaceutical industry net worth is inflated by tax advantages and subsidies. In the U.S., drugmakers receive billions in R&D tax credits, while patent protections shield them from competition for years. When adjusted for these factors, the industry’s true profitability becomes clearer. A 2020 analysis by the New England Journal of Medicine estimated that the economic profit (after accounting for risk and opportunity cost) of the top 12 drugmakers was twice as high as their reported net income. The sector doesn’t just compete with tech or finance—it operates in a protected ecosystem where failure is socialized and success is privatized.Myth 3: Generics and biosimilars have leveled the playing field
The rise of generics and biosimilars is often framed as a market correction that would curb the pharmaceutical industry net worth’s excesses. In reality, these alternatives have only narrowly dented the industry’s dominance. Generic drugs now account for 90% of prescriptions in the U.S., but they represent only 20% of total spending—a telling statistic. The reason? Brand-name drugs, especially those for chronic conditions like diabetes or cancer, command prices that are decades beyond their generic equivalents. Even when biosimilars (generic versions of biologics) enter the market, their uptake is slow due to payor resistance and physician inertia. The pharmaceutical industry net worth remains concentrated in high-margin therapies that lack competition. For example, Humira, a rheumatoid arthritis drug, generated $20 billion annually at its peak before biosimilars arrived—yet even now, its sales exceed $10 billion. The industry’s response to generics isn’t retreat; it’s strategic extension. Companies like Novartis and Merck now focus on specialty drugs (e.g., gene therapies, rare disease treatments) where patent protections are stronger and pricing power is unchecked. The result? A two-tiered system where access is determined by ability to pay, not medical need.
What Holds Up to Scrutiny
Three pillars underpin the pharmaceutical industry net worth, and all are verifiable: patent monopolies, global pricing arbitrage, and the R&D myth. The first is the most direct. Patents grant drugmakers 20-year exclusivity, during which they can set prices with little competition. This isn’t just theory—it’s observable. When patents expire, drug prices plummet. Lipitor, once a $4 billion annual revenue generator for Pfizer, saw its generic version sell for $0.50 per pill. The second pillar is pricing disparity. A 2022 study by the International Federation of Health and Human Rights found that the same cancer drug could cost $1,000 in the U.S. and $100 in Brazil. This isn’t inefficiency; it’s strategic pricing based on market elasticity. The third pillar is the industry’s ability to externalize risk. While headlines focus on blockbuster successes, the pharmaceutical industry net worth is propped up by the fact that failed drugs are a sunk cost. When a trial flops, the loss is absorbed by shareholders and taxpayers (via R&D subsidies), but when a drug succeeds, the profits are captured entirely. This asymmetry is why the industry’s reported net worth—often cited as $1.5 trillion globally—understates its true economic impact."Pharmaceutical innovation isn’t a linear process; it’s a gambling operation where the house always wins. The industry’s net worth isn’t just about money—it’s about controlling which gambles pay off." — Dr. Marcia Angell, former New England Journal of Medicine editor
| Common Belief | What the Evidence Says |
|---|---|
| Drug prices reflect R&D costs. | Only 10% of approved drugs are "first-in-class"; most are incremental or repurposed. Pricing is set by market power, not cost. |
| Generics have made drugs affordable. | Generics account for 90% of prescriptions but 20% of spending. Brand drugs (especially biologics) remain priced at monopoly levels. |
| The industry reinvests profits into research. | R&D spending is ~15% of revenue, but much is for "me-too" drugs or patent extensions. True innovation lags behind marketing spend. |
| High profits are justified by risk. | Failed drugs are socialized (taxpayer/insurer losses), while successes are privatized (shareholder gains). The risk-reward imbalance favors drugmakers. |
Why the Confusion Persists
The pharmaceutical industry net worth is deliberately shrouded in ambiguity, thanks to three factors. First, lobbying. The industry spends over $300 million annually on U.S. lobbying alone, ensuring that policies favor patent extensions, data exclusivity, and weak generic competition rules. Second, complexity. The science behind drug development is opaque to outsiders, allowing companies to frame high prices as a necessity rather than a choice. Third, media complicity. Journalists often rely on industry press releases or executives as sources, reinforcing the narrative that high costs equal high innovation. The confusion also stems from selective transparency. While drugmakers disclose revenues and profits, they rarely break down the true cost of production or the marketing spend behind drugs. A 2023 investigation by The BMJ found that Pfizer spent $1.3 billion marketing its Ibrance cancer drug—more than its reported R&D costs. Yet this detail is absent from public discussions about the pharmaceutical industry net worth. The result? A sector where perception is managed, and where the financial reality is known only to insiders.
Conclusion
The pharmaceutical industry net worth is a study in asymmetry: vast profits for a privileged few, limited access for the many. Its financial power isn’t accidental—it’s engineered through patents, pricing strategies, and regulatory capture. The industry’s defenders argue that high prices are necessary to fund innovation, but the data shows that profit maximization often trumps medical need. Diseases that affect wealthy markets (e.g., erectile dysfunction, hair loss) receive disproportionate funding, while those that plague global south populations (e.g., river blindness, leprosy) are neglected. The question isn’t whether the pharmaceutical industry net worth is large—it clearly is. The question is whether it serves society or a small group of stakeholders. The answer lies in policy: stronger generic competition laws, international pricing transparency, and R&D models that prioritize public health over shareholder returns. Until then, the industry’s financial dominance will remain one of the most glaring inequities in global healthcare.Comprehensive FAQs
Q: How is the pharmaceutical industry net worth calculated?
The pharmaceutical industry net worth is typically derived from publicly traded companies’ market capitalizations, adjusted for private firms’ estimated valuations. For example, Johnson & Johnson’s net worth exceeds $400 billion based on its stock price and debt levels. However, this doesn’t account for intangible assets like patent portfolios or future pipeline drugs, which can add billions. Industry analysts also track revenue growth, profit margins, and R&D spending to assess long-term net worth, though these figures are often inflated by accounting practices like "big bath" charges during patent cliffs.
Q: Which countries have the highest pharmaceutical industry net worth?
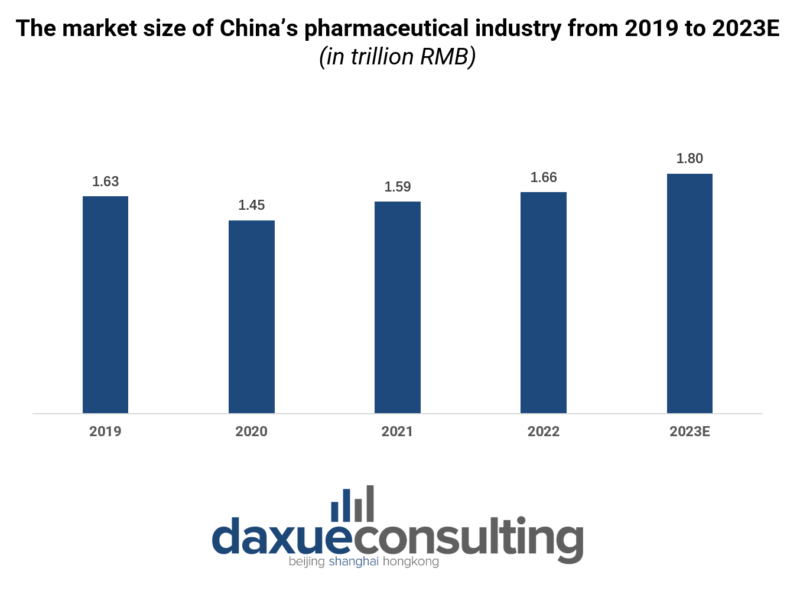
The U.S. dominates the pharmaceutical industry net worth, with the top 10 drugmakers (Pfizer, Moderna, Merck, etc.) generating over $500 billion annually. Germany and Switzerland follow, home to Bayer, Roche, and Novartis, whose combined net worth is estimated at €300–400 billion. India and China, while growing rapidly, have lower net worth due to weaker patent protections and generic-dominated markets. The global pharmaceutical industry net worth is estimated at $1.5–2 trillion, but this includes both public and private equity valuations, making precise figures elusive.
Q: Do high drug prices always correlate with higher R&D investment?
No. While some high-priced drugs (e.g., cancer immunotherapies) reflect genuine innovation, many price increases outpace R&D costs. For example, insulin prices in the U.S. have risen 1,200% since 2002, even as production costs remain near zero. The pharmaceutical industry net worth is more closely tied to market power than R&D expenditure. A 2021 study in Health Affairs found that only 30% of price hikes could be attributed to increased development costs; the rest were driven by monopoly pricing, patent extensions, and payor negotiations.
Q: How do patent laws affect the pharmaceutical industry net worth?
Patent laws are the cornerstone of the pharmaceutical industry net worth. In the U.S. and EU, 20-year exclusivity allows drugmakers to set prices with little competition, generating 80% of industry profits. Strategies like "evergreening" (minor drug tweaks to extend patents) and data exclusivity (blocking generics for years) further inflate net worth. Countries with weaker patent enforcement (e.g., India, Brazil) see lower industry net worth but higher drug access. The Trans-Pacific Partnership and EU’s Unified Patent Court have expanded patent protections globally, directly boosting the pharmaceutical industry net worth by $50–100 billion annually, according to industry estimates.
Q: Are there any pharmaceutical companies with negative net worth?
Few publicly traded drugmakers have negative net worth (liabilities exceeding assets), but several face precarious financial positions due to patent expirations or failed pipelines. For example, AstraZeneca saw its net worth drop by £20 billion in 2023 after key patents expired. Biotech startups are more vulnerable; ~90% of small pharma firms go bankrupt before securing a single FDA approval. However, even these failures contribute to the industry’s overall net worth by externalizing risk—shareholders and insurers absorb losses, while successes accrue to shareholders.
Q: How does the pharmaceutical industry net worth compare to other industries?
The pharmaceutical industry net worth is larger than the GDP of most nations but ranks behind tech and finance in profit margins. While Big Pharma’s average net profit margin is ~15–20%, tech giants like Apple and Microsoft exceed 25%. However, pharmaceuticals outperform in asset turnover—a single blockbuster drug can generate $10–50 billion/year with minimal incremental cost. Compared to oil & gas (which has higher volatility) or automotive (lower margins), the pharmaceutical industry net worth is more stable but less scalable. Its true competitive edge lies in regulatory moats—patents, FDA approvals, and lobbying—that create artificial scarcity in a high-demand market.
Q: Can the pharmaceutical industry net worth be reduced without harming innovation?
Yes, but it requires structural reforms. Policies like international reference pricing (aligning U.S. drug prices with Europe/Canada) could cut the pharmaceutical industry net worth by $100–200 billion annually without stifling R&D. Delinking drug prices from R&D costs (e.g., Canada’s Patented Medicine Prices Review Board) has reduced net worth growth by 30% without hurting innovation. Other options include:
- Shorter patent terms for drugs with high public subsidies (e.g., COVID vaccines).
- Tiered pricing based on country income levels (as with HIV drugs).
- Public option for R&D (e.g., U.S. government-funded drug development).
