
The Complete Overview of Percentile Rank of Net Worth
The percentile rank of net worth operates as a financial GPS, plotting your position against a reference group—whether your nation, your profession, or a global cohort. Unlike gross income, which measures annual flow, net worth captures the cumulative effect of decades: assets minus liabilities, from a first home to a deferred retirement account. But the rankings aren’t neutral. A 90th-percentile net worth in Sweden implies a different lifestyle than the same percentile in Nigeria, where currency volatility and property rights distort the comparison. The rankings also age poorly. A 30-year-old in the 75th percentile might be on track for the 99th by retirement—or derailed by a single market crash. The real power of percentile rankings lies in their ability to normalize wealth into digestible tiers, turning complex data into a language of inclusion or exclusion. Financial advisors use them to set client expectations; policymakers cite them to justify tax reforms. Yet the rankings are only as accurate as the data behind them. Surveys like the Federal Reserve’s Survey of Consumer Finances or the Credit Suisse Global Wealth Report rely on self-reported figures, which skew toward the affluent (the poor are less likely to respond). Even then, the thresholds shift. What constituted the "top 1%" in 2000 might now be the "top 0.1%" after two decades of asset inflation.Historical Background and Evolution
The concept of percentile rankings in wealth distribution emerged alongside modern economics, but its refinement as a tool for public discourse came in the late 20th century. Thomas Piketty’s Capital in the Twenty-First Century (2013) didn’t invent the percentile rank of net worth, but it weaponized the metric, exposing how wealth concentration had reversed course after decades of post-war decline. Before then, discussions of inequality focused on income—not the compounding power of inherited assets. The shift was critical: a $1 million net worth in 1980 might buy a mansion and a yacht; today, it’s a modest down payment in Manhattan. Governments began tracking percentile distributions in earnest during the 1990s, as tax policy debates grew more contentious. The U.S. Internal Revenue Service’s Statistics of Income division started publishing wealth percentiles by household, revealing that the top 0.1% had seen their share of national wealth grow from 7% in 1980 to over 20% by 2020. Meanwhile, central banks like the Bank of England adopted percentile benchmarks to assess financial stability risks. The rankings became a proxy for systemic health: if the 90th percentile’s net worth stagnated while the 99th surged, economists flagged it as a warning sign for asset bubbles.Core Mechanisms: How It Works
Percentile rankings are calculated by ordering all observed net worth values from lowest to highest, then dividing the population into 100 equal parts. If you’re in the 60th percentile, 60% of households have less net worth than you—and 40% have more. The challenge lies in defining the "population." A global percentile rank of net worth might include everyone from a farmer in Kenya to a tech CEO in Silicon Valley, but the median net worth in the U.S. ($120,000 in 2022) dwarfs that of India ($3,200). Context matters. A household in the 95th percentile in rural India could own a plot of land worth $50,000—enough to secure generational stability—while the same percentile in New York might mean a $5 million penthouse. The rankings also depend on the data’s granularity. Broad surveys mask disparities within subgroups. For example, Black households in the U.S. have a median net worth of $24,100, compared to $188,200 for white households—a gap that persists even after controlling for income. This isn’t just a percentile difference; it’s a structural divide. Financial planners often adjust benchmarks by demographics. A 35-year-old in the 50th percentile might be on track, but a 55-year-old in the same percentile could face retirement shortfalls. The rankings are static snapshots, but wealth is a dynamic process—one where timing, luck, and access to credit play outsized roles.Key Benefits and Crucial Impact
Understanding your percentile rank of net worth isn’t just about vanity—it’s a diagnostic tool for financial resilience. For individuals, it clarifies whether you’re ahead of or behind peers in similar life stages. A 40-year-old in the 70th percentile with $500,000 in assets might feel secure, but if their debt-to-asset ratio is 80%, the ranking hides fragility. For institutions, percentile data exposes blind spots. When the Federal Reserve found that the bottom 50% of U.S. households held just 2.6% of total wealth in 2022, it wasn’t just a statistic—it was a call to action for policy reforms like child trust funds or student debt relief. The rankings also reshape behavior. High-net-worth individuals in the 99th percentile often cluster in tax-advantaged investments or offshore accounts, while those in the 50th–75th percentile may over-index on real estate as a hedge. Psychologically, the percentile rank of net worth can be a double-edged sword. For some, it’s motivation; for others, it’s paralysis. Studies show that people in the 80th–90th percentiles are more likely to take financial risks, while those just below the median may avoid investments entirely, fearing they’ll fall further behind."Wealth isn’t just about money—it’s about the options money buys. The percentile rank of net worth is the first step in understanding which doors are open to you." — Edward N. Wolff, Professor of Economics at NYU
Major Advantages
- Benchmarking progress: Tracks whether your wealth is growing faster or slower than peers, adjusting for inflation and life stage.
- Policy leverage: Governments use percentile distributions to design targeted interventions (e.g., wealth taxes on the top 0.1%).
- Risk assessment: Lenders and insurers adjust underwriting based on percentile tiers, not just absolute numbers.
- Generational planning: Helps families estimate inheritance potential or gaps (e.g., a 30th-percentile household may need trusts to bridge the wealth divide).
- Global mobility insights: Reveals how portable your wealth is—e.g., a 95th-percentile net worth in Singapore may not translate to the same lifestyle in Argentina.
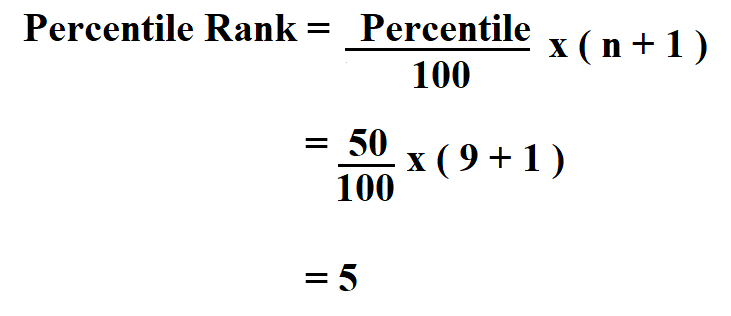
Comparative Analysis
| Metric | U.S. (2023 Estimates) | Germany (2023 Estimates) |
|---|---|---|
| Median Net Worth (50th Percentile) | $120,000 | €110,000 (~$120,000) |
| 90th Percentile Threshold | $1.3 million | €1.1 million (~$1.2 million) |
| Top 1% Net Worth Floor | $11.5 million | €9 million (~$9.7 million) |
| Wealth Gini Coefficient (0 = equal, 1 = unequal) | 0.89 (high inequality) | 0.75 (moderate inequality) |
| Key Driver of Percentile Shifts | Homeownership, stock market exposure | Pension funds, real estate inheritance |
Future Trends and Innovations
The next decade will test whether percentile rankings remain static or evolve with technological disruption. As cryptocurrency and decentralized finance (DeFi) grow, traditional net worth metrics may struggle to capture volatile assets. A household with $500,000 in Bitcoin might rank in the 99th percentile today—but if the market corrects by 50%, their percentile could plummet overnight. Regulators are already debating whether to include crypto in wealth surveys, which could reshape percentile benchmarks. Another shift is the rise of liquidity-adjusted percentiles, which account for how easily assets can be converted to cash. A vineyard in Bordeaux might rank highly in net worth, but if it’s illiquid, its percentile value during a crisis drops sharply. Meanwhile, artificial intelligence is poised to personalize percentile rankings. Algorithms could soon adjust for factors like healthcare costs, childcare expenses, or even environmental risks (e.g., flood-prone property). The question isn’t whether the rankings will change—it’s who controls the new thresholds.
Conclusion
The percentile rank of net worth is more than a number—it’s a reflection of the rules that govern wealth accumulation. Whether you’re optimizing for retirement, advocating for policy change, or simply curious about your place in the economy, the rankings offer a lens. But they’re not destiny. A 60th-percentile net worth today doesn’t preordain a 70th-percentile tomorrow. The gap between percentiles is where strategy, luck, and systemic barriers collide. The challenge ahead is to move beyond passive acceptance of these rankings. If the data shows that the top 10% hold 70% of wealth, the onus isn’t just on individuals to "work harder"—it’s on societies to redefine what a fair percentile distribution looks like. The numbers will keep changing. The question is whether we’ll let them define us—or use them to rewrite the rules.Comprehensive FAQs
Q: How often are percentile rankings updated?
Major surveys like the Federal Reserve’s Survey of Consumer Finances are conducted every three years, while global reports (e.g., Credit Suisse) update annually. However, real-time percentile tools—such as those from wealth managers—may refresh quarterly based on market data. The lag means rankings can feel outdated, especially during economic shocks like the 2008 crisis or COVID-19 recovery.
Q: Can my percentile rank change drastically in a short time?
Yes. A single event—a stock market rally, a divorce settlement, or inheriting $500,000—can shift you across percentiles overnight. For example, someone in the 50th percentile might jump to the 90th after a windfall, only to fall back if they liquidate assets during a downturn. Percentile volatility is highest for households near threshold crossings (e.g., 75th to 80th percentile).
Q: Are percentile rankings the same across countries?
No. The 90th percentile in Sweden (~€1.5 million) translates to a far higher standard of living than the same percentile in Brazil (~$300,000), due to cost-of-living differences, tax structures, and asset valuations. Even within the U.S., a 95th-percentile net worth in Texas ($2.5 million) buys less purchasing power than in Wyoming ($1.8 million), where land and housing are cheaper.
Q: Do percentile rankings account for debt?
Yes, but indirectly. Net worth is calculated as assets minus liabilities, so debt reduces your percentile placement. For example, a couple with $1 million in assets but $800,000 in mortgage debt might rank in the 60th percentile, while a debt-free peer with $600,000 in assets could be in the 70th. High-debt households often see their percentiles drop more sharply during recessions, as asset values fall while liabilities remain fixed.
Q: How do I find my own percentile rank?
Public datasets (e.g., Federal Reserve’s Distribution of Household Wealth) allow rough estimates by inputting your net worth and location. For precision, financial advisors or tools like Wealthfront or Personal Capital can generate customized percentiles based on your demographics. However, self-reported data may overstate net worth (e.g., excluding illiquid assets like art or private business equity).
Q: What’s the most misleading percentile benchmark?
The global median net worth, often cited as ~$10,000 by Credit Suisse, is misleading because it includes billions of people with near-zero wealth, skewing the distribution. A better benchmark is the median of the top 50% of households, which better reflects the "middle class" experience. Additionally, rankings that ignore generational wealth (e.g., inherited property) overstate the achievements of first-generation earners.
Q: Can governments manipulate percentile rankings?
Indirectly, yes. Policies like capital gains tax cuts, student debt forgiveness, or inheritance tax reforms can shift percentile distributions without changing underlying wealth. For example, the U.S. Tax Cuts and Jobs Act of 2017 increased the 99th-percentile threshold by lowering tax burdens on high-net-worth individuals, effectively inflating their percentile rankings. Conversely, wealth taxes (as proposed in some European nations) could suppress top-percentile growth.
Q: Are there percentile rankings for specific groups (e.g., women, minorities)?h3>
Yes, but they require granular data. Studies like the Federal Reserve’s Survey of Consumer Finances break down percentiles by race, gender, and age. For instance, Black women in the U.S. have a median net worth of ~$5,000—placing them in the 10th percentile or lower—while white men’s median (~$188,200) lands them in the 50th–60th percentile. These gaps highlight how percentile rankings expose systemic inequities beyond individual effort.
