
The Complete Overview of How Much Net Worth Is Upper Middle Class
The upper middle class isn’t a monolith; it’s a tier defined by access rather than absolute wealth. In the U.S., the Pew Research Center categorizes households earning between $130,000 and $208,000 annually (pre-tax) as upper middle class, but net worth tells a different story. A young professional in Austin with $600,000 in assets—including a mortgage-free home and a modest investment portfolio—might live like an upper middle-class resident of Chicago, where the same net worth would feel modest. The disconnect arises because net worth is static, while income is dynamic. A surgeon in Boston with $1.8 million in assets may have a net worth that aligns with upper middle class benchmarks, but her annual earnings could push her into the lower echelons of the affluent. Globally, the thresholds shift dramatically. In Germany, a net worth of €1 million to €5 million often marks the upper middle class, thanks to stronger social safety nets and lower healthcare costs. Meanwhile, in Hong Kong or Singapore, the same bracket might require HK$10 million to HK$30 million due to skyrocketing real estate prices. The key variable isn’t just currency but the liquidity premium—how easily assets can be converted into cash without sacrificing lifestyle. A family in Toronto with $1.5 million in home equity may feel secure, while one in Vancouver with the same figure might still stress over market downturns. The upper middle class, in essence, is where financial security meets the anxiety of not being quite rich enough.Historical Background and Evolution
The concept of the upper middle class as a distinct economic stratum emerged in the early 20th century, as industrialization and white-collar professions expanded. Before then, wealth was binary: aristocracy or working class. The rise of managers, lawyers, and engineers created a new tier—one that could afford private schools but couldn’t buy yachts. By the 1950s, post-WWII prosperity in the U.S. and Europe solidified this group’s identity, with net worth benchmarks tied to homeownership and college funds. The $100,000 net worth threshold of the 1960s would equate to roughly $1 million today, adjusted for inflation, yet the lifestyle expectations have lagged behind. The 1980s and 1990s saw the upper middle class fragment further. The tax policies of Reagan and Thatcher widened the gap between this group and the wealthy elite, while the dot-com boom and housing bubble of the 2000s inflated net worth figures temporarily. After the 2008 financial crisis, the definition became more conservative: households with $500,000 to $2 million were recalibrated as upper middle class, reflecting a world where pensions were unreliable and student debt was rising. Today, the debate over how much net worth is upper middle class is less about static numbers and more about resilience—can this group weather a 20% market correction without selling their home?Core Mechanisms: How It Works
Net worth in the upper middle class isn’t just about savings accounts; it’s a portfolio of protected assets. The average upper middle-class household in the U.S. allocates roughly 60% of their net worth to their primary residence, 20% to retirement accounts (401(k)s, IRAs), and the remaining 20% to liquid investments, side businesses, or collectibles. The critical mechanism is debt leverage: a mortgage isn’t a liability but a tool to amplify wealth over time. A couple in Seattle with $1.2 million in net worth—$900,000 of it tied to their home—might feel secure because they’ve paid off the mortgage, while a similar household in Miami with the same net worth but a $500,000 mortgage would feel the pressure. The upper middle class also operates under implicit rules of engagement. They won’t splurge on a $200,000 car or a $10,000 vacation, but they’ll invest in experiences that signal belonging—private school tuition, country club memberships, or a second home in a lower-cost region. Their wealth is strategically illiquid: they’d rather hold a rental property than cash out, even if it means less flexibility. This mindset explains why the upper middle class often resists the "FIRE movement" (Financial Independence, Retire Early)—they’re not chasing freedom; they’re chasing relative security within their peer group.Key Benefits and Crucial Impact
The upper middle class occupies a unique position in the wealth hierarchy: they benefit from the privileges of affluence without the scrutiny of the ultra-rich. Their net worth—whether $750,000 in Dallas or £1.5 million in London—grants access to elite education for their children, tax-advantaged investment vehicles, and the ability to self-insure against medical emergencies. Yet the real advantage isn’t the money itself but the psychological buffer it provides. A parent who can afford private school isn’t just buying an education; they’re buying peace of mind in a competitive job market. The trade-off is visibility. Unlike the wealthy elite, whose fortunes are often private, the upper middle class’s wealth is performative. They attend the right charities, send their kids to the right camps, and drive the right cars—not to flaunt, but to signal belonging. This performativity isn’t vanity; it’s a survival strategy in a world where social capital matters as much as financial capital. The upper middle class understands that their net worth is only as secure as their reputation."Upper middle class isn’t about what you have; it’s about what you’re seen to protect. A $1.5 million net worth in Boston means nothing if your neighbors assume you’re living beyond your means." — Economist and wealth psychologist Dr. Elena Vasquez
Major Advantages
- Intergenerational wealth transfer: Upper middle-class families can fund college without crippling debt, ensuring their children enter the workforce with fewer barriers.
- Geographic flexibility: Unlike lower-income groups, they can afford to move for career opportunities without sacrificing lifestyle.
- Tax optimization: Access to financial advisors and tax-efficient vehicles (e.g., HSAs, 529 plans) reduces effective tax burdens.
- Network effects: Membership in professional associations, alumni networks, and exclusive clubs opens doors that income alone can’t.
- Legacy planning: Even without seven-figure estates, they can structure trusts and estate plans to preserve wealth for heirs.
Comparative Analysis
| Metric | Upper Middle Class (U.S.) | Lower Middle Class (U.S.) | |--------------------------|------------------------------------|------------------------------------| | Net Worth Range | $500,000 – $2 million | $100,000 – $250,000 | | Primary Asset | Home equity (60-70%) | Home equity (40-50%) + retirement | | Debt Strategy | Mortgage leverage, low consumer debt| High consumer debt, credit cards | | Lifestyle Signals | Private school, vacations, club memberships | Public school, budget travel, used cars | | Wealth Transmission | College funds, trusts | Emergency savings, paycheck-to-paycheck |Future Trends and Innovations
The definition of how much net worth is upper middle class is evolving faster than ever due to three macro trends. First, student debt is redefining entry points: a 2024 graduate with $100,000 in loans may start their career with a net worth below zero, delaying their ascent into the upper middle class by a decade. Second, remote work is compressing geographic disparities: a software engineer in Nashville with $1.2 million in net worth now competes with peers in San Francisco who may have the same figure but higher living costs. Finally, AI and automation are eroding traditional career ladders, forcing upper middle-class professionals to pivot from linear wealth accumulation to portfolio careers—consulting, freelancing, and side hustles that generate income without traditional employer benefits. The next decade may see the upper middle class shrink in numbers but grow in complexity. Those who thrive will be those who treat net worth as a dynamic variable, not a fixed target. A family in Atlanta with $900,000 in assets today might need to diversify into cryptocurrency, real estate syndications, or private equity to maintain their status as the cost of healthcare and education outpaces inflation. The old playbook—buy a home, max out retirement accounts, and ride it out—is no longer sufficient.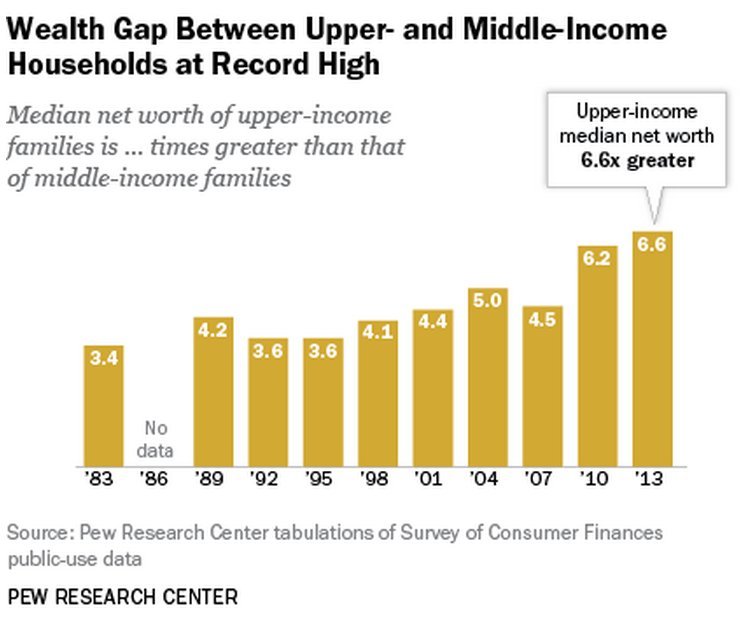
Conclusion
The question of how much net worth is upper middle class has no single answer because the upper middle class itself is a moving target. It’s the tier where financial security meets the gnawing fear of falling back, where a $1.5 million net worth in Ohio feels like a safety net and the same figure in Manhattan feels like a starting point. The real insight isn’t the number but the mental model behind it: a willingness to defer gratification, a tolerance for risk, and an understanding that wealth in this bracket is less about accumulation and more about protection. For those aspiring to join this tier, the path isn’t about hitting a specific net worth milestone but about building a lifestyle that feels secure within their peer group. That might mean a $750,000 home in Phoenix or a $2 million portfolio in Zurich—both are valid, as long as they align with local expectations. The upper middle class isn’t a destination; it’s a negotiated identity, one that requires constant recalibration in an economy where the rules change with every election cycle and market correction.Comprehensive FAQs
Q: Can you be upper middle class with a negative net worth?
A: Technically, no. The upper middle class is defined by positive net worth, typically starting around $500,000 in the U.S. However, high earners with significant debt (e.g., student loans, mortgages) may live like upper middle-class households without the asset base to match. True upper middle-class status requires liquid assets or equity that outstrip liabilities.
Q: Does homeownership automatically qualify someone as upper middle class?
A: Not necessarily. A homeowner with a $400,000 mortgage and $50,000 in savings may own property but lack the net worth to be considered upper middle class. The threshold depends on equity position—upper middle-class households typically have 50%+ equity in their primary residence, with minimal high-interest debt.
Q: How does inheritance affect upper middle-class net worth?
A: Inheritance can catapult someone into the upper middle class overnight, but it’s not a prerequisite. Many upper middle-class families build wealth organically through career progression, real estate, and disciplined saving. Inherited wealth often accelerates their timeline but doesn’t define the tier—many upper middle-class individuals are first-generation accumulators.
Q: Are there regional differences in upper middle-class net worth?
A: Yes. In high-cost cities (e.g., NYC, San Francisco), upper middle-class net worth starts around $1.5–2 million, while in lower-cost regions (e.g., Midwest, Southeast), $700,000–$1 million may suffice. The key is relative affluence—can you afford private school, healthcare, and retirement without dipping into principal?
Q: Can you be upper middle class without a college degree?
A: Absolutely. Many upper middle-class households are built by entrepreneurs, skilled tradespeople, or high-earning professionals in non-degree fields (e.g., electricians, real estate developers). The defining factor is income stability and asset accumulation, not educational attainment. However, degrees often provide network and credential advantages that speed up wealth-building.
Q: How does the upper middle class differ from the affluent?
A: The upper middle class focuses on security and legacy, while the affluent prioritize growth and liquidity. An upper middle-class household may have $1.2 million in assets but keep 80% tied to their home; an affluent family with the same net worth might hold diversified investments, private equity, or multiple properties. The affluent also tend to have higher liquidity ratios (cash/investments vs. illiquid assets).
Q: What’s the biggest financial mistake upper middle-class families make?
A: Overleveraging for lifestyle inflation. Many upper middle-class households upgrade to luxury cars, second homes, or private schools without recalculating how these expenses impact long-term net worth growth. The mistake isn’t spending—it’s spending in ways that erode future financial flexibility. For example, a $150,000 car may feel like a status symbol but could delay retirement by five years if the funds were invested instead.
