
Where It All Began
Shell’s origins weren’t in high finance but in the gritty trade routes of the British Empire. Marcus Samuel, a London merchant, had made his fortune selling seashells—until he noticed the black residue clinging to the dhows returning from the Malay Archipelago. That residue was oil, and by 1892, Samuel had pivoted entirely to fuel. His company, Shell Transport, began buying oil from wildcatters in the Dutch East Indies, then shipping it to Europe in converted ships. The early net worth of Shell was tied to these tankers and the refineries that followed. By 1900, the company had built its first major refinery in the Netherlands, a move that would later anchor its European operations. The real inflection point came in 1907, when Shell merged with Royal Dutch Petroleum to form Royal Dutch Shell. The deal created the world’s first multinational oil company, with assets spanning the globe. This merger wasn’t just about scale; it was about survival. The new entity could afford to drill where others couldn’t, securing concessions in the Middle East even as smaller players were squeezed out. The net worth of Shell at this stage was less about publicly traded shares and more about the silent value of exclusive drilling rights. By the 1920s, the company had become a linchpin of global energy, its financial health directly linked to the rise of the automobile and aviation industries.The Early Signs
Shell’s financial strategy in its first half-century was simple: dominate the supply chain. While American independents like Standard Oil focused on vertical integration, Shell bet on horizontal control—owning the wells, the pipelines, and the retail outlets. This model paid off during World War I, when Shell’s tankers kept Allied forces fueled. The company’s profits during the war years were reinvested into expanding its refining capacity, particularly in the Netherlands and the UK. By the 1930s, Shell had become the largest oil company in Europe, its net worth growing not just from oil but from the chemicals and lubricants spun off its refining operations. The Depression tested Shell’s model, but its diversified holdings—including a stake in the newly formed Iraqi Petroleum Company—kept it afloat. The company also pioneered marketing tactics that would define modern branding, from the iconic yellow-and-red "Pecten" logo to the first motorist service stations. These weren’t just revenue streams; they were financial safeguards. By the time World War II began, Shell’s net worth was no longer just about crude. It was about infrastructure—pipelines in the Caucasus, refineries in the Far East, and a network of depots that spanned three continents. The war would force Shell to adapt, but its financial foundation was unshakable.The Turning Point
The 1970s oil crisis didn’t just disrupt markets—it rewrote the rules of Shell’s financial playbook. When OPEC embargoed oil exports in 1973, prices quadrupled overnight. Shell, unlike some competitors, had anticipated the shift. The company had already begun diversifying into natural gas and petrochemicals, reducing its exposure to crude price volatility. While other majors hemorrhaged profits, Shell’s net worth remained stable, thanks to its integrated model. The crisis also accelerated Shell’s move into global markets, particularly in Asia, where demand for energy was rising faster than supply. The real turning point came in the 1980s, when Shell made a controversial but financially astute decision: it began selling off non-core assets. The company divested from retail gas stations and even some refining operations, focusing instead on upstream oil and gas production. This shift wasn’t just about cutting costs—it was about repositioning Shell as a high-margin energy player. By the end of the decade, the company’s net worth was no longer tied to the whims of oil price swings but to its ability to extract and refine at scale. The 1980s also saw Shell embrace environmental, social, and governance (ESG) considerations before they became industry buzzwords, a move that would later insulate its financial reputation during regulatory crackdowns."Shell didn’t just survive the oil shocks—it turned them into a competitive advantage. While others panicked, we bet on diversification and long-term infrastructure. That’s how you build a net worth that outlasts commodity cycles." — Shell’s former CEO, Jeroen van der Veer, in a 2010 interview
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1907–1939 | Mergers create Royal Dutch Shell; expands into Middle East and Southeast Asia. Net worth tied to exclusive drilling rights and refining capacity. |
| 1945–1973 | Post-war reconstruction boosts demand; Shell invests in chemicals and lubricants. Diversification shields early net worth from crude price volatility. |
| 1973–1985 | Oil crises force asset sales and gas expansion. Shell’s integrated model keeps net worth resilient amid market turbulence. |
| 1986–2000 | Focus shifts to upstream production; major discoveries in Nigeria and Qatar. Net worth grows as Shell becomes a top-three global oil producer. |
| 2001–Present | Renewable energy investments (solar, hydrogen) alongside traditional oil. Net worth now reflects dual strategy—though oil remains core. |
Lessons From the Journey
- Diversification isn’t just a buzzword—Shell’s ability to pivot from oil to gas to renewables has kept its net worth stable through every commodity cycle.
- Geopolitical savvy matters more than raw drilling. Shell’s early concessions in the Middle East set the stage for decades of financial dominance.
- Branding creates hidden value. The "Shell" name isn’t just a logo—it’s a guarantee of supply, which translates to premium pricing and customer loyalty.
- Regulatory agility is a financial safeguard. Shell’s early ESG commitments helped it navigate climate lawsuits and carbon taxes better than competitors.
- The net worth of Shell today isn’t just about today’s profits—it’s about the infrastructure and talent it’s built over a century. That’s harder to replicate than a single oil field.
Where Things Stand Today
Shell’s current net worth is a study in contrasts. On one hand, it’s a £150 billion corporation with operations in 70 countries, its market cap fluctuating with oil prices but rarely dipping below £100 billion. On the other, it’s a company caught between two futures: the fading dominance of fossil fuels and the uncertain rise of renewables. The tension is visible in its financial reports—where oil and gas still account for 80% of profits, but hydrogen and solar projects are the fastest-growing segments. The net worth of Shell isn’t just a reflection of today’s energy markets; it’s a bet on which side of history the company will land on. What’s clear is that Shell’s financial strategy has evolved. The days of relying solely on crude reserves are over. The company has become a hybrid—part traditional oil major, part energy transition player. Its recent investments in carbon capture and offshore wind farms aren’t just PR moves; they’re financial hedges. If oil prices collapse, Shell’s renewables portfolio could offset losses. If renewables take over, the company’s existing infrastructure gives it a head start. The net worth of Shell in 2024 isn’t just about today’s profits—it’s about which assets will be valuable in 2050.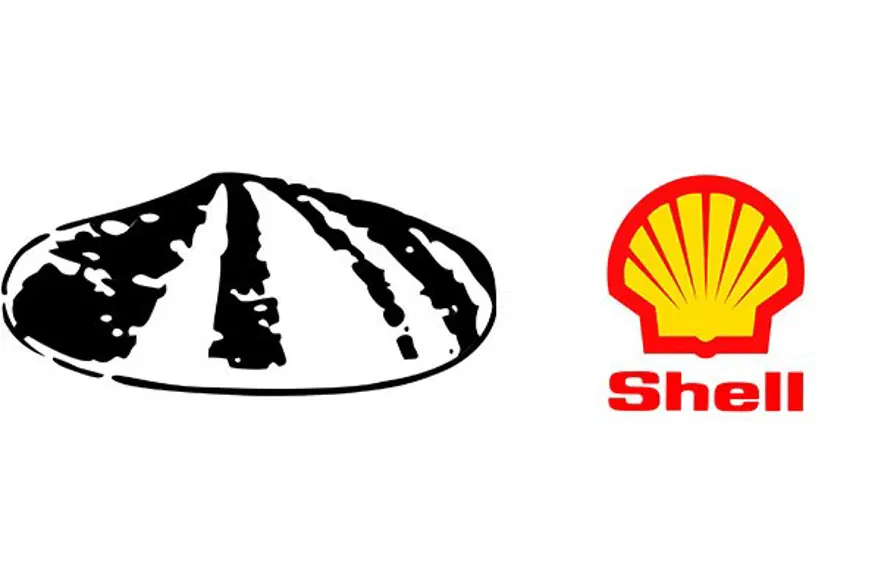
Conclusion
The net worth of Shell is more than a balance sheet figure. It’s a historical record of how energy shapes economies, how corporations navigate crises, and how financial strategies outlast the people who create them. From the button-making dhows of 1892 to the hydrogen hubs of 2024, Shell’s journey mirrors the rise and fall of entire industries. The company’s ability to reinvent itself—whether through mergers, divestments, or green investments—has kept its net worth growing even as the world around it changed. There’s a lesson here for any business tracking its own financial trajectory. Shell didn’t succeed by clinging to the past; it succeeded by anticipating the future. Whether that future belongs to oil, gas, or something else entirely, the company’s net worth will continue to be a benchmark—not just for energy, but for how corporations adapt when the world demands it.Comprehensive FAQs
Q: How does Shell’s net worth compare to other oil majors like Exxon or BP?
Shell’s market capitalization is typically higher than BP’s but lower than ExxonMobil’s at its peak. However, Shell’s diversified holdings—including renewables and chemicals—give it a more stable net worth than pure-play oil companies. Exxon’s value is more volatile due to its heavier focus on crude production, while BP’s net worth has been more affected by past environmental fines and divestments.
Q: What’s the biggest threat to Shell’s net worth today?
The biggest risks are geopolitical instability in key oil regions (like the Middle East or Nigeria) and the speed of the energy transition. If governments enforce rapid decarbonization, Shell’s oil assets could become stranded. Conversely, if renewables fail to scale quickly enough, the company’s net worth could remain tied to volatile oil markets for decades longer than planned.
Q: Does Shell’s net worth include its renewable energy investments?
Yes, but only partially. While Shell’s hydrogen and solar projects are growing, their contribution to the overall net worth is still small compared to oil and gas. Analysts estimate renewables account for less than 10% of Shell’s current valuation, though that figure is rising as the company accelerates its green investments.
Q: How has Shell’s net worth changed over the past decade?
Shell’s net worth has seen significant fluctuations. During the 2014 oil price crash, its market cap dropped by nearly 50%, but it recovered as demand rebounded. The COVID-19 pandemic caused another dip, though the company’s diversified revenue streams limited the damage. More recently, geopolitical tensions (like Russia’s invasion of Ukraine) have boosted Shell’s profits from European gas sales, temporarily inflating its net worth.
Q: Can Shell’s net worth survive a full transition to renewable energy?
It’s possible, but unlikely in its current form. Shell has positioned itself as a "transition company," meaning it’s betting on a gradual shift rather than an abrupt one. If oil demand collapses faster than expected, Shell’s net worth could shrink unless its renewables portfolio scales dramatically. The company’s advantage lies in its existing infrastructure—pipelines and refineries can often be repurposed for green energy—but the financial transition would still be massive.
