The Complete Overview of What Is the Net Worth Formula
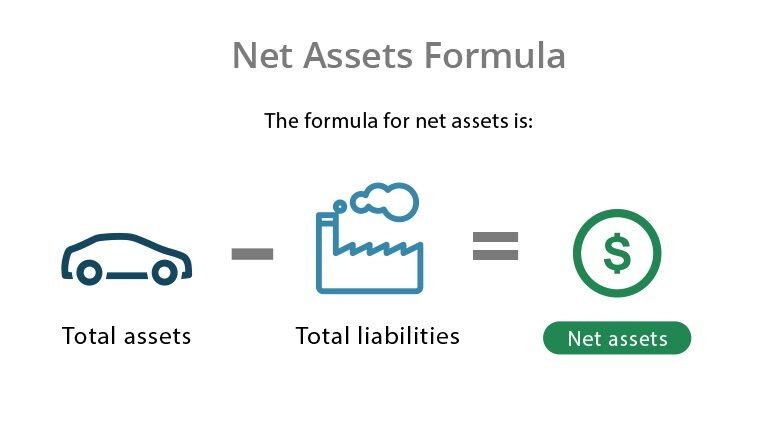
At its core, what is the net worth formula is a financial identity: assets minus liabilities equals net worth. But the execution varies based on context. For individuals, assets typically include cash, investments, real estate, vehicles, and intellectual property (like patents or royalties). Liabilities encompass mortgages, loans, credit card balances, and even unpaid taxes. The result—a single number—serves as a benchmark for financial health, risk tolerance, and long-term planning. Yet this simplicity masks complexity. A $1 million net worth in San Francisco buys a fraction of the lifestyle it would in Wichita, Kansas. The formula’s power lies in its adaptability: it works for a freelancer tracking gig earnings, a family estimating college fund growth, or a corporation valuing intangible assets like brand equity. The formula’s limitations become clear when applied to volatile assets. Cryptocurrency holdings might spike one month and vanish the next; private company stock can be illiquid until an exit event. Even tangible assets like art or collectibles require appraisals that fluctuate with trends. The formula doesn’t account for time—an heirloom with sentimental value might have zero market liquidity. And it ignores human capital: the potential future earnings of a medical resident or a coding bootcamp graduate. These nuances explain why net worth statements often include footnotes, disclaimers, or ranges (e.g., "net worth between $X and $Y, depending on valuation methods"). The formula is a tool, not an oracle.Historical Background and Evolution
The concept of net worth predates modern accounting by centuries. Medieval merchants in Venice and Florence used similar calculations to assess a trader’s creditworthiness before extending loans. Their ledgers tracked inventory (assets) against debts (liabilities), much like today’s personal balance sheets. The term "net worth" itself emerged in 18th-century England, where industrialists and bankers formalized the practice of valuing businesses by subtracting liabilities from tangible assets. This method became the backbone of corporate finance, influencing everything from the South Sea Bubble of 1720 to the Great Depression-era reforms that standardized financial reporting. The 20th century transformed net worth from a merchant’s tool into a household metric. The rise of consumer credit in the 1950s and 1960s made liabilities more visible, while the personal computer revolution of the 1980s democratized tracking. Software like Quicken and later apps like Mint allowed individuals to automate calculations that once required ledger books. The formula also evolved to reflect new asset classes: the dot-com boom introduced stock options, the 2008 financial crisis highlighted the risks of leverage, and the gig economy forced freelancers to treat their skills as semi-liquid assets. Today, the formula is as likely to be discussed in a Silicon Valley boardroom as it is in a suburban kitchen over dinner.Core Mechanisms: How It Works
The formula’s elegance lies in its binary structure: what you own (assets) minus what you owe (liabilities). But the execution demands precision. Assets are categorized into liquid (cash, savings) and illiquid (real estate, retirement accounts). Liabilities are split into secured (mortgages, auto loans) and unsecured (credit cards, medical debt). The challenge isn’t the math—it’s the valuation. A rental property’s net worth isn’t just its market price; it’s adjusted for vacancy rates, maintenance costs, and depreciation. A 401(k) might be worth $500,000 on paper, but if the account holder is 55, only a portion is accessible without penalties. The formula also reveals hidden variables. For example, a high net worth individual might have a negative net worth if their primary residence is underwater, or if their business assets are overvalued. Conversely, someone with modest assets but no debt could have a net worth that exceeds expectations. The formula’s dynamic nature means it’s not a static number but a moving target. A single event—a stock market crash, a divorce settlement, or an unexpected medical bill—can reset the calculation overnight. This volatility is why financial planners emphasize what is the net worth formula as a starting point, not an endpoint.Key Benefits and Crucial Impact
Understanding what is the net worth formula shifts the conversation from "how much do I make?" to "what do I control?" It forces clarity on financial priorities: Should you pay off a credit card or invest in a rental property? Is that luxury car an asset or a liability disguised as fun? The formula doesn’t provide answers—it frames the questions. For creditors, it’s a risk assessment tool; for entrepreneurs, it’s a pitch deck staple. Even governments use net worth thresholds to determine eligibility for programs like Medicaid or Social Security benefits. The formula’s universality makes it both a personal and a societal metric. Yet its impact extends beyond numbers. A net worth statement can be a mirror, reflecting lifestyle choices, generational wealth gaps, or systemic inequities. Studies show that households headed by Black or Latino individuals often have lower net worth due to historical barriers like redlining or wage disparities. The formula doesn’t explain these disparities, but it quantifies them—making the case for policy changes or targeted financial education. For individuals, it’s a wake-up call: a $100,000 salary might sound impressive until you see that $80,000 of it goes to debt service, leaving little for wealth-building."Net worth is the residue of your life’s financial decisions. It’s not about how much you earn; it’s about how much you keep, how much you grow, and how much you protect." — Carl Richards, The New York Times financial columnist
Major Advantages
- Financial clarity: The formula distills complex finances into one number, making it easier to track progress toward goals like retirement or homeownership.
- Debt management insight: By isolating liabilities, it highlights which debts are dragging down net worth and which (like a mortgage) might be strategic.
- Investment focus: A high net worth relative to income suggests opportunities for diversification; a low net worth may indicate the need for debt reduction.
- Risk assessment: Lenders, insurers, and even employers use net worth as a proxy for stability—understanding the formula helps individuals manage perceptions.

Comparative Analysis
| Individual Net Worth | Corporate Net Worth |
|---|---|
| Assets: Cash, real estate, investments, personal property | Assets: Tangible (machinery, inventory), intangible (patents, goodwill) |
| Liabilities: Mortgages, loans, credit cards, taxes | Liabilities: Debt, accounts payable, contingent liabilities (lawsuits) |
| Valuation challenges: Subjective (e.g., art, collectibles) | Valuation challenges: Market volatility (e.g., commodity prices) |
| Purpose: Personal financial health, eligibility for programs | Purpose: Investor confidence, regulatory compliance |
| Frequency of update: Monthly/quarterly | Frequency of update: Annual (GAAP requirements) |
Future Trends and Innovations
The net worth formula is evolving alongside technology. Blockchain and decentralized finance (DeFi) introduce new asset classes—crypto holdings, NFTs, and smart contracts—that complicate traditional valuations. For example, an NFT’s "net worth" might depend on secondary market activity, not intrinsic value. Meanwhile, AI-driven financial tools now predict net worth trajectories based on spending habits, offering personalized advice. The rise of "financial wellness" apps also shifts focus from static snapshots to dynamic tracking, with real-time alerts for cash flow changes. Regulatory changes will further reshape the formula. Stricter disclosure rules for private company stock (like those proposed for SPACs) could force more granular net worth reporting. Climate-related risks may also enter the equation, as investors demand ESG (environmental, social, governance) metrics alongside traditional financials. For individuals, the formula’s future lies in integration with biometric data—imagine a net worth dashboard that factors in health metrics, like life expectancy, to estimate future earning potential. The formula itself won’t change, but its components will grow more nuanced.
Conclusion
What is the net worth formula is more than arithmetic; it’s a lens through which to view financial reality. It doesn’t judge, but it exposes. A negative net worth isn’t failure—it’s a starting point. A seven-figure net worth isn’t success unless it aligns with personal values. The formula’s genius is its flexibility: it works for a recent graduate with student loans and a side hustle, or a retiree managing a portfolio. Its limitations—subjective valuations, market risks—are also its strengths, forcing users to confront what truly matters. The real question isn’t how to calculate net worth, but how to use it. Should you aim for a specific number, or use it to guide decisions? Is it a tool for security, or a measure of freedom? The answer depends on who’s asking. For the young professional, it’s about building; for the near-retiree, it’s about preserving. For the philanthropist, it’s about legacy. The formula remains the same, but the story it tells changes with every life stage.Comprehensive FAQs
Q: Can net worth ever be negative?
A: Yes. A negative net worth occurs when liabilities exceed assets—common for recent graduates with student loans, homeowners with underwater mortgages, or businesses in distress. While alarming, it’s not irreversible. Strategies like debt consolidation, asset liquidation, or increasing income can improve the ratio over time.
Q: How often should I update my net worth?
A: Frequency depends on volatility. High-net-worth individuals or those with volatile assets (e.g., stock traders) may update monthly. For most people, quarterly reviews suffice, especially if major transactions (like buying a home) are infrequent. Automated tools can simplify tracking.
Q: Does net worth include future earnings potential?
A: No, not directly. Net worth is a snapshot of current assets and liabilities. However, human capital (future earning ability) is sometimes factored into broader financial planning. For example, a doctor’s residency might be considered an "asset" in long-term projections, even though it’s not liquid.
Q: How do taxes affect net worth calculations?
A: Taxes can impact net worth in two ways: as a liability (unpaid taxes reduce net worth) or as a drag on asset growth (capital gains taxes erode investment returns). Some assets, like retirement accounts, are valued pre-tax, while others (like a primary residence) may qualify for tax exemptions. Always consult a tax professional to avoid under- or overstating liabilities.
Q: Is a high net worth always a sign of financial health?
A: Not necessarily. A high net worth could stem from illiquid assets (e.g., a family business with no exit strategy), excessive leverage (e.g., a portfolio of rental properties with high vacancy risks), or one-time windfalls (e.g., an inheritance). True financial health considers liquidity, risk diversification, and alignment with personal goals—not just the bottom-line number.
