The Short Answers
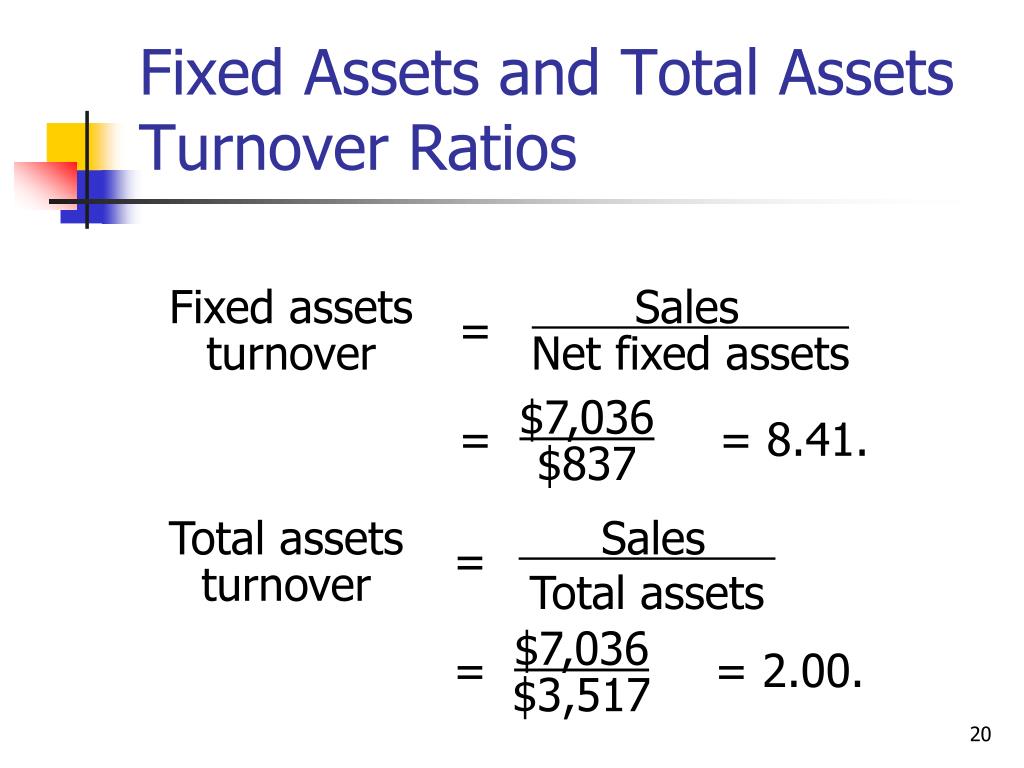
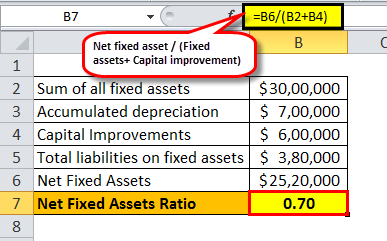
- The net fixed assets equation is gross fixed assets minus accumulated depreciation, revealing a company’s true investment in long-term physical assets.
- It directly impacts metrics like return on assets (ROA) and debt coverage ratios, making it critical for lenders and investors.
- Depreciation methods (straight-line vs. accelerated) can alter the equation’s outcome by years, affecting taxable income and reported profitability.
- Companies often reclassify assets between fixed and intangible categories to optimize this equation for financial reporting.
- Industries with high capital intensity—like manufacturing or energy—rely on this equation more heavily than service sectors.
- A negative net fixed asset value signals potential liquidation risks or aggressive depreciation policies.
Deep Dive: The Full Picture
The net fixed assets equation isn’t just a line item on a balance sheet; it’s a reflection of a company’s industrial DNA. Take a manufacturer like Tesla. Its net fixed assets equation would include not only the value of its Gigafactories but also the accumulated depreciation of assembly lines, robotics, and testing equipment—all of which must be replaced or upgraded to maintain production levels. The equation forces a confrontation with the law of diminishing returns: even the most advanced machinery loses efficiency over time. For Tesla, this means balancing R&D spend against the need to refresh its fixed asset base every 5–7 years, a decision that directly influences its capital expenditure budgets. Conversely, a software company like Salesforce may have minimal fixed assets beyond office space and servers. Its net fixed assets equation would be far less volatile, yet still critical during IPO filings or when seeking debt financing. Lenders examining Salesforce’s balance sheet would weigh its net fixed assets against intangible assets (like patents) to assess collateral risk. The equation’s simplicity belies its complexity: it’s not just about numbers but about aligning a company’s physical infrastructure with its growth trajectory.The Context You Need
Understanding the net fixed assets equation requires grasping two accounting principles: historical cost and matching. Assets are recorded at their purchase price, not their current market value—a relic of conservative accounting that prevents overstatement of equity. Meanwhile, depreciation spreads the cost of an asset over its useful life, matching expenses to the revenue it generates. This duality creates tension: a company might hold assets worth far more on the open market than their book value, yet the net fixed assets equation reflects only the depreciated amount. The equation also serves as a litmus test for capital discipline. Consider a retail giant like Walmart. Its net fixed assets equation would include stores, distribution centers, and delivery fleets—all subject to rapid obsolescence. If Walmart’s depreciation policy underestimates the useful life of its assets, it could face unexpected reinvestment needs, squeezing margins. Alternatively, if it overestimates, it might defer necessary upgrades, risking operational inefficiencies. The equation thus becomes a tool for strategic trade-offs: should the company invest in automation now or defer costs to boost short-term earnings?The Mechanics
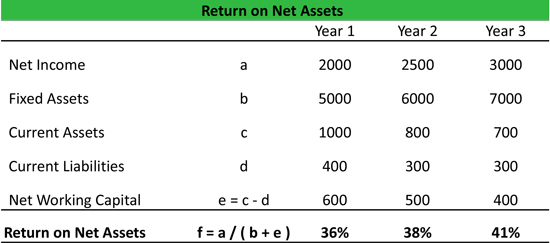
Breaking down the net fixed assets equation reveals three key variables: 1. Gross fixed assets: The total cost of all long-term physical assets, from land to machinery. 2. Accumulated depreciation: The cumulative reduction in asset value due to wear, age, or obsolescence. 3. Net fixed assets: The residual value after depreciation, representing the company’s net investment in its productive capacity. The choice of depreciation method—whether straight-line, double-declining balance, or units-of-production—can dramatically alter the equation’s trajectory. A company using accelerated depreciation will show higher expenses early in an asset’s life, reducing taxable income but preserving net fixed assets for longer. This isn’t just an accounting trick; it’s a financial strategy. For example, a mining company might use accelerated depreciation to defer tax payments while maintaining higher net fixed asset values for potential asset sales later.Details That Change the Picture
The net fixed assets equation isn’t static. It evolves with asset impairments, revaluations, and even regulatory changes. During economic downturns, companies may impair assets—writing down their value to reflect market realities—thus shrinking the net fixed asset base. Conversely, during booms, firms might revalue assets upward, inflating the equation’s numerator. These adjustments aren’t arbitrary; they’re signals of a company’s financial health. A sudden impairment suggests overcapacity or poor asset management, while revaluations may indicate strategic realignment. The equation also interacts with off-balance-sheet items. Leased assets, for instance, don’t appear in the net fixed assets equation under operating leases, yet they still represent long-term commitments. This creates a hidden layer of fixed asset exposure that analysts must unpack. For example, a company might lease a factory for 20 years, avoiding depreciation charges but incurring fixed lease payments that effectively mimic asset ownership."The net fixed assets equation is where theory meets the grind of physical reality. You can model cash flows until you’re blue in the face, but if your factories are falling apart or your equipment is obsolete, the numbers don’t lie—your balance sheet will." —Former CFO of a Fortune 500 industrial conglomerate
| Scenario | Impact on Net Fixed Assets Equation |
|---|---|
| Acquisition of a new production line | Gross fixed assets increase; net fixed assets rise initially before depreciation kicks in. |
| Asset impairment due to market downturn | Accumulated depreciation spikes, reducing net fixed assets sharply. |
| Switch from straight-line to accelerated depreciation | Higher early-year depreciation; net fixed assets decline faster initially but stabilize later. |
| Sale of obsolete machinery | Gross fixed assets and accumulated depreciation both decrease, but net effect depends on sale proceeds. |
| Revaluation of land holdings upward | Gross fixed assets increase (if land is revalued), but net fixed assets may rise only if depreciation is recalculated. |
Conclusion
The net fixed assets equation is more than a mechanical calculation—it’s a barometer of a company’s industrial vitality. It exposes the tension between short-term profitability and long-term sustainability, forcing executives to confront the tangible costs of growth. For investors, it’s a window into operational resilience; for regulators, it’s a check against financial engineering. Ignore it, and you risk misjudging a company’s true capacity to generate returns. Yet the equation’s power lies in its simplicity. It doesn’t require complex models or predictive analytics—just an understanding of how assets age, how depreciation erodes value, and how these factors interplay with a company’s broader financial strategy. In an era where intangible assets dominate headlines, the net fixed assets equation remains a grounding force, reminding us that even the most innovative firms are bound to the laws of physics—and accounting.Comprehensive FAQs
Q: How does the net fixed assets equation affect a company’s tax liability?
The equation influences taxable income through depreciation deductions. Accelerated depreciation methods (like MACRS in the U.S.) reduce taxable income faster, lowering tax liabilities in early years but increasing them later when assets are fully depreciated. Straight-line depreciation spreads the deduction evenly, offering smoother tax impacts but potentially higher early-year taxes.
Q: Can a company manipulate the net fixed assets equation for financial reporting?
Yes, through asset reclassifications, depreciation method changes, or impairment decisions. For example, a company might reclassify a long-term asset from fixed to intangible to alter its depreciation profile. However, aggressive manipulation risks triggering audits or regulatory scrutiny, especially under IFRS or GAAP rules.
Q: Why do some industries have higher net fixed asset ratios than others?
Capital-intensive industries—like manufacturing, energy, or transportation—require significant fixed assets (factories, pipelines, aircraft) and thus have higher ratios. Service industries (consulting, software) rely more on intangibles (patents, brand) and human capital, resulting in lower net fixed asset ratios.
Q: How does lease accounting (ASC 842/IFRS 16) change the net fixed assets equation?
Under new lease standards, operating leases now appear on the balance sheet as right-of-use assets and lease liabilities. This increases gross fixed assets (or a similar line item) and introduces corresponding lease liabilities, which don’t directly affect the net fixed assets equation but create a parallel fixed-asset-like exposure.
Q: What happens if a company’s net fixed assets turn negative?
A negative value typically indicates accumulated depreciation exceeds gross fixed assets, suggesting over-depreciation, asset impairments, or liquidation risks. It’s rare in healthy companies but can occur in distressed firms or those with aggressive depreciation policies.
Q: How do mergers and acquisitions (M&A) impact the net fixed assets equation?
In an acquisition, the buyer may revalue the target’s assets (e.g., writing up depreciated machinery), which inflates gross fixed assets and temporarily boosts net fixed assets. Conversely, if the target has impaired assets, the buyer may recognize additional depreciation, reducing net fixed assets. Post-merger, the combined entity’s equation reflects the blended depreciation policies of both firms.
