
7 Things Worth Knowing About On the June 30 Balance Sheet What Is the Net Worth or Net Assets of the Business
The June 30 closing date isn’t arbitrary. For many public companies, it aligns with fiscal year-ends, tax filings, or seasonal business cycles. But the timing also creates a unique challenge: how to reconcile net assets at a point where working capital, debt maturities, and market conditions may be in flux. The following seven factors explain why the answer to what does the June 30 balance sheet show for net worth? is never as straightforward as it seems.1. Net Worth ≠ Market Capitalization
The balance sheet’s net worth—calculated as total assets minus total liabilities—often bears little resemblance to a company’s market cap. For example, a manufacturing firm might list property, plant, and equipment at historical cost minus depreciation, while the real estate market values those assets at 30% higher. Meanwhile, the company’s stock price reflects growth expectations, not just tangible assets. The disconnect is especially stark for asset-heavy industries like utilities or airlines, where book value can lag behind economic reality. Investors fixate on market cap because it incorporates future earnings potential; accountants focus on historical cost because that’s what auditors demand.2. Intangible Assets Are Often Undervalued
Goodwill, patents, and brand value rarely appear on the balance sheet at anywhere near their true worth. When a company acquires another, it records goodwill—the excess of purchase price over net assets—as an asset. But goodwill is tested annually for impairment, and if the market value of the acquired business drops, that goodwill can vanish overnight. For businesses where intangibles drive value—think pharmaceuticals or media—this creates a distorted picture. A June 30 balance sheet might show a net worth that excludes the full value of a blockbuster drug in development, simply because it hasn’t been commercialized yet.3. Off-Balance-Sheet Financing Distorts the View
Not all liabilities appear on the balance sheet. Operating leases, joint ventures, and special-purpose entities can hide debt or obligations. Before new accounting rules (ASC 842 for U.S. firms), many companies leased assets without recording them as debt. Even now, some forms of financing—like securitized receivables—remain off-balance-sheet, artificially inflating reported net worth. The result? A company might look healthier than it is, lulling creditors into a false sense of security. This was a key factor in the 2008 financial crisis, where banks used off-balance-sheet vehicles to mask leverage.4. Working Capital Fluctuations Matter More Than Static Numbers
A June 30 balance sheet might show strong net worth, but if accounts receivable are aging or inventory is obsolete, the company could be sitting on a time bomb. Working capital—current assets minus current liabilities—is a better predictor of short-term health than net worth alone. For seasonal businesses (like agriculture or retail), June 30 might coincide with a cash flow trough, making the balance sheet look weaker than it is at other times. Analysts often adjust for this by comparing working capital ratios across periods, not just absolute net worth figures.5. Currency and Inflation Adjustments Can Skew Results
Companies with global operations face another layer of complexity: exchange rates. If a U.S. firm’s European subsidiary holds cash in euros, a sudden currency devaluation could wipe out reported net worth overnight—even if the underlying business is profitable. Similarly, historical-cost accounting ignores inflation, meaning assets purchased decades ago may appear artificially cheap. Some firms use inflation-adjusted figures in internal reports, but these rarely appear in public filings. This is why comparing net worth across time periods without adjusting for inflation can be misleading.6. Management’s Choices Affect the Numbers
Accounting policies aren’t neutral. A company can choose between FIFO and LIFO for inventory valuation, accelerate or defer revenue recognition, or capitalize rather than expense certain costs. These choices can shift net worth by millions without changing the underlying business. For example, a firm that capitalizes software development costs will show higher assets (and thus higher net worth) than one that expenses them immediately. The SEC requires consistency, but the leeway still exists—and savvy executives use it to smooth earnings or boost reported equity.7. Debt and Equity Structure Creates Illusions
Some companies issue hybrid securities—like convertible bonds—that blur the line between debt and equity. If these instruments are classified as debt, they reduce net worth; if equity, they don’t. The classification can hinge on technicalities, such as whether the bondholder has a right to vote. Meanwhile, share buybacks can inflate reported earnings per share while reducing total equity. The result? A company might appear more profitable and better capitalized than it is, obscuring its true financial flexibility.
How These Facts Connect
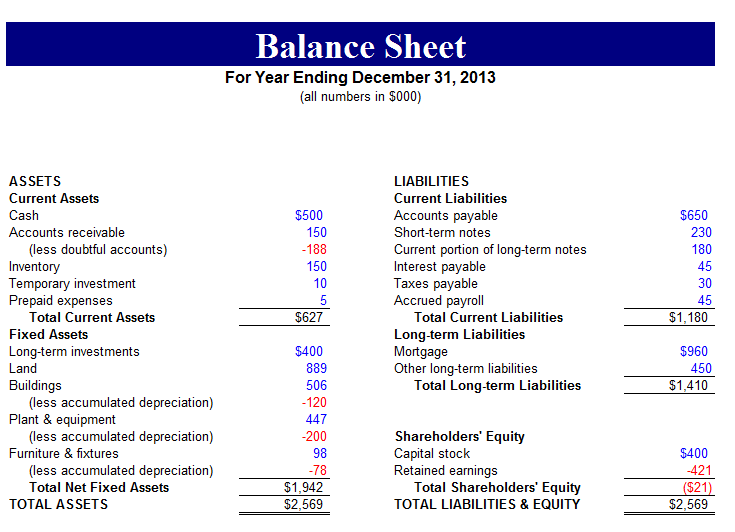
The June 30 balance sheet isn’t just a financial statement; it’s a negotiation between transparency and strategic obfuscation. The answer to what is the net worth on the June 30 balance sheet? depends on whose perspective you take: an auditor’s (focused on compliance), an investor’s (focused on future cash flows), or a creditor’s (focused on collateral). The disconnect between book value and economic value isn’t a bug—it’s a feature of how businesses operate. Intangible assets, off-balance-sheet items, and management discretion all serve to align incentives: executives want to appear stable to shareholders, but they also want flexibility to adapt to market changes. What the balance sheet reveals is less about absolute net worth and more about how a company is positioned to weather risks. A tech startup might show negative net worth but massive deferred revenue—indicating future growth. A mature manufacturer might have strong net worth but stagnant revenue—suggesting it’s a cash cow rather than a growth engine. The key is to look beyond the headline number and ask: What does this balance sheet tell us about the company’s ability to generate cash, innovate, and survive downturns?| Factor | Impact on Net Worth | Example Industry | Red Flag | What to Watch For |
|---|---|---|---|---|
| Intangible Assets | Understated if not capitalized | Pharmaceuticals | Sudden goodwill impairment | Patent filings vs. R&D spend |
| Off-Balance-Sheet Items | Artificially inflated | Financial Services | Hidden leverage | Footnotes on leases/SPVs |
| Working Capital | Volatile without context | Retail | Aging receivables | Days sales outstanding (DSO) |
| Currency Fluctuations | Distorted by FX moves | Multinationals | Sudden translation losses | Hedging disclosures |
| Management Discretion | Can be manipulated | All industries | Aggressive revenue recognition | Changes in accounting policies |
Conclusion
The June 30 balance sheet is where finance meets reality—and where the two often collide. The question of what is the net worth or net assets on the June 30 balance sheet? has no single answer, because net worth is a construct, not a fact. It’s shaped by accounting rules, market conditions, and the choices of those who prepare the statements. For investors, the real work begins after reading the numbers: digging into footnotes, comparing trends, and asking whether the balance sheet reflects a company’s true potential—or just its ability to play by the rules. What’s clear is that no balance sheet tells the whole story. The best analysts don’t stop at net worth; they look at liquidity, debt covenants, and qualitative factors like management quality. The June 30 snapshot is just one frame in a much longer film—and the most valuable insights often come from what’s left unsaid.Comprehensive FAQs
Q: Why does the net worth on the June 30 balance sheet differ from other reporting periods?
The June 30 date is often a fiscal year-end or a point of high seasonal activity (e.g., retail inventory peaks). Unlike quarterly reports, which focus on recent performance, the June 30 balance sheet captures a full-cycle snapshot—including inventory levels, debt maturities, and currency exposures that may not be as visible in shorter periods. For example, a retailer might show higher net worth in June due to pre-holiday inventory buildup, even if margins are thin.
Q: Can a company legally inflate its net worth on the June 30 balance sheet?
Yes, within accounting guidelines. Techniques include capitalizing expenses (e.g., R&D), using favorable depreciation methods, or structuring transactions to avoid liability recognition. However, material misstatements can lead to SEC enforcement. The key is whether the methods are consistently applied and disclosed. For instance, a company might argue that its software development costs should be capitalized as an asset—boosting net worth—if they provide future economic benefit.
Q: How do intangible assets affect the net worth calculation on June 30?
Intangibles like goodwill, patents, or trademarks are recorded at acquisition cost minus amortization. If the market value of these assets declines (e.g., a patent becomes obsolete), the company must impair them—reducing net worth. On June 30, if impairment tests are triggered, the balance sheet could show a sharp drop in net assets, even if the underlying business is stable. For example, a biotech firm might see its net worth plummet if a drug candidate fails clinical trials, erasing the value of R&D capitalized as an asset.
Q: What’s the difference between net worth and shareholders’ equity on the June 30 balance sheet?
They’re often used interchangeably, but technically, shareholders’ equity is a component of net worth. Net worth = Total Assets – Total Liabilities. Shareholders’ equity = Common Stock + Retained Earnings + Other Equity (e.g., treasury stock). The two differ when there are minority interests or non-controlling shares. For example, a subsidiary’s net worth might include equity held by minority shareholders, which isn’t part of the parent’s shareholders’ equity.
Q: Should I trust the net worth figure if the company has off-balance-sheet liabilities?
No. Off-balance-sheet items—like operating leases, unfunded pension obligations, or special-purpose entities—can hide risks. The June 30 balance sheet might show strong net worth, but if the company has guaranteed debt for a joint venture, that liability isn’t reflected. Always check footnotes for disclosures on contingent liabilities. For instance, Enron’s collapse in 2001 was partly due to off-balance-sheet partnerships that masked its true financial health—its June 30 balance sheet looked solid until auditors dug deeper.
Q: How can I adjust the June 30 net worth for a fairer comparison?
Start by normalizing for one-time items (e.g., asset sales, restructuring charges). Then adjust for:
- Inflation: Revalue assets using current replacement costs if historical-cost accounting understates value.
- Market conditions: Compare inventory turnover or receivables aging to industry norms.
- Off-balance-sheet items: Add back liabilities like operating leases or unfunded pensions.
- Intangibles: Estimate fair value for unrecorded assets (e.g., brand equity) using valuation models.
Q: What’s the most common mistake analysts make when interpreting June 30 net worth?
Assuming it’s a measure of liquidity. Net worth reflects historical costs and accounting choices, not cash-generating ability. The mistake is treating net worth as an indicator of solvency—a company can have strong net worth but weak cash flow if its assets are illiquid (e.g., real estate). Always pair net worth analysis with cash flow statements and working capital ratios. For instance, a real estate developer might show high net worth on June 30, but if its projects are tied up in slow-moving markets, it could still face liquidity crises.
