Breaking Down the Numbers
The investment assets to net worth ratio is deceptively simple: divide your investable assets (stocks, bonds, private equity, real estate, crypto, etc.) by your total net worth (assets minus liabilities). The result is a percentage that reveals your exposure. A ratio of 60% suggests moderate risk; 80% or higher signals aggressive—or reckless—allocation. But the real insight comes from context. A 70% ratio for a 30-year-old tech founder may be prudent; for a 65-year-old approaching retirement, it’s a ticking time bomb. The ratio isn’t static. It shifts with life stages, market cycles, and personal risk tolerance. A young professional might start with a 90% ratio—most of their net worth tied to stocks or a startup—but as they age, they’ll likely reduce it to 50% or less, shifting toward cash, bonds, or tangible assets. The ratio also changes when liabilities (mortgages, loans) shrink or when new assets (a rental property, a business) are added. Ignoring these shifts is how investors turn paper wealth into real losses.The Verified Baseline
Publicly traded companies rarely disclose their investment assets to net worth ratio, but regulatory filings and proxy statements offer glimpses. For instance, Berkshire Hathaway’s Warren Buffett has historically maintained a ratio where cash and equivalents (a conservative asset) often exceed 20% of net worth, even during bull markets. This isn’t just about liquidity—it’s a deliberate choice to preserve capital when others are overleveraged. In contrast, a leveraged buyout firm like KKR might have a ratio where private equity stakes dominate, meaning 70%+ of net worth is tied to illiquid, high-risk assets. For individuals, the ratio becomes clearer in legal disputes or financial disclosures. When Elon Musk’s net worth was called into question during his Twitter acquisition, analysts pored over his investment asset allocation—publicly traded Tesla stock vs. private ventures like Neuralink—to estimate how much of his reported $260 billion was liquid versus speculative. The ratio wasn’t just a number; it was evidence of how much of his wealth was exposed to volatility. Similarly, when Mark Zuckerberg sold Facebook shares to fund his "Year of Travel," his investment assets to net worth ratio dropped sharply, signaling a shift from growth assets to consumption.What the Estimates Suggest
Industry estimates suggest that the average U.S. household allocates around 50% of net worth to investment assets, with the remainder in home equity, retirement accounts, and cash. However, this masks stark disparities. Households in the top 1% reportedly have ratios closer to 70-80%, with heavy concentrations in private equity, hedge funds, and illiquid ventures. Meanwhile, the median household—where most wealth is tied to home equity—may have a ratio closer to 30-40%, meaning two-thirds of their net worth is in a single, non-diversified asset. For ultra-high-net-worth individuals, the ratio often reflects strategic concentration. A family office might hold 90% of net worth in alternative investments (real estate, art, venture capital) while maintaining only 10% in liquid assets—a deliberate choice to generate outsized returns but at the cost of accessibility. The risk? A single downturn in private markets can erase decades of wealth. Conversely, a ratio below 40%—common among retirees—may indicate opportunity cost: too much wealth is locked in low-yielding bonds or cash, failing to keep pace with inflation.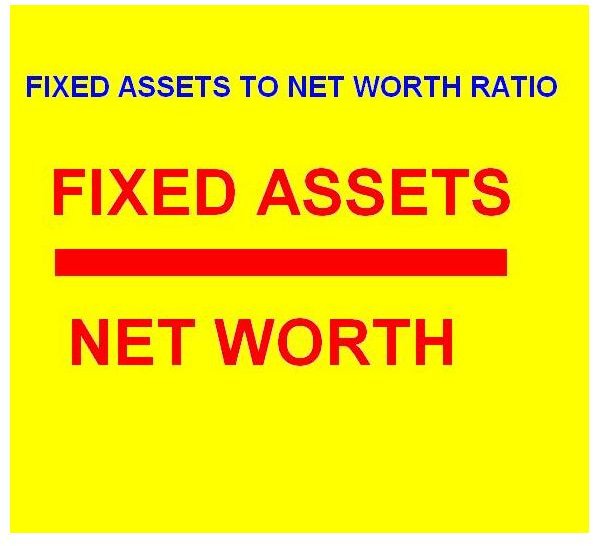
Case Study: A Closer Look
Consider the portfolio of a mid-career physician in their late 40s, with a net worth of $5 million. Their allocation might look like this: - Public equities (ETFs, individual stocks): 40% - Private practice ownership (illiquid): 30% - Real estate (rental properties): 15% - Retirement accounts (401k, IRA): 10% - Cash and equivalents: 5% Here, the investment assets to net worth ratio is roughly 90%, but the breakdown reveals hidden risks. While stocks and real estate are diversified, the private practice is a single-point failure: a malpractice lawsuit or a shift in healthcare policy could wipe out 30% of net worth overnight. The low cash reserve (5%) means they lack dry powder to buy opportunities or cover emergencies. The physician’s ratio would look far different if they’d sold the practice years earlier, locking in gains and diversifying into bonds or commodities. The ratio isn’t just a number—it’s a stress test. If their practice value drops 20%, their net worth plummets proportionally. If they’d maintained a 60% ratio instead, the impact would be far less severe."Your net worth is a snapshot; your investment assets to net worth ratio is the motion picture. It shows you where you’re vulnerable before the crisis hits." — Morgan Housel, The Psychology of Money
| Factor | Estimated Impact on Ratio |
|---|---|
| Selling illiquid assets (e.g., private business) | Could reduce ratio from 90% to 60%+ if proceeds are reinvested in liquid assets. |
| Market downturn (-20% in equities) | Ratio remains high, but net worth drops by ~18% (assuming 90% exposure). |
| Increasing cash reserve to 20% | Ratio drops to ~70%, improving liquidity but potentially reducing long-term growth. |
| Adding a diversified bond allocation (15%) | Ratio stays similar (~85%), but risk profile improves. |
| Leveraging debt to acquire more assets | Ratio may rise temporarily, but net worth could decline if liabilities exceed asset appreciation. |
What This Means Going Forward
The investment assets to net worth ratio is becoming a non-negotiable metric for financial planners, especially as markets grow more volatile. The 2022 correction exposed how many investors had ratios north of 80%, assuming perpetual growth. When stocks fell 20%, those portfolios saw net worth declines of similar magnitude—despite years of accumulation. The lesson? Ratios above 70% are a red flag unless you’re in the accumulation phase with a long time horizon. For institutions, the ratio is a governance issue. Endowments and pension funds now track their investment asset concentration more closely, ensuring no single asset class exceeds 30-40% of net worth. The ratio isn’t just about returns; it’s about preserving the principal that future generations depend on. For individuals, the takeaway is simpler: the higher your ratio, the more you need a contingency plan. That could mean holding more cash, diversifying into tangibles, or accepting that your wealth will grow slower but safer.
Conclusion
The investment assets to net worth ratio is the financial equivalent of a stress test. It doesn’t tell you how much you’re worth—it tells you how much of that worth is at risk. In an era of low interest rates, high asset valuations, and geopolitical uncertainty, ignoring it is financial malpractice. The ratio forces you to confront a harsh truth: wealth isn’t just about growth; it’s about survival. The best investors don’t just chase returns—they manage exposure. They ask: What happens if this asset class corrects? What if I need liquidity tomorrow? The answers lie in the ratio. And in a world where one bad trade or one unforced error can unravel decades of planning, that ratio is the only number that truly matters.Comprehensive FAQs
Q: How often should I calculate my investment assets to net worth ratio?
At least annually, or whenever there’s a major life change—selling an asset, taking on debt, or shifting career stages. Quarterly checks are ideal for high-net-worth individuals with volatile portfolios. The ratio isn’t static; it evolves with your financial life.
Q: What’s a “healthy” investment assets to net worth ratio?
There’s no universal answer, but 50-60% is a common target for balanced growth and safety. Aggressive investors (young, long time horizon) might aim for 70-80%, while conservative investors (near retirement) should cap it at 40-50%. The key is alignment with your risk tolerance and liquidity needs.
Q: Does my home equity count toward the ratio?
No—only investable assets (stocks, bonds, private equity, crypto, etc.) are included. Home equity is a separate component of net worth. Some advisors treat rental properties as investment assets, but primary residences are typically excluded unless they’re leveraged for income.
Q: Can a high ratio ever be a good thing?
Yes, but only under specific conditions: if you’re in accumulation mode (20-30 years until retirement), have a diversified portfolio, and can tolerate volatility. For example, a 35-year-old with 80% in stocks and no debt might thrive in a high-ratio strategy. However, if you’re leveraged or nearing retirement, a high ratio becomes a liability.
Q: How does debt affect the ratio?
Debt doesn’t directly change the ratio, but it amplifies risk. A high ratio with significant liabilities (e.g., a leveraged real estate portfolio) means a market downturn could wipe out both asset gains and force liquidation to cover debt. The ratio alone doesn’t show leverage—you must also track your debt-to-net-worth ratio for a full picture.
Q: What’s the biggest mistake people make with this ratio?
Assuming a high ratio means they’re “all in” on growth—when in reality, they’ve overconcentrated in a single asset class (e.g., crypto, a single stock, or a private business). The ratio doesn’t reveal diversification; it only shows exposure. Two portfolios with a 70% ratio can have wildly different risk profiles if one is in ETFs and the other in a single startup.
