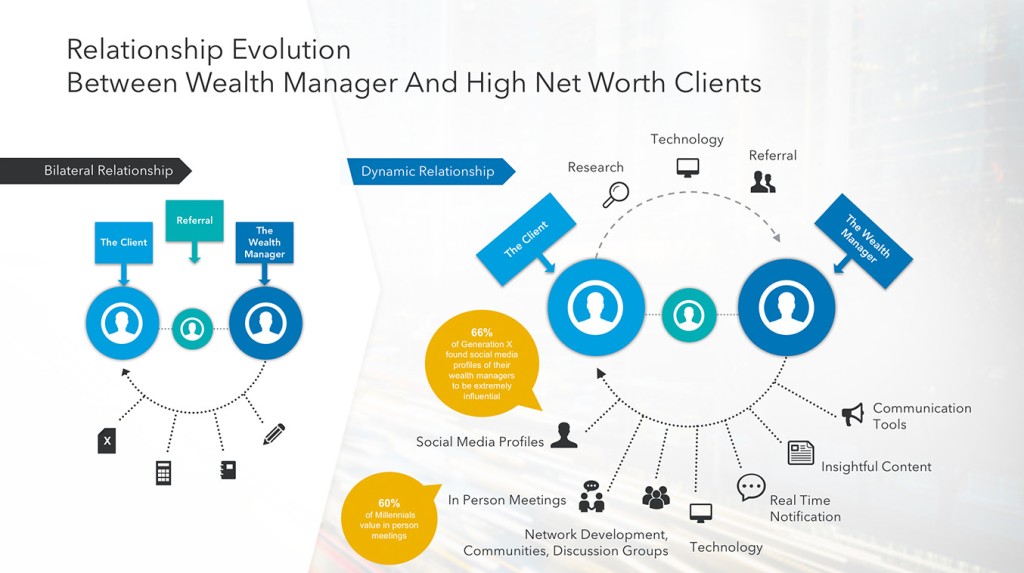
Breaking Down the Numbers
The financial services industry treats what is high net worth client? as a spectrum, not a binary category. At its core, the definition hinges on liquid investable assets—cash, stocks, bonds, and other easily tradable holdings. However, the threshold varies by region and by the institution making the classification. In the U.S., many firms adopt the $1 million mark (excluding primary residence) as a starting point, while European private banks often look at €3 million or more. The discrepancy isn’t arbitrary; it reflects differences in cost of living, tax structures, and the types of services these clients expect. What these numbers obscure is the non-liquid wealth that often dwarfs the liquid portion. A real estate portfolio valued at $20 million might be illiquid, yet it could represent the bulk of a client’s net worth. Similarly, a family business passed down for generations might not appear on a balance sheet but could be the foundation of their financial security. The what is high net worth client? label thus becomes a shorthand for a far more complex financial ecosystem—one where advisors must navigate valuation challenges, succession risks, and the emotional weight of legacy assets.The Verified Baseline
Publicly available data confirms that what is high net worth client? status is tied to access, not just asset size. Studies from organizations like Capgemini and RBC Wealth Management consistently show that these clients hold disproportionate influence in global capital flows. For example, the number of individuals with $30 million or more in investable assets grew by 12% annually between 2018 and 2023, according to industry reports. This growth isn’t uniform; it’s concentrated in cities like New York, London, Zurich, and Hong Kong, where financial infrastructure supports complex wealth structures. The verified baseline also includes behavioral patterns. High net worth clients tend to: - Hold multiple bank accounts across jurisdictions, often for tax and currency diversification. - Use private wealth managers rather than digital platforms, valuing personalized service over algorithm-driven advice. - Engage in philanthropy at scale, with giving strategies that align with dynastic wealth preservation. - Seek alternative investments—private equity, hedge funds, and even collectibles—where traditional markets fall short. These behaviors aren’t just preferences; they’re operational necessities for preserving and growing wealth at this level.What the Estimates Suggest
Industry estimates paint a picture of what is high net worth client? as a highly fragmented group, with significant variations by age, origin, and risk tolerance. For instance, ultra-high-net-worth individuals (UHNWIs), defined as those with $30 million+, are estimated to control $50 trillion in assets globally, according to Knight Frank. Yet this wealth isn’t static; it’s highly mobile, with clients frequently relocating for tax advantages or political stability. Estimates suggest that 30% of UHNWIs hold passports from more than one country, a figure that underscores the need for advisors with cross-border expertise. The estimates also highlight a generational divide. Younger high net worth clients—often self-made entrepreneurs or tech heirs—tend to favor digital engagement (e.g., robo-advisory tools for portfolio monitoring) alongside traditional services. In contrast, older clients, particularly those from established families, prioritize discretion and legacy planning. This divide isn’t just about age; it reflects differing trust models. A 40-year-old tech founder might trust a fintech platform to manage crypto holdings, while an 80-year-old industrialist will insist on face-to-face meetings with a Swiss private banker. The what is high net worth client? label thus masks subcultures within the segment, each with distinct expectations.
Case Study: A Closer Look
Consider the case of a European family with a $50 million portfolio, primarily in real estate and European equities. Their wealth manager, based in Geneva, had long positioned them as a high net worth client—until the family decided to expand into U.S. commercial real estate. The shift revealed critical gaps in their existing advisory structure: their Swiss bank lacked the local knowledge for U.S. zoning laws, and their tax planner hadn’t accounted for the BEAT (Base Erosion and Anti-Abuse Tax) provisions in the IRS code. The family’s liquid assets dropped by 15% over two years—not from market losses, but from unexpected tax liabilities and legal fees. The incident underscored a critical truth about what is high net worth client? management: specialization matters. The family’s advisor, while skilled in European wealth structures, failed to recognize that their client’s global ambitions required a hybrid team—one with U.S. real estate experts, cross-border tax attorneys, and a compliance officer familiar with FATCA regulations. The lesson wasn’t just about asset size; it was about adapting infrastructure to match evolving financial strategies."We assumed our wealth manager understood 'high net worth'—but they didn’t understand 'global high net worth.' The difference cost us millions." — Anonymized client, European family office
| Factor | Estimated Impact |
|---|---|
| Lack of U.S. real estate expertise | Delayed deals by 6–12 months, leading to higher acquisition costs |
| Unaccounted BEAT provisions | Additional tax burden of ~$3 million over two years |
| No FATCA compliance review | Potential penalties (though avoided via last-minute restructuring) |
| Over-reliance on Swiss banking model | Missed opportunities in U.S. syndication financing for larger deals |
What This Means Going Forward
The evolving definition of what is high net worth client? is reshaping financial services. Firms that once competed on minimum asset thresholds are now differentiating through niche expertise. For example, family offices—once the domain of the ultra-wealthy—are now being replicated by firms targeting $10 million+ clients, offering concierge-like services for everything from school admissions to private jet logistics. This democratization of luxury services is blurring the lines between traditional wealth management and premium lifestyle consulting. The shift also reflects a tech-driven transformation. High net worth clients, particularly younger ones, expect seamless digital integration—AI-driven portfolio analytics, blockchain-based asset tracking, and real-time reporting that rivals corporate dashboards. Yet, paradoxically, they still demand human oversight for high-stakes decisions. The future of serving what is high net worth client? lies in hybrid models: leveraging technology for efficiency while maintaining high-touch relationships for strategy. Firms that fail to strike this balance risk losing clients to competitors who offer both scale and personalization.
Conclusion
The question what is high net worth client? isn’t static—it’s a moving target shaped by economics, technology, and shifting global power dynamics. What remains constant is the complexity of managing wealth at this level. It’s not just about protecting assets; it’s about orchestrating them across legal jurisdictions, generational transitions, and ever-changing market conditions. The clients who thrive are those who recognize that wealth management is as much about risk mitigation as it is about growth. For advisors and institutions, the takeaway is clear: one-size-fits-all approaches won’t suffice. The high net worth client of 2024 demands agility, specialization, and a willingness to challenge conventional wisdom. Those who treat the label as a checklist—rather than a starting point for deeper engagement—will find themselves on the wrong side of a rapidly evolving landscape.Comprehensive FAQs
Q: How do financial institutions define a high net worth client?
Definitions vary by firm and region, but the most common threshold is $1 million in liquid assets (excluding primary residence). Some institutions, particularly private banks, may require $5 million or more. The key distinction lies in service expectations: high net worth clients typically expect dedicated relationship managers, customized investment strategies, and access to exclusive opportunities like private placements or concierge services. Institutions often use tiered segmentation (e.g., HNW, UHNW, VEB—Very Exceptional Business) to align resources with client needs.
Q: Can a high net worth client also be considered "mass affluent"?
No. While the terms are sometimes conflated, they describe distinct financial profiles. Mass affluent individuals typically have $100,000–$1 million in investable assets and may use digital platforms or robo-advisors. High net worth clients, by contrast, require human-centric, complex solutions—such as estate planning across multiple jurisdictions, private banking services, or access to alternative investments. The service model is the primary differentiator: mass affluent clients often seek cost efficiency; high net worth clients prioritize tailored expertise.
Q: Do high net worth clients always use private banks?
Not exclusively. While private banks are a common choice for ultra-high-net-worth individuals (UHNWIs), many high net worth clients (those with $1–$30 million) use a mix of traditional banks, wealth managers, and boutique firms. The decision depends on jurisdiction, tax strategy, and personal preference. For example, a client in Singapore might use DBS Private Banking for Asia-focused services while maintaining accounts in Swiss private banks for discretion. The trend toward multi-bank relationships has grown as clients seek specialized services (e.g., art advisory, aviation finance) that no single institution can provide.
Q: How does geography affect high net worth client status?
Geography plays a critical role in defining what is high net worth client? due to tax laws, currency values, and cost of living. For instance, a $5 million portfolio in Zurich may grant access to elite private banking services, while the same sum in Miami might only qualify for premium advisory without the same level of exclusivity. Additionally, tax residency rules (e.g., Switzerland’s wealth tax, the U.S. FBAR requirements) can elevate or limit a client’s status. Clients in low-tax jurisdictions (e.g., Dubai, Singapore) may appear wealthier on paper than peers in high-tax regions (e.g., California, France) due to net worth after taxes. Advisors must account for these localized factors when assessing a client’s true financial standing.
Q: What’s the biggest misconception about high net worth clients?
The most persistent myth is that all high net worth clients are the same—or that wealth alone guarantees financial sophistication. In reality, many self-made high net worth individuals lack formal financial education and rely heavily on advisors for basic tax and investment strategies. Conversely, inherited wealth doesn’t always translate to smart wealth management; dynastic families often struggle with succession planning, trust structures, and liquidity crises. Another misconception is that these clients only care about returns. While performance matters, security, privacy, and legacy preservation frequently outweigh short-term gains. Advisors who assume one-size-fits-all strategies risk misunderstanding their clients’ true priorities.
Q: Can a high net worth client lose their status?
Absolutely. High net worth status isn’t permanent; it’s earned and maintained through active wealth management. Factors that can erode status include:
- Poor investment decisions (e.g., overconcentration in a single asset class).
- Unplanned liquidity events (e.g., divorces, lawsuits, or ill-timed real estate sales).
- Tax missteps (e.g., failing to report foreign accounts or underestimating capital gains).
- Inflation or market downturns that reduce portfolio value below the threshold.
- Lifestyle spending that outpaces income (e.g., excessive luxury purchases without asset growth).
Q: How do high net worth clients differ from ultra-high-net-worth individuals (UHNWIs)?
The primary distinction lies in asset size and complexity:
- High net worth (HNW): Typically $1–$30 million in liquid assets. These clients may use wealth managers, private banking, or boutique firms but often still engage with traditional banks for day-to-day needs. Their portfolios may include diversified equities, real estate, and private equity, but illiquid assets (e.g., family businesses) are less dominant.
- Ultra-high-net-worth (UHNWI): $30 million+, often with multi-generational wealth. UHNWIs frequently operate family offices, employ dedicated legal and tax teams, and access exclusive asset classes (e.g., rare art, wine, or aviation). Their challenges—succession planning, dynastic trusts, and cross-border wealth transfer—require enterprise-level solutions that HNW clients may not need.
